
Banks
The World’s Top 10 Banks in 2025: Power, Risk, and the New Financial Order

China’s trillion-dollar banking giants dominate global finance—but their real estate exposure could reshape the entire system
The global banking landscape has reached an inflection point. As we close 2025, the world’s 100 largest banks control $95.5 trillion in assets—a figure that eclipses the GDP of most nations combined. Yet beneath this staggering concentration of financial power lies a paradox that should concern policymakers and investors alike: the banks with the biggest balance sheets may not be the most resilient.
Four Chinese state-owned institutions—Industrial and Commercial Bank of China, Agricultural Bank of China, China Construction Bank, and Bank of China—occupy the top spots in the global rankings by total assets. Meanwhile, JPMorgan Chase, the largest U.S. bank and fifth globally, commands the highest market capitalization at nearly $788 billion, signaling that investors value American banking efficiency over sheer size.
This divergence tells us something critical: in 2025’s banking world, scale and strength are no longer synonymous.
The Rankings: Size Doesn’t Equal Safety
Based on the latest data from S&P Global Market Intelligence and financial reports through Q4 2024, here are the world’s ten largest banks by total assets:
1. Industrial and Commercial Bank of China (ICBC) – $6.6 trillion in assets. The world’s largest bank by assets continues to benefit from Beijing’s infrastructure spending and state support, operating over 16,000 branches globally. Yet non-performing loan ratios are forecast to rise to 5.4-5.8% in 2025-2027, up from 5.1% in 2024, driven primarily by real estate exposure.
2. Agricultural Bank of China – Approximately $5.8 trillion. Deeply embedded in rural China’s financial system, ABC faces similar real estate headwinds while supporting Beijing’s rural development priorities.
3. China Construction Bank – Around $5.6 trillion. As its name suggests, CCB’s fortunes are intimately tied to China’s construction sector, making it particularly vulnerable to the ongoing property crisis.
4. Bank of China – Approximately $4.8 trillion. The most internationally oriented of China’s “Big Four,” with significant foreign operations, yet still carrying substantial domestic real estate exposure.
5. JPMorgan Chase – $4.0 trillion in assets. The most profitable large bank globally, JPMorgan’s return on equity reached 18% in 2024, demonstrating that American banks achieve more with less. With 5,021 domestic branches and sophisticated digital platforms, JPMorgan exemplifies the “smaller but mightier” model.
6. Bank of America – $2.65 trillion. The second-largest U.S. bank maintains 3,624 domestic branches and has aggressively invested in digital banking, serving millions through its AI-powered virtual assistant Erica.
7. HSBC Holdings – $3.0 trillion. Europe’s largest bank by assets, HSBC is navigating a strategic pivot toward Asia while managing legacy exposures across its global footprint.
8. BNP Paribas – Approximately $2.9 trillion. France’s largest bank and a European leader in investment banking and corporate finance.
9. Crédit Agricole – Around $2.6 trillion. Another French banking giant with significant retail and corporate banking operations across Europe.
10. Citigroup – $1.84 trillion. Once the world’s largest bank, Citi has streamlined operations but maintains an unparalleled global presence with operations in 109 foreign branches.
The Elephant in the Boardroom: China’s Real Estate Time Bomb
Here’s what the asset rankings don’t show: Chinese banks’ exposure to real estate loans has created systemic vulnerabilities, with non-performing asset ratios for property development loans potentially reaching 7% by 2027 if markets stabilize—and much worse if they don’t.
Walk through any major Chinese city today and you’ll see the problem in concrete and steel: unfinished apartment towers, silent construction sites, and the ghostly remains of a $52 trillion property bubble that’s now deflating. Chinese policymakers removed price caps on housing in 2024, allowing eligible families to buy unlimited homes in suburban areas, a desperate attempt to revive demand that has largely failed.
The human cost is staggering. Mid-2025 data shows mortgage non-performing loan rates at listed banks rising overall, with some banks up more than 20 basis points. Millions of Chinese homeowners now hold “underwater” mortgages—properties worth less than their outstanding loans. Some have lost both their homes and down payments yet still owe banks hundreds of thousands of yuan.
For the Big Four Chinese banks, this isn’t just a loan quality issue—it’s an existential question. Banks’ exposure to housing and local government debt declined to 20.7% in Q4 2024 from 22.2% a year earlier, but that still represents trillions in potentially troubled assets. Beijing’s response? Issuing 500 billion yuan in special treasury bonds in 2025 to support bank recapitalization.
Think about that for a moment. The government that owns these banks is now having to inject capital into them to cover losses from lending that the government itself encouraged. It’s a circular firing squad of state capitalism.
American Excellence: Smaller, Smarter, More Profitable
Cross the Pacific and the banking model looks radically different. JPMorgan Chase’s annualized return on equity for Q2 2025 was 16.93%, a performance Chinese banks can only dream of. With roughly $4 trillion in assets—a third of ICBC’s size—JPMorgan generated comparable or superior profits through better risk management, superior technology, and diversified revenue streams.
American banks aren’t perfect. They face their own challenges: rising commercial real estate defaults, regulatory uncertainty around the Basel III endgame rules, and fierce competition from fintech disruptors. Yet their fundamental business model—strict capital requirements, transparent accounting, and market discipline—creates resilience.
The regulatory framework matters enormously. Basel III requires banks to maintain a minimum Common Equity Tier 1 ratio at all times, plus a mandatory capital conservation buffer equivalent to at least 2.5% of risk-weighted assets. U.S. implementation has been stricter than in many jurisdictions, forcing American banks to hold more capital but also making them genuinely safer.
Compare this to China, where banks have remained cautious about new property exposure, transferring housing risks to non-bank financial institutions. That’s not risk management—that’s risk concealment. The leverage doesn’t disappear; it just moves to less regulated corners of the financial system.
The Digital Divide: Innovation as the New Moat
Size and capital strength matter, but in 2025, technological sophistication increasingly separates winners from also-rans. DBS Bank’s AI investments are projected to reach 750 million Singapore dollars (about $577 million) in 2024 and surpass SG$1 billion in 2025. The Singapore-based bank has deployed over 1,500 AI and machine learning models across 370 use cases, from corporate risk assessment to customer service.
JPMorgan and Bank of America aren’t far behind. BofA’s Erica virtual assistant has handled billions of customer interactions, while JPMorgan uses AI for everything from fraud detection to trading strategies. Only 8% of banks were developing generative AI systematically in 2024, with 78% taking a tactical approach, but that’s changing rapidly.
The Chinese banks? They’re investing heavily in digital infrastructure, to be sure. Yet their technology serves a fundamentally different purpose: facilitating state-directed lending, monitoring transactions for political purposes, and supporting Beijing’s social credit systems. Innovation, yes—but innovation in service of control rather than customer value.
European banks occupy an uncomfortable middle ground. BBVA’s expansion of its OpenAI collaboration will see ChatGPT Enterprise rolled out to all 120,000 global employees, signaling serious AI ambitions. Yet European banks collectively lag their American and Asian peers in both investment and implementation.
Basel III Endgame: The Regulatory Reckoning
Speaking of uncomfortable positions, let’s address the regulatory elephant: the Basel III endgame. Under the original proposal, large banks would begin transitioning to the new framework on July 1, 2025, with full compliance starting July 1, 2028. The proposal would have resulted in an aggregate 16% increase in common equity tier 1 capital requirements for affected bank holding companies.
But here’s the twist: US regulators recently proposed to reduce capital requirements on the largest banks, bowing to intense industry lobbying and political pressure. The revised proposal now calls for only a 9% increase for global systemically important banks—still significant, but less onerous than originally planned.
This compromise may prove disastrous. The average leverage ratio of US global systemically important banks declined from a 2016 peak of 9% to about 7% in 2023 and has remained there. Banks have been gaming the system, increasing risk exposure while maintaining superficially healthy risk-weighted capital ratios.
Meanwhile, the European Central Bank and Bank of England have delayed their Basel III implementation, citing US inaction. We’re witnessing a potential regulatory race to the bottom—exactly what the Basel framework was designed to prevent.
The Geopolitical Wildcard: Trade, Tariffs, and Banking Stress
Banking doesn’t happen in a vacuum. International trade disputes and changes in tariffs are expected to influence the performance of banks, impacting asset quality and growth potential. If U.S.-China trade tensions escalate further—a real possibility given recent political developments—Chinese banks will feel the pain first and hardest.
Reciprocal tariffs between the US and China are exerting pressure on Chinese banks, particularly due to declining demand from export-oriented manufacturers. When factories close or cut production, loan defaults follow. It’s Economics 101, but at a scale that could destabilize the entire Chinese banking system.
American banks have their own trade exposure, of course, but it’s more diversified and often hedged. JPMorgan operates in over 100 countries. Citi, despite its shrinking footprint, remains the most truly global bank. They have options. Chinese banks, despite their size, remain heavily dependent on the domestic economy.
What This Means for 2026 and Beyond
So where does this leave us? Here’s my take, informed by twenty years covering this beat:
First, asset size is an increasingly misleading metric. ICBC’s $6.6 trillion balance sheet looks impressive until you examine what’s actually on it. Quality trumps quantity, and American banks demonstrate this daily through superior profitability and resilience.
Second, the Chinese banking system faces a reckoning. It’s not a matter of if, but when and how severe. Chinese banks were sitting on 3.2 trillion yuan ($440 billion) worth of bad loans by the end of September—a 33% increase from pre-Covid times. These numbers, from the banks themselves, are almost certainly understated.
Third, technology is creating a two-tier banking world. Banks that aggressively adopt AI, blockchain, and advanced analytics will dominate. Those that don’t will become utilities—low-margin, heavily regulated, and perpetually vulnerable to disruption.
Fourth, regulatory arbitrage is back with a vengeance. The Basel III endgame was supposed to eliminate it. Instead, we’re seeing regulators water down requirements in response to bank lobbying. This should terrify anyone who remembers 2008.
Finally, geopolitics increasingly dictates banking success. In an era of great power competition, owning a bank in Shanghai or New York means different things. Chinese banks serve the state; American banks serve shareholders (at least theoretically). European banks are caught in between, trying to navigate relationships with both powers while maintaining independence.
The Billion-Dollar Question
Here’s what keeps me up at night: We’ve seen this movie before. Massive banks, seemingly too big to fail, carrying hidden risks that regulators either can’t see or choose to ignore. Policymakers convinced that “this time is different” because of better capital rules, smarter supervision, or more sophisticated risk management.
It never is.
The difference in 2025 is that the risks are concentrated in banks that operate under fundamentally different rules. When—not if—the Chinese property crisis forces Beijing to choose between bank bailouts and economic growth, the ripples will reach far beyond Asia.
The world’s largest 100 banks account for $95.5 trillion in assets, up 3% year over year. That’s growth, yes, but it’s also concentration. Too much power, in too few hands, making too many bets on too few assumptions.
Jamie Dimon, CEO of JPMorgan, likes to say his bank could survive another 2008-style crisis. He’s probably right—JPMorgan is genuinely well-capitalized and well-managed. But could the global financial system survive a crisis originating in China’s $6 trillion banking sector?
That’s the question that should haunt every central banker and finance minister. Because in 2025, we’re not just worried about banks that are too big to fail. We’re worried about banks that are too big, too opaque, and too politically connected for anyone to fully understand the risks they carry.
The world’s top ten banks in 2025 aren’t just financial institutions. They’re nodes in a global system where everyone’s connected to everyone else through invisible chains of credit, derivatives, and counterparty risk. Pull one thread, and you might unravel the whole sweater.
Sleep tight.
The author is a Senior Opinion Columnist specializing in global finance and policy. Views expressed are personal.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


The third-quarter 2026 earnings season arrives with investors asking whether corporate profits justify expensive stocks and elevated financing costs. Reuters’ October 9 market preview identified major U.S. banks and the upcoming inflation data as key near-term events. An earnings preview should be careful with dates: a company’s announced release time is verifiable; its actual result is not known until published. Sources: Reuters market week ahead and Reuters chip demand report.
The important context competitors can overlook
Bank commentary can reveal credit quality, deposit pricing, commercial borrowing and investment-banking activity. In technology, watch the gap between AI revenue growth and the cost of building data centers. Consumer-facing businesses offer different clues: pricing power, discounting, spending patterns and margin pressure from transportation or labor. Each sector may be telling a different part of the economic story. For primary-source checks and current reporting, see Reuters market week ahead and Reuters market breadth. The key distinction is preview without inventing earnings that have not happened.
Bank profits, AI spending and consumer earnings reveal different parts of the economy. Separate scheduled announcements, management forecasts and confirmed quarterly results. Research cutoff: October 12, 2026; confirm developing facts before publication.
A practical way to use this information
For every results story, separate reported revenue, adjusted earnings, guidance and free cash flow. Compare the release with consensus only if the estimate is dated and sourced. Include management’s explanation of one-off gains or impairments, and quote the most meaningful risk disclosure. A company can beat a quarterly forecast yet fall if investors expected stronger forward guidance.
An earnings scorecard readers can actually use
| Metric | What it answers | Common misreading |
|---|---|---|
| Revenue | Did customers buy more? | Revenue growth automatically means cash generation |
| Operating margin | Did each dollar of sales produce more operating profit? | Temporary charges always reflect normal operations |
| Free cash flow | Was cash generated after major investments? | Noncash earnings and cash are interchangeable |
| Forward guidance | What is management signaling next? | Guidance is a confirmed future result |
For bank earnings, add credit-loss provisions and deposit costs; for AI firms, add capital expenditure and utilization. A fuller scorecard is more useful than the headline beat/miss framing seen in many fast earnings articles.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Which earnings matter most in October 2026? Large banks, leading chip companies and consumer businesses can help explain different pressures in the economy.
Does beating estimates guarantee a rally? No. Expectations for future growth and valuation often matter as much as the reported quarter.
The bank earnings signals that extend beyond Wall Street
Large banks often report early in earnings season and can provide a window into lending, deposits and the health of consumers and businesses. Net interest income indicates what a bank earns from assets such as loans after its funding costs, but it should be read alongside deposit pricing and balance-sheet changes. A rising interest margin may support profits while simultaneously raising financing costs for borrowers. Loan-loss provisions are another important signal: management estimates expected credit losses using assumptions that can change as the economic outlook changes.
Credit-card delinquencies, consumer balances and commercial real-estate exposure can reveal pockets of stress before broader indicators show deterioration. Yet one bank’s customer mix may not represent the entire nation. A lender focused on wealthy households could report very different trends from a bank serving customers with lower disposable incomes. Earnings articles should avoid treating an executive’s anecdote as an official macroeconomic statistic, even when the comment offers valuable context.
The AI spending test: orders are not profits
Technology companies may announce record capital expenditure, new data centers or faster AI-related revenue growth. Investors should ask where in the chain a figure sits. A chip order is revenue for a supplier only under relevant accounting conditions. A cloud provider’s capital investment is an expense or asset decision rather than proof that end-user services are profitable. Enterprise customers may test AI tools for months before committing to large long-term contracts. Demand can be strong and returns uneven at the same time.
Look at management’s guidance for capital expenditure, depreciation and expected utilization. Compare recurring revenue with one-time setup fees or equipment sales. Rising sales accompanied by escalating delivery costs may produce lower margins than expected. Conversely, an initially costly rollout may yield operating leverage as capacity fills. The correct question is whether management’s stated timetable is supported by reported progress, not whether the company uses the phrase “AI transformation.”
What consumer-company results can reveal
Retailers, restaurants, airlines and payment companies see different portions of household demand. Revenue growth can come from higher prices, more transactions, acquisitions or a change in product mix. Same-store sales help isolate performance at established outlets, but their precise definition varies by company. Gross margin can fall despite rising revenue when labor, transport and input costs increase. Strong premium product sales may coexist with financial pressure on budget shoppers. A useful consumer earnings article looks for such differences.
When a company raises its full-year forecast, identify the starting forecast and the assumptions that changed. Was the increase driven by demand, pricing, exchange rates or reduced expense? An earnings beat relative to analysts’ estimates can occur even if operating performance deteriorated from a year earlier. Readers deserve both comparisons. Future guidance may be more important to the share price than the prior quarter’s reported earnings, but the response can differ according to expectations already embedded in valuation.
How to read one earnings release in ten minutes
Start with the publication timestamp and confirm the quarter ended when you think it did. Read revenue, operating income, net income and cash flow before the chief executive’s prepared quotations. Compare with the corresponding prior-year quarter, not only the immediately preceding one for a seasonal business. Identify adjusted measures and find their reconciliation with generally accepted accounting figures. Check whether share buybacks altered earnings per share. Then review guidance, debt, capital expenditure and the transcript for questions management was reluctant to answer.
Finally, compare the share-price move with the broader sector and the timing of other macroeconomic news. A company may post strong numbers and fall because investors expected even stronger results; another can rise on less disappointing guidance. Avoid writing that “investors rejected the results” unless the evidence makes the causal link clear.
Build a rolling earnings scoreboard
For each selected company, use columns for release date, quarter, revenue, year-over-year growth, operating margin, EPS, free cash flow, guidance change and key management caveat. Mark any still-unreported company as scheduled, never “reported.” Link to the actual investor-relations release and update the row after publication. A screenshot or commentary from a secondary source can help explain reaction, but should not replace the issuer’s filing.
A reliable earnings hub is useful precisely because it separates the known from the anticipated. It helps readers compare banks, technology firms and consumer businesses without turning forecasts into facts or mistaking one impressive quarter for a universal economic conclusion.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
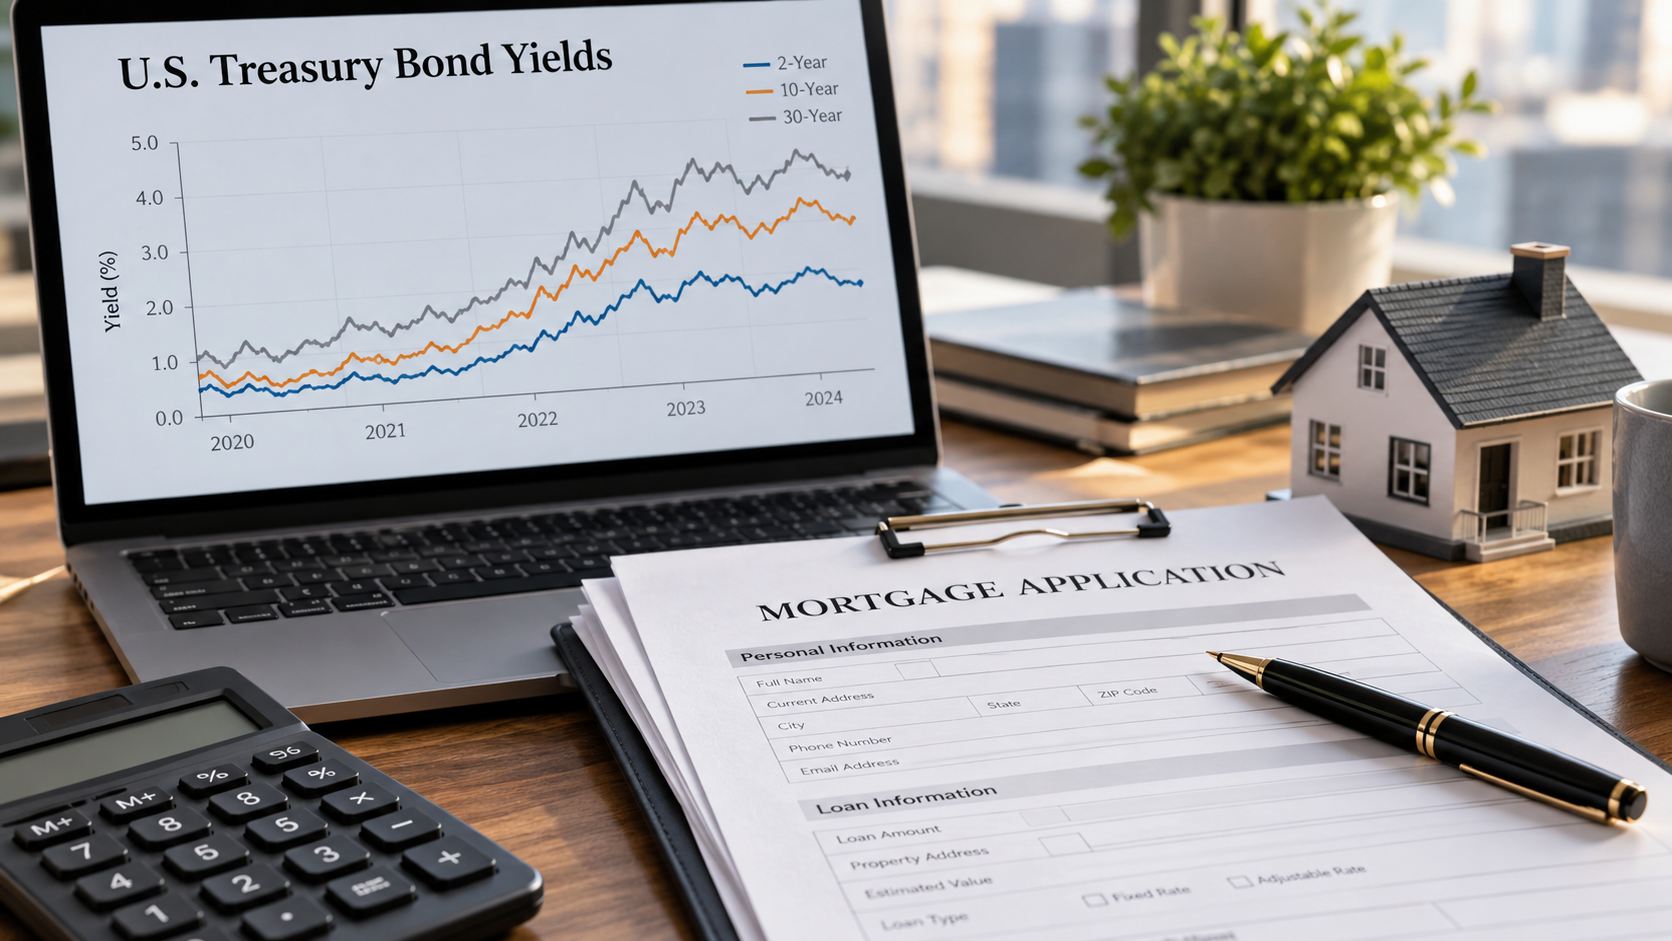
Long-term Treasury yields are the price signal linking government borrowing, mortgages, growth-stock valuations and the return available on safer assets. Reuters has highlighted an unusual 2026 divergence: shares near highs while longer-term bond yields have climbed. A bond yield is not the same as the Federal Reserve policy rate, and a large move in either can affect people differently depending on whether they borrow, save or invest. Sources: Reuters bond market analysis and Reuters market breadth.
The important context competitors can overlook
Bond prices generally fall when market yields rise. That inverse relationship explains why holders of long-duration bond funds can suffer losses even as the yields offered to new buyers become more attractive. Mortgage rates also reflect lending spreads, credit risk and other factors, so a single Treasury number cannot predict a specific home-loan offer. Companies with distant expected cash flows may be particularly sensitive to higher discount rates. For primary-source checks and current reporting, see Reuters bond market analysis and Investor.gov. The key distinction is translate bond math into household decisions.
Long-term Treasury yields connect bond markets to household borrowing and asset values. Higher yields can benefit new savers while hurting some borrowers and existing bondholders. Research cutoff: October 12, 2026; confirm developing facts before publication.
A practical way to use this information
Compare yields at consistent maturities rather than mixing two-year and ten-year readings. A homebuyer should assess monthly payment affordability at an actual lender quote. A saver choosing between a short-term bill and a long-term fund should consider liquidity needs and interest-rate risk. For an investor, the useful question is what rate assumptions are embedded in a company valuation, not whether “6%” makes a dramatic headline.
A simple rate-shock example
Imagine an existing long-duration bond fund whose duration is eight years. A simplified duration approximation suggests a one-percentage-point increase in yield could mean about an 8% price decline, before convexity, income and other effects. This is illustrative, not a forecast for a named fund. A short-term Treasury instrument with far lower duration usually reacts less to the same yield shock.
That distinction makes a practical difference for readers considering an emergency fund versus retirement money they can invest for a decade. The current market narrative described by Reuters should prompt a discussion of time horizon, not a blanket instruction to abandon bonds.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Are higher Treasury yields always bad?
No. New fixed-income savers may earn more, while existing long-duration bond prices can decline.
Does the Fed set the ten-year Treasury yield?
No. It influences conditions, but market expectations and term premiums also matter.
Why the ten-year yield influences everyday borrowing
The 10-year U.S. Treasury yield is an important benchmark for longer-term financing because it reflects the return investors require to hold government debt with that maturity. Mortgage rates do not equal the 10-year yield, but lenders consider Treasury markets, mortgage-backed securities, credit risk, servicing costs and competition when setting offers. If investors demand a higher return across long-term bonds, mortgage borrowing can become more expensive even without an immediate increase in the Federal Reserve’s short-term policy rate.
Suppose a buyer finances $300,000 over 30 years with a fixed-rate mortgage. At an illustrative 6% annual interest rate, principal and interest are roughly $1,799 per month; at 7%, they are roughly $1,996. The difference of about $197 per month excludes taxes, insurance, fees and other ownership costs. It demonstrates why a change in borrowing conditions can outweigh a modest change in a home’s asking price. Real quotes depend on the borrower’s circumstances and market conditions, not merely the Treasury yield reported in a news article.
Why bond prices and bond yields move in opposite directions
A conventional fixed-coupon bond promises specified payments. When newly issued securities offer higher yields, an existing bond with a lower coupon generally must trade at a lower price to attract buyers. The opposite happens when market yields fall. Duration measures a bond’s sensitivity to interest-rate changes. As an approximate illustration, a portfolio with an effective duration of seven years could lose about 7% in price if relevant yields rise by one percentage point, before other effects. The relationship is approximate and can vary with convexity, changing spreads and portfolio holdings.
For savers, a higher yield can be welcome if they are buying newly issued securities and can hold them under suitable circumstances. For owners of existing long-duration bonds, the same move can produce mark-to-market losses. Investors seeking near-term stability should understand the distinction between a bond’s redemption terms and the market price they might receive if they must sell before maturity. Credit risk also differs between Treasury securities and corporate or municipal bonds.
The yield curve tells a story, but not one prediction
The yield curve plots interest rates across maturities. Its shape can reflect expectations for growth, inflation, monetary policy and compensation for holding longer bonds. An inverted curve has often been studied as a recession signal, yet neither inversion nor steepening guarantees a specific economic outcome. A steepening curve may arise because investors expect stronger future activity, higher inflation or greater long-term borrowing supply. The underlying cause matters more than the shape alone.
Distinguish nominal yields from real yields after expected inflation. If a nominal Treasury yield rises because inflation expectations rise, the investor’s purchasing-power return may not improve nearly as much as the headline suggests. Treasury Inflation-Protected Securities provide another reference point, though their market prices and practical suitability also require care. Useful analysis compares inflation expectations, real yields and nominal yields rather than describing all higher rates as a sign of healthy growth.
A decision framework for households
Borrowers should compare multiple complete loan offers, including interest rate, annual percentage rate, closing costs and applicable points. A lower headline rate with very large upfront fees may not be cheaper for someone planning to move or refinance. Depositors should distinguish variable savings-account APYs from yields locked by certain fixed-term products. Bond-fund investors should review duration, credit quality, expenses and possible withdrawals. Stock investors should consider how higher discount rates affect the value assigned to future profits, particularly where profits are expected many years ahead.
No single financial product becomes universally best because yields reach a round number. A retiree seeking predictable cash flow, a first-time homebuyer and a technology-company investor face different tradeoffs. Their financial decisions are better guided by time horizon, liquidity and risk tolerance than by a prediction of where the yield will be next week.
The key variables to monitor
For a coherent market story, compare the 2-year and 10-year Treasury yields, current Fed communications, the latest inflation data and changes in bond-market liquidity. Track the time at which each observation was made. Also distinguish a policy announcement from a market-implied forecast; futures pricing can change significantly with new information. Where a report cites a historic high, specify the exact maturity and comparison period. Generalized phrases such as “rates hit their highest level” can conceal important differences.
Relevant data and explanations are available from the U.S. Treasury and Federal Reserve. Those are appropriate baselines for an article readers may use to understand mortgages, bonds and savings decisions.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
A savings account’s value comes from accessible, insured cash and transparent net earnings—not simply the largest advertised APY. Research cutoff: October 12, 2026; confirm developing facts before publication.
What is happening and why readers are searching
A high-yield savings account should be judged by what a depositor actually earns and how readily the money can be accessed, not only by a prominent introductory APY. For someone building an emergency fund, deposit insurance, account terms, transfer speed and possible rate changes can be more important than a small advertised advantage. Sources: FDIC Money Smart and Reuters bond market analysis.
The important context competitors can overlook
APY reflects compounding over a year, whereas an account’s stated interest rate may differ. Banks can change variable savings rates. Promotional accounts may have balance limits, direct-deposit requirements or fees that reduce an apparent benefit. FDIC insurance covers eligible deposits at insured banks subject to applicable ownership-category limits; a similar-looking fintech app is not automatically the bank that holds the funds. For primary-source checks and current reporting, see FDIC Money Smart and Investor.gov. The key distinction is evergreen buyer intent with no invented current bank rates.
A practical way to use this information
Calculate expected earnings at the amount you intend to deposit. For example, a hypothetical $10,000 balance at 4.00% APY would earn roughly $400 over one year if the APY stayed constant and there were no intervening transactions. That is arithmetic, not a claim that a particular institution offers 4%. Verify rates on the provider’s own page the day you publish and compare at least three insured options.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Are high-yield savings rates fixed? Most are variable and can change.
Should I choose the bank with the largest advertised APY? Also assess insurance, fees, balance rules and withdrawal access.
APY is useful only if you understand how it works
Annual percentage yield estimates how much an account earns over a year when interest is compounded according to the bank’s terms, assuming the rate remains unchanged and other relevant conditions are met. It differs from a simple annual interest rate because it accounts for compounding. Many savings rates are variable, which means today’s advertised APY can change after the account is opened. A bank may also require a certain balance, a qualifying deposit or another relationship to earn its highest advertised tier. Read the conditions before assuming every dollar in the account will earn the headline figure.
Consider $10,000 held for one year at a hypothetical constant APY of 4.0%. The approximate earnings would be $400 before tax. At 3.5%, the corresponding amount would be $350, a $50 difference. If the higher-rate account charges $10 per month in fees, that fee could more than eliminate the apparent advantage. This comparison illustrates why small rate differences should be evaluated alongside minimum balances, fees and the effort of moving money repeatedly.
Deposit protection is not the same as investment safety
A typical U.S. bank savings account may be eligible for FDIC insurance if the bank is insured and the deposits fall within applicable ownership-category limits. Federally insured credit unions operate under a separate NCUA framework. The standard $250,000 limit is not a simple promise that every individual has exactly one $250,000 cap across every account. Coverage depends on the institution, ownership category and how accounts are titled. Readers with large balances should check the official calculators rather than assume a marketing phrase tells the whole story.
A brokerage cash-management product, money-market mutual fund and bank savings account can look similar in an app while carrying different protections. Some sweep arrangements distribute money among partner banks; the exact program terms matter. A money-market mutual fund is not the same as an FDIC-insured bank deposit. Read whether the product is a deposit or an investment, who holds the funds and when coverage begins. Official explanations are available at FDIC and NCUA.
Liquidity: when will the money actually be available?
An emergency fund is valuable because it can be accessed at the moment an emergency occurs. Online savings accounts may support electronic transfers but not immediate cash withdrawal. Moving funds between institutions can involve transfer limits, cutoffs, identity checks or processing delays. If a bank advertises a faster service, verify whether it applies to your linked account and requested amount. A high APY is less useful if a household cannot pay an urgent medical bill or repair invoice when needed.
People keeping a larger emergency reserve can consider a modest amount in an immediately accessible transaction account and the remainder in savings, depending on circumstances. That is a liquidity-management principle, not an endorsement of a particular bank. Avoid oversimplified rules such as “always keep exactly three months.” The appropriate reserve depends on employment stability, housing obligations, dependents and insurance coverage.
How to compare a promotional rate fairly
Create a one-page comparison with offered APY, stated promotional expiration, required actions, fee schedule, insurance status, transfer speed, minimum opening deposit and any cap on the qualifying balance. Record the date because rates and offers can change. If one bank offers an incentive for opening an account, calculate the conditions needed to receive it and whether the benefit offsets lost interest, potential fees or complexity. A high introductory offer can still be worthwhile, but it should be analyzed over the likely holding period rather than the first week.
Do not compare one institution’s APY with another institution’s simple interest rate without adjusting for compounding. Likewise, avoid extrapolating a short-term bonus as though it repeats every year. Rate cuts or increases by the Federal Reserve may influence savings rates but do not require all banks to adjust at the same speed or by the same amount.
A decision checklist before moving savings
Verify the institution’s legal name and insurance status using official tools; compare accounts with the same estimated balance; confirm account access and customer-support options; calculate after-fee returns; test transfer arrangements with a modest amount if appropriate; and keep records of any promotional terms. Be skeptical of an unusually high guaranteed return marketed through social media, especially if it asks you to move money to a personal account or purchase cryptocurrency first.
The best high-yield savings account is not automatically the one with the highest figure on a comparison page. It is the one whose return, protection, accessibility and requirements fit the depositor’s real purpose for holding cash.
Frequently asked savings questions
Is a high-yield account better than a certificate of deposit?
Not universally. A variable-rate savings account often offers convenient access while its APY can change. A certificate of deposit may provide a specified rate for a term, with consequences for early withdrawals. A person saving for an unpredictable medical cost may value flexible access; someone with funds earmarked for a known later date may compare fixed-term options. The comparison should include inflation, withdrawal needs and any penalties.
Do I have to move banks whenever an APY changes?
No. Repeated transfers require time and can create administrative mistakes. Estimate the dollar difference for your actual balance and expected holding period. A quarter-point annual APY difference on $5,000 is only around $12.50 before tax over a full year if rates remain unchanged. That may or may not justify opening and managing a new account.
Can a savings-account rate be guaranteed?
A typical variable savings APY is not fixed for years. Read the product disclosures and distinguish introductory offers from continuing rates. Any claim of exceptional guaranteed yields with no risk deserves careful scrutiny, particularly when advertised outside regulated bank channels. Verify deposit insurance independently and never rely only on a screenshot of a comparison ranking.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

OP-ED:The AI Race Has No Single Winner — And Pakistan Must Choose Its Own Future

VA Disability Rates Increase 2027: The Confirmed 3.6% COLA Explained

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025