
China Economy
China Chose Political Control Over Fixing Its Deflation Trap in 2026

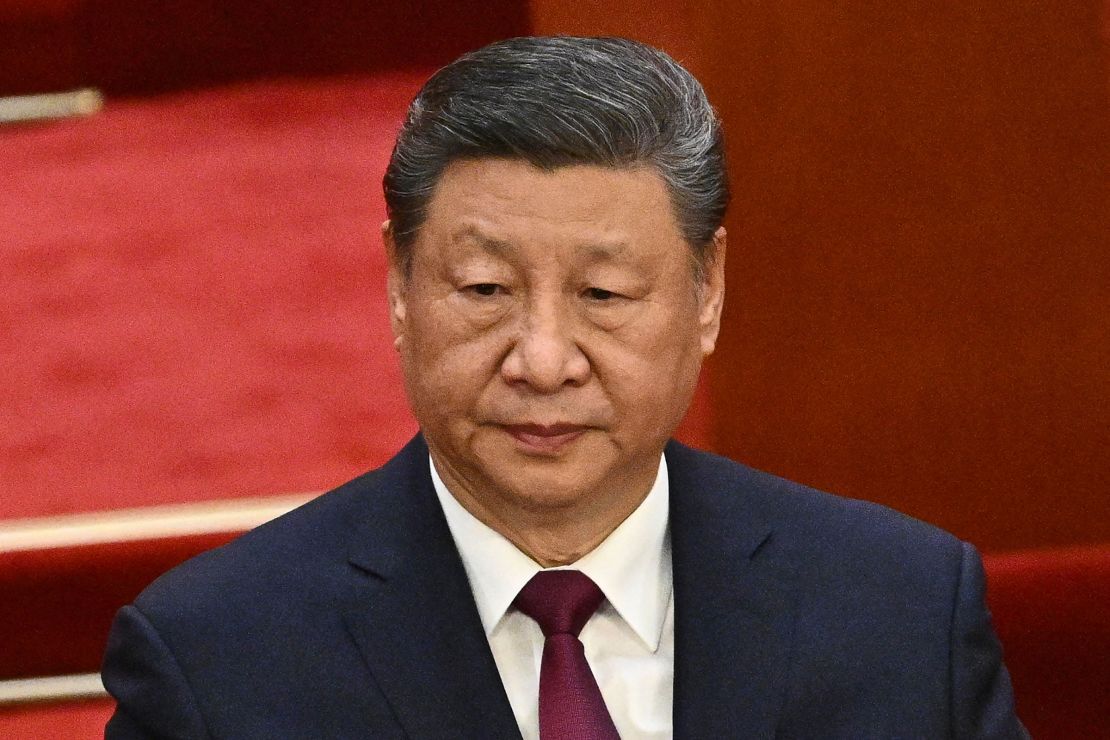
China’s home prices have now fallen for more than four and a half years — a household wealth shock comparable in scale to the 2008 U.S. crash, except still accelerating, according to Eurasia Group’s 2026 top-risks assessment. The consultancy ranked China’s deflation trap as its #7 global risk for the year, with a striking core argument: Beijing has the fiscal and monetary tools to break the cycle, but with the 21st Party Congress looming in 2027, Xi Jinping is prioritizing political control and technological supremacy over the consumption stimulus and structural reform that could actually fix it.
The Numbers Behind the Trap
Retail sales declined in May 2026 for the first time since December 2022, even as industrial output remained resilient — a sign that domestic demand weakness, not supply, is the core problem, according to The Economy’s reporting. Eurasia Group’s analysis is blunt about the mechanism: Beijing bet that high-tech manufacturing would fill the gap left by the property collapse, but state-driven investment has instead created overcapacity with too few buyers to absorb it — pushing China to keep “exporting its way out,” flooding global markets with cheap goods at other countries’ expense.
Beijing has responded, just cautiously. The government announced $51 billion in initial 2026 public spending to boost consumption and investment, including 295 billion yuan ($42 billion) front-loaded for national strategic initiatives, according to Bloomberg. Subsidies have been running since mid-2024 specifically to stabilize consumption battered by the housing slump and persistent deflation.
Where the Stimulus Is Working — Barely
The clearest evidence of partial success came during the Lunar New Year holiday: rail travel hit a record of over 18.7 million passengers in a single day, and CCB International Securities called the holiday spending data confirmation that recent stimulus is working, according to CNBC. Yet even that good news carried a deflationary asterisk: average spend per tourist trip fell 0.2% year-on-year, signaling that more people were traveling but spending less per trip.
February’s CPI print showed the strongest rebound since January 2023, up 1.3% year-on-year, beating forecasts, per separate CNBC coverage. But Beijing kept its annual inflation target at “around 2%” — the lowest in over two decades — treating it explicitly as a ceiling rather than a goal, while simultaneously lowering its 2026 GDP growth target to 4.5-5%, the least ambitious target on record since the early 1990s.
The Reform Beijing Isn’t Making
Asia Times argues the more consequential missed opportunity predates 2026: China’s over-the-top COVID lockdowns and Xi’s 2020 crackdown on internet giants — starting with Alibaba founder Jack Ma — set back consumer confidence for years and had Wall Street debating whether China was “uninvestable,” according to Asia Times’ analysis. The piece argues the genuine fix — ending the property crisis, strengthening capital markets, increasing transparency, making the yuan fully convertible — remains politically available but undeployed, with municipal leaders instead trapped chasing arbitrary annual GDP targets that “warp all economic incentives.”
For 2026, China is targeting roughly 5% GDP growth as the opening year of its 15th Five-Year Plan, according to reporting via MEXC, a target advisers reportedly want set explicitly to give the new plan a strong launch — political messaging as much as economic forecasting.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


China Economy
China’s Local Debt Race Against Time: Why Economists Demand Central Action Before the Deflation Window Closes
Key Policy Takeaways
- The Fiscal Dilemma: China’s local government hidden debt (off-balance-sheet LGFV liabilities) is estimated by the International Monetary Fund (IMF) to exceed 60 trillion yuan (~US$8.4 trillion).
- The Vanishing Window: Ultra-low benchmark interest rates and weak price indices offer Beijing an ideal window to swap high-cost, short-duration local liabilities for long-duration central sovereign bonds.
- The Risk of Delay: Waiting until inflation rebounds or global monetary policy tightens will significantly increase debt-servicing burdens and squeeze commercial bank margins.
- Structural Reform Needed: Refinancing alone is insufficient; Beijing must overhaul central-local tax distribution to prevent new hidden debts from accumulating.
1. The Perishable Window: Why Low Inflation Is a Double-Edged Sword
Prominent Chinese economic advisors are urging Beijing to capitalize on the country’s prevailing low-interest and soft-price environment to execute a comprehensive debt restructuring. According to research from the World Bank, China’s subdued consumer and producer price trends have created a rare, temporary period where sovereign issuance can be expanded with minimal immediate risk of runaway inflation or surging debt-servicing yields.
When price levels and market borrowing rates are low, the cost of issuing special central government bonds (Treasuries) is at historical troughs. By leveraging this environment, Beijing can absorb or refinance high-yield municipal obligations at fractions of their original servicing cost.
However, macroeconomists warn that this window is shrinking:
[Low Inflation & Low Yields] ──► [Lower Sovereign Issuance Costs] ──► [Ideal Debt Swap Window]
          │                                                                  │
          ▼ (If Delayed)                                                     ▼ (If Executed Now)
[Erosion of Local Revenues] ──► [Rising Default & Credit Risks]   ──► [Restored Fiscal Flexibility]
If Beijing delays central balance-sheet expansion, prolonged deflation risks further eroding local government tax revenues and land sales proceeds. Analysis from S&P Global Market Intelligence indicates that land sales revenues—historically accounting for up to 30% of municipal fiscal funds—have dropped significantly from their peak levels, leaving local authorities without the primary engine used to service off-balance-sheet vehicles.
2. The LGFV Mechanics: How Hidden Debt Stalls Regional Growth
The root of China’s fiscal challenge lies in Local Government Financing Vehicles (LGFVs)—special entities created by provinces and cities to finance public infrastructure without officially breaching central deficit caps.
The Anatomy of China’s Municipal Balance Sheet
- Official Municipal Debt: Directly tracked bonds subject to strict quota limits set by the National People’s Congress.
- Implicit / Hidden LGFV Debt: High-cost, off-balance-sheet bank loans, corporate bonds, and shadow banking products carrying implicit guarantees but yielding insufficient commercial returns.
As highlighted in a macroeconomic study by the Peterson Institute for International Economics (PIIE), when local debt-servicing costs outpace local economic growth, municipal governments are forced into fiscal austerity. This results in delayed civil service pay, cuts to public transit subsidies, and reduced local procurement—directly depressing domestic demand and compounding broader deflationary pressures.
3. The “Involution” Loop: Price Wars and Subsidized Capacity
A critical dynamic overlooked in conventional coverage is how local debt fuels industrial “involution” (内卷)—cutthroat, race-to-the-bottom price competition.
Faced with declining traditional tax revenues and mounting debt obligations, regional authorities frequently use local subsidies, cheap land allocation, and state-directed credit to prop up favored local manufacturing sectors (such as solar components, EV parts, and industrial chemicals).
┌────────────────────────────────────────────────────────────────────────┐
│                        THE INVOLUTION CYCLE                            │
├────────────────────────────────────────────────────────────────────────┤
│ 1. Local Debt Pressure  ──► Municipalities seek fast industrial GDP    │
│ 2. Target Subsidies     ──► Directed capital into local manufacturing  │
│ 3. Industrial Overcap   ──► Manufacturers overproduce to maintain scale  │
│ 4. Price Wars (CPI/PPI) ──► Deflationary pressure squeezes margins     │
│ 5. Lower Tax Revenues   ──► Debt burden expands relative to revenue    │
└────────────────────────────────────────────────────────────────────────┘
According to sector reporting from Rhodium Group, this localized credit allocation keeps unproductive firms afloat, floods domestic markets with overcapacity, and drives price deflation across industrial outputs. To break this loop, economists argue that Beijing must restrict local industrial subsidies while substituting them with direct central transfers to households.
4. Policy Roadmap: How Beijing Can Safely De-Risk Local Liabilities
To outperform past partial debt swaps, top financial experts recommend a coordinated four-point execution plan:
| Strategic Pillar | Action Item | Target Economic Outcome |
| 1. Central Balance Sheet Expansion | Issue Ultra-Long Special Sovereign Bonds to swap LGFV debt into central debt. | Reduces aggregate interest payments by hundreds of billions of yuan annually. |
| 2. Commercial Bank Shielding | Structure interest rate cuts alongside targeted PBoC liquidity injections. | Protects bank Net Interest Margins (NIMs) from lower bond yields. |
| 3. Tax Revenue Sharing Reform | Rebalance the 1994 tax-sharing system to allocate a higher tax share to local authorities. | Permanently aligns municipal spending obligations with recurring revenue. |
| 4. Consumption-Focused Stimulus | Shift state expenditures from physical infrastructure to social security, healthcare, and income support. | Unlocks household savings and drives organic demand-led reflation. |
Reports from the Organisation for Economic Co-operation and Development (OECD) emphasize that structural fiscal reform—specifically updating the distribution of revenues between Beijing and provincial capitals—is necessary to prevent local governments from simply building new hidden debt after the current swap is completed.
5. Global Implications for Investors and Markets
For international markets, China’s decision to act decisively on local debt carries substantial weight:
- Commodity & Global Demand: Restructuring local debt allows municipalities to resume core public works and social spending, stabilizing demand for global industrial metals and capital equipment, as monitored by the Asian Development Bank.
- Currency and Yield Dynamics: As noted by analysis in the Financial Times and market coverage in Bloomberg News, a central government debt swap reduces tail-risk in China’s financial sector, offering long-term stability for the Renminbi (RMB) even as benchmark rates remain low.
- Banking Sector Relief: Replacing non-performing or low-yielding LGFV loans with sovereign-backed paper lowers credit risk weights for state banks, preserving regulatory capital buffers across the broader financial system.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Global Economy
Beyond Rhetoric: How the EU Is Deploying ‘All Tools’ to Rebalance Its €1 Billion-a-Day Trade Deficit with China
Key Takeaways
- The Tipping Point: European Commission President Ursula von der Leyen has declared that Europe’s trade deficit with China has reached an “unsustainable” €1 billion per day, pushing bilateral trade relations to a historical tipping point.
- Enforcement Over Engagement: Signaling a fundamental shift in doctrine, von der Leyen issued a direct ultimatum: “Words are good. But deeds are better.”
- The Defensive Arsenal: Brussels is escalating beyond traditional anti-dumping tariffs, actively deploying the Foreign Subsidies Regulation (FSR), the International Procurement Instrument (IPI), and establishing a centralized European Critical Raw Materials Corporation under the RESourceEU framework.
- Supply Chain Exposure: European and Asian enterprises face heightened compliance scrutiny, potential market access restrictions, and supply chain realignment risks across green-tech, automotive, and critical mineral sectors.
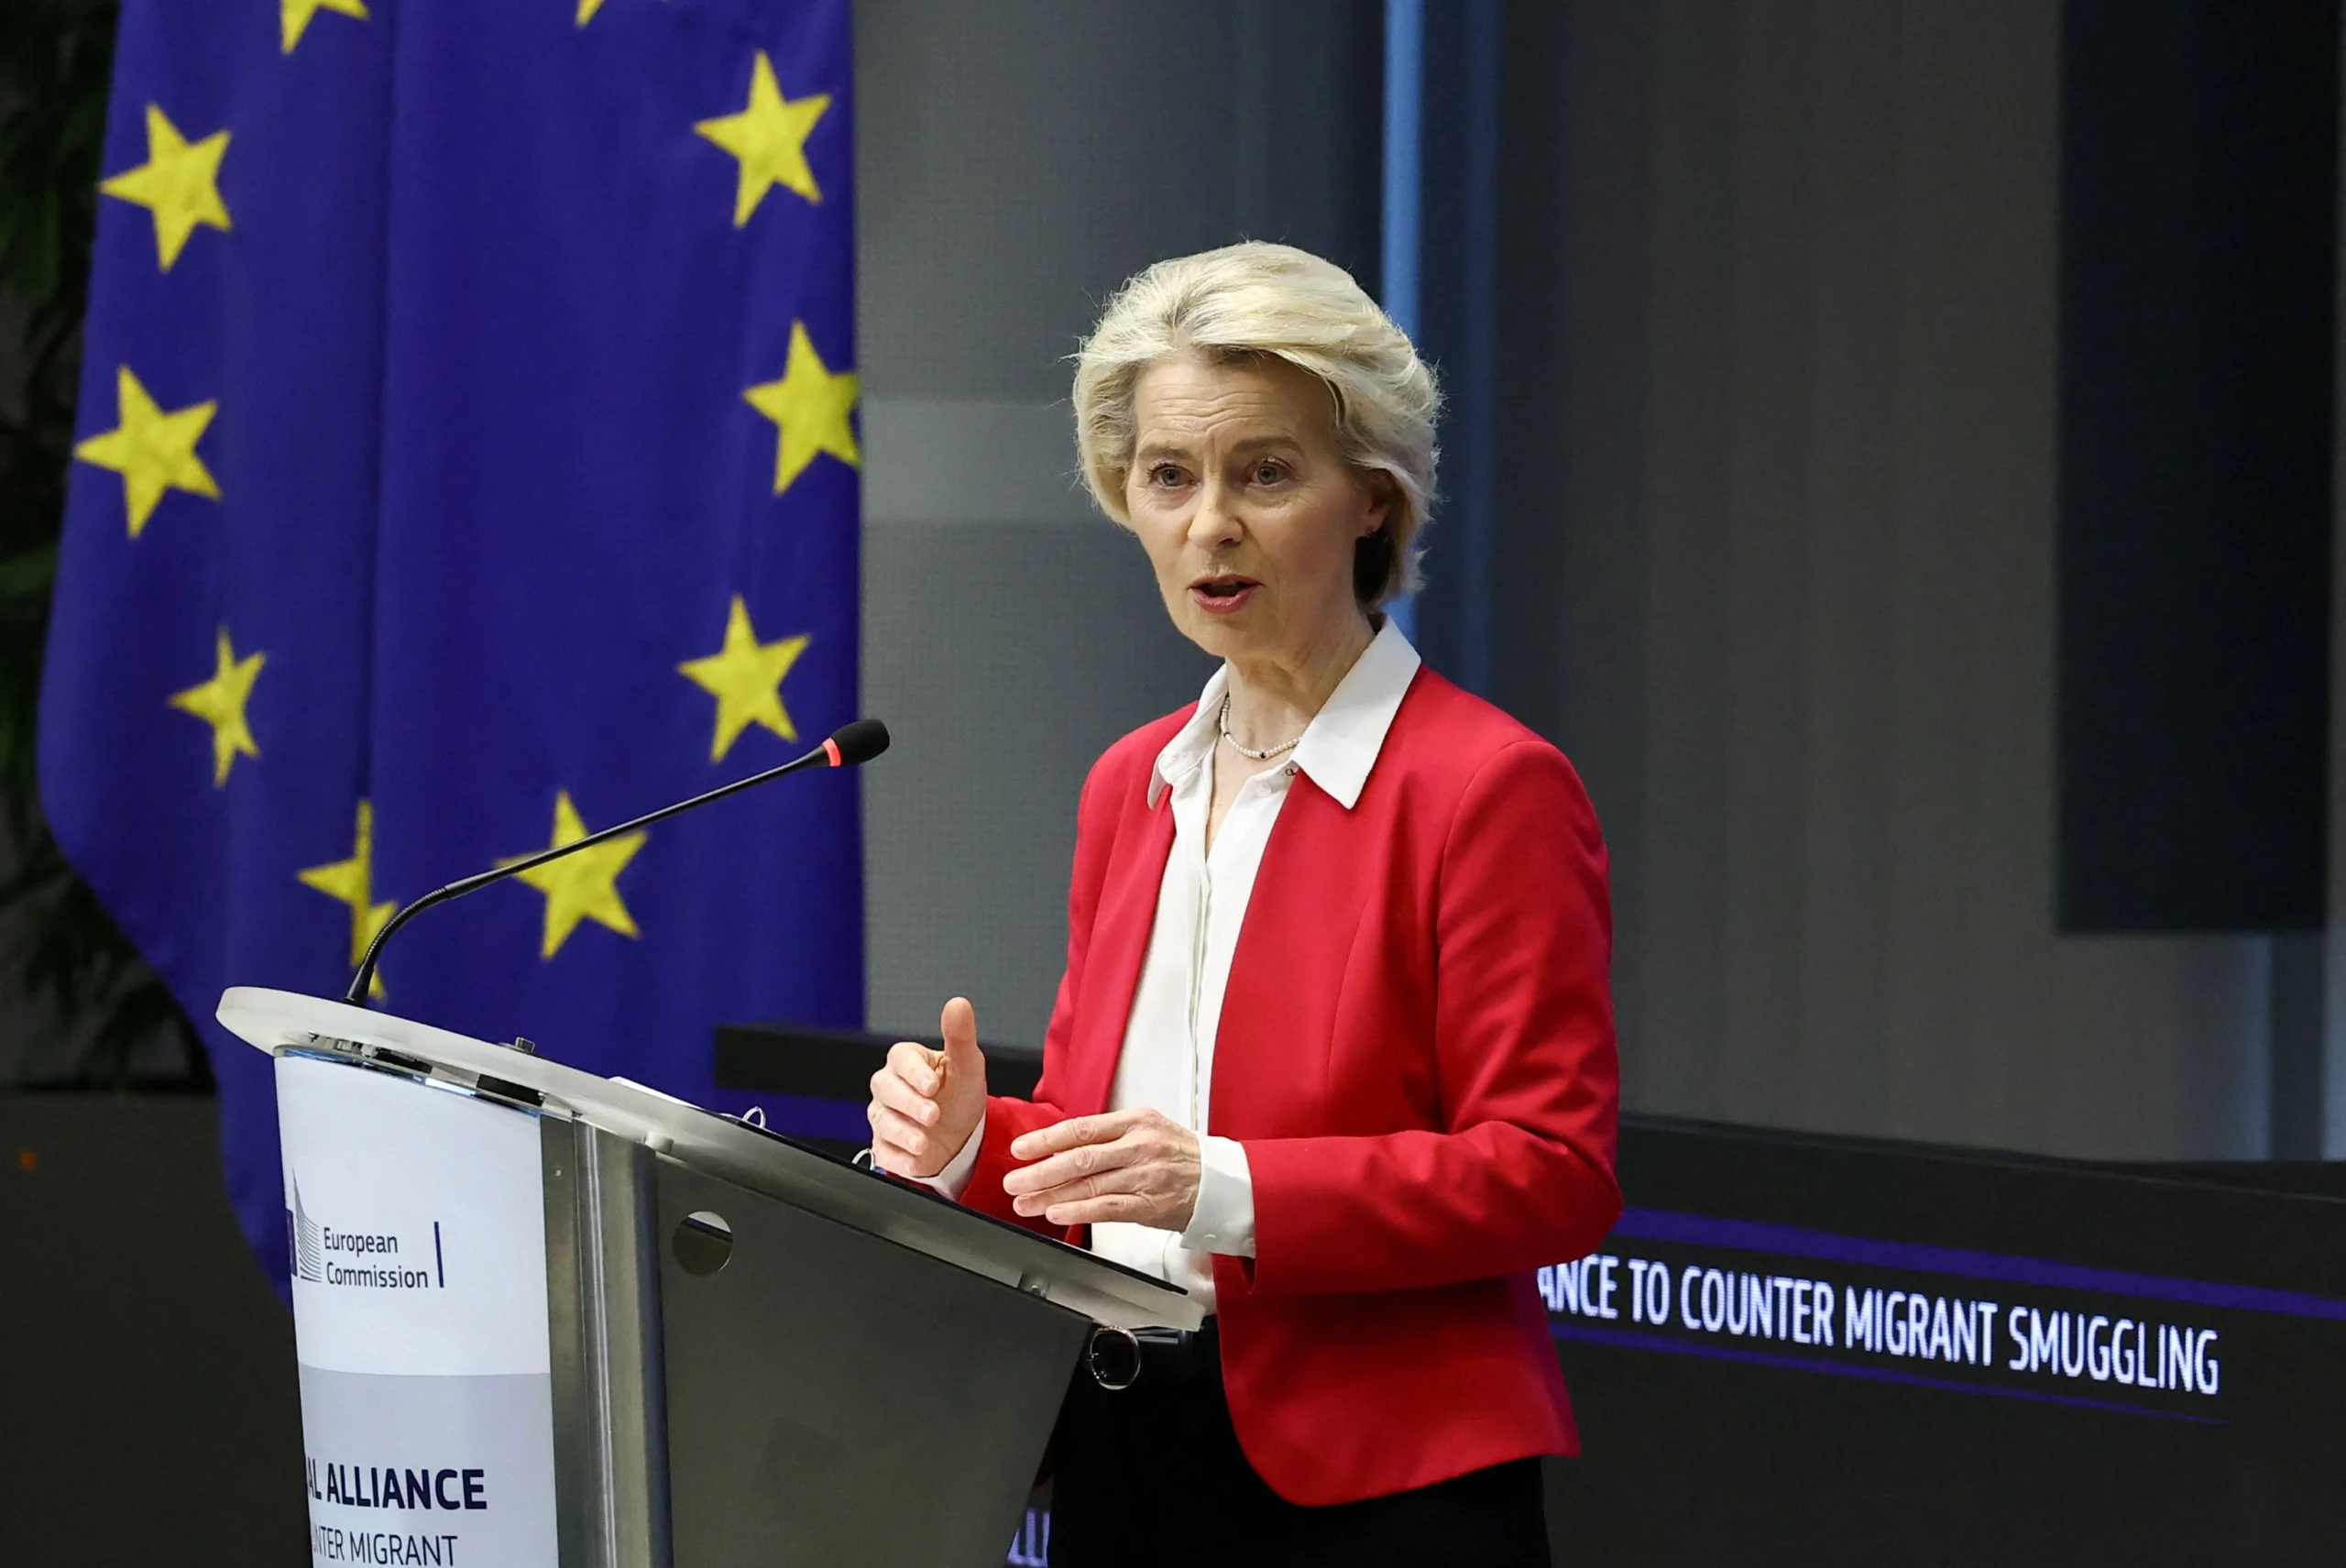
Commission President von der Leyen outlining EU trade policy in Brussels. Source: Yves Herman / REUTERS
The €1 Billion-a-Day Dilemma: Inside Brussels’ Trade Ultimatum
In her 2026 State of the Union address, European Commission President Ursula von der Leyen delivered her sternest warning to date regarding economic relations with Beijing. Citing structural industrial overcapacity in China and subsidized export dumping into the Single Market, von der Leyen emphasized that Europe’s trade deficit with China—now running at approximately €1 billion every single day—has crossed a critical threshold.
While reaffirming that diplomatic dialogue remains open, von der Leyen signaled that Brussels’ patience with protracted negotiations has expired:
“Words are good. But deeds are better. If market imbalances persist and level-playing-field conditions are not restored, the European Union will use all tools at its disposal to rebalance trade.” — Ursula von der Leyen, President of the European Commission
According to official data released alongside the address by the European Union External Action Service, the EU’s merchandise trade deficit with China has expanded sharply over the past decade. The expansion is driven by state-directed investments in clean technology, advanced industrial machinery, and automotive manufacturing, combined with persistent market barriers facing European exporters in mainland China.
Deconstruction of the EU’s Trade-Defence Arsenal
To move beyond political warnings, the European Commission is mobilizing a multi-layered regulatory architecture designed to shield European industries from non-market practices.
| Trade Defence Instrument | Legal Basis & Focus | Operational Impact on Chinese Exports |
|---|---|---|
| Foreign Subsidies Regulation (FSR) | EU Regulation 2022/2560 | Allows Brussels to inspect and block foreign state-subsidized companies from bidding on EU public tenders or acquiring European firms. |
| International Procurement Instrument (IPI) | EU Regulation 2022/1031 | Restricts access to EU public procurement markets for companies from countries that discriminate against EU businesses. |
| Anti-Subsidy & Anti-Dumping Duties | EU Regulation 2016/1037 | Enables retroactive tariffs on subsidized goods (e.g., Electric Vehicles, solar modules, wind turbines). |
| Critical Raw Materials Corporation (RESourceEU) | 2026 Industrial Strategy | Co-finances joint purchasing, strategic stockpiling, and processing of rare earth elements to reduce single-source dependency. |
As highlighted by macroeconomic analysis from Reuters Global Economic News, the Commission’s strategy represents a transition from reactive tariff enforcement to proactive market access restriction.
EU and China trade relations face growing regulatory and tariff barriers. Source: Bloomberg / Bloomberg via Getty Images
De-Risking in Action: Critical Minerals & the RESourceEU Imperative
A core pillar of von der Leyen’s strategic agenda is severing Europe’s vulnerable supply chain dependencies. China currently controls over 70% of global lithium refining, 85% of rare earth processing, and a dominant share of permanent magnet manufacturing.
To counter this vulnerability, von der Leyen confirmed the formal launch of the European Critical Raw Materials Corporation under the broader RESourceEU initiative. This entity will serve as a centralized buyer and investor, co-funding strategic mining, processing, and recycling projects within the EU, North America, and partner nations across Africa and Latin America.
Key objectives of the mineral security framework include:
- Extraction Mandates: At least 10% of the EU’s strategic raw materials extracted domestically by 2030.
- Processing Sovereignty: At least 40% of the EU’s annual consumption of strategic raw materials processed within the bloc.
- Diversification Caps: No more than 65% of any strategic raw material sourced from a single third country.
Economic reporting by the Financial Times Trade Analysis notes that these targets represent one of the most aggressive state-supported supply chain realignment efforts in modern European history.
Geopolitical Fallout & Beijing’s Countermeasures
Beijing’s Ministry of Commerce (MOFCOM) has expressed strong opposition to Brussels’ hardening stance, warning that increased trade barriers risk destabilizing global recovery and violating World Trade Organization (WTO) principles.
In response to European investigations under the FSR and anti-subsidy rules, China has initiated targeted anti-dumping probes into European exports, including brandy, dairy products, and agricultural machinery. Analysts anticipate that further unilateral measures by Brussels could prompt reciprocal restrictions on European automotive and chemical majors operating in mainland China.
+-----------------------------------------------------------------------+
|                 EU-CHINA TRADE TENSION CASCADE MATRIX                  |
+-----------------------------------------------------------------------+
| 1. EU Measures: FSR Inspections, Tariff Escalation, Raw Material Caps |
|    │                                                                  |
|    ▼                                                                  |
| 2. Chinese Countermeasures: Target Agribusiness, Spirits, Luxury Goods|
|    │                                                                  |
|    ▼                                                                  |
| 3. Corporate Impact: Supply Chain Realignment, Dual-Hub Production    |
+-----------------------------------------------------------------------+
Strategic Playbook for Global Business Leaders
For corporate executive teams and supply chain planners navigating this evolving landscape, the European Union Trade Policy Framework recommends three strategic adjustments:
- Audit State Subsidy Exposure: European subsidiaries of non-EU firms must conduct thorough audits of parent company subsidies, tax credits, and state grants to avoid disqualification under FSR procurement reviews.
- Diversify Critical Mineral Sourcing: Manufacturers reliant on graphite, neodymium, lithium, or cobalt should secure secondary supply contracts outside China ahead of 2027 compliance deadlines.
- Adopt “China + 1” Regionalization: Multinationals serving both European and Asian markets should decouple supply chains into distinct regional hubs to insulate operations from tariff hikes and export controls.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Key Takeaways
- Mainland Chinese indices slid to multi-week lows in mid-September 2026, with the Shanghai Composite at 3,888 (a two-week low) and the Shenzhen Component at 13,471 (an over one-month low), pressured by rising oil prices and higher US Treasury yields.
- Hong Kong’s Hang Seng Index has been choppier still, falling as low as 24,954 in early September amid Middle East-driven risk-off sentiment, before stabilizing near 25,300.
- Beijing has responded with roughly RMB 360 billion (~$54 billion) in fresh capital injections into major state-owned banks and insurers — a policy-driven floor that stands in contrast to more cautious international investor sentiment.
- China’s semiconductor and AI sector continues attracting capital despite the broader selloff — Shanghai chipmaker Enflame Technology recently raised roughly $908 million in a heavily oversubscribed IPO.
- The IMF’s July 2026 outlook raised China’s 2026 growth forecast to 4.6%, even as the broader stock market today narrative remains one of policy support offsetting external headwinds rather than a clean, confirmed bottom.
Chinese equities have spent much of September 2026 grinding lower, caught between two competing forces: a genuinely supportive domestic policy stance from Beijing, and an external environment darkened by surging oil prices and rising US bond yields. For investors asking whether Chinese and Hong Kong-listed stocks are approaching a durable bottom, the honest picture is mixed — supportive at the policy level, but not yet confirmed at the price level.
The Current Selloff, By the Numbers
As of the second week of September 2026, the Shanghai Composite closed at 3,888.1, a two-week low, down 1.18% on the day and roughly 1.48% over the trailing month. The Shenzhen Component fared worse, dropping 1.08% to an over one-month low of 13,471.3. The proximate causes were external rather than domestic: rising oil prices — driven by the escalating US-Iran conflict — combined with a jump in US Treasury yields after a weaker-than-expected US Treasury buyback operation, weighed on risk appetite across Asian markets broadly.
Notable laggards during the slide included Zijin Mining Group (-5.42%), CMOC Group (-4.52%), CATL (-2.23%), and East Money Information (-3.48%) — a mix of commodity and financial-services names sensitive to both global rate expectations and China’s own growth trajectory.
Hong Kong has told a similarly volatile story. The Hang Seng Index fell to as low as 24,954 in early September as Middle East tensions and surging oil prices weighed on sentiment, before partially recovering to trade around 25,300–25,650 in subsequent sessions. Tech names bore the brunt of the volatility: Chinese AI startups Z.AI Co. and MiniMax posted sharp single-day declines of over 3% and 7% respectively during the worst sessions, while over the trailing month, JD Logistics and Kuaishou each fell roughly 26%.
Beijing’s Policy Floor
What differentiates this selloff from prior Chinese market corrections is the scale and speed of policy support. Chinese authorities have unveiled roughly RMB 360 billion (approximately $54 billion) in capital injections into major state-owned banks and insurers — a move analysts say is partly intended to strengthen institutions Beijing increasingly wants positioned as long-term equity investors. Estimates suggest the measures could support around RMB 100 billion of additional insurer equity exposure to domestic markets, effectively building a policy-driven demand floor beneath the broader index.
This “national team” style intervention has a track record in China of stabilizing markets during external shocks, even if it hasn’t historically produced immediate V-shaped recoveries. The key question for investors is whether this round of support proves sufficient to offset the current combination of high oil prices, elevated global bond yields, and lingering uncertainty around US-China trade dynamics.
The Technology Counter-Narrative
Even amid the broader selloff, China’s technology and semiconductor sector has continued attracting significant capital — a sign that investor conviction in China’s AI self-reliance push remains intact regardless of the macro backdrop. Shanghai-based AI chipmaker Enflame Technology raised approximately $908 million in a heavily oversubscribed IPO, underscoring investor appetite for domestic alternatives to Nvidia as Beijing continues pushing technological self-reliance amid ongoing US export restrictions. During a brief rebound period earlier in September, communications shares rose 6.2% and electronics gained 3.9% in a single session, even as coal and non-bank financial stocks fell.
Index Snapshot: Where Things Stand
| Index | Recent Level | Recent Trend |
|---|---|---|
| Shanghai Composite | ~3,888 | Two-week low, -1.48% trailing month |
| Shenzhen Component | ~13,471 | Over one-month low, -0.34% weekly |
| CSI 300 | ~4,575–4,578 | Broadly flat to slightly down |
| Hang Seng Index | ~25,300 (range 24,954–25,650) | Volatile, Middle East-driven swings |
| Hang Seng TECH | ~4,527 | -2.0% over one week during worst sessions |
Why This Matters: Policy Support vs. External Shock
The IMF’s July 2026 World Economic Outlook update raised China’s 2026 growth forecast to 4.6%, a relatively resilient number within a global backdrop the Fund otherwise describes as uneven — energy importers under pressure, technology-value-chain economies benefiting from the AI investment cycle. China occupies an unusual middle position: an energy importer exposed to the same oil-price shock hitting other Asian markets, but also a major beneficiary of the AI capital-expenditure supercycle through its domestic chip and data-center buildout.
For investors trying to time a bottom, the more instructive signal may not be the index level itself but the divergence between policy-driven sectors (banks, insurers, state-directed capital) and sentiment-driven sectors (consumer platforms, logistics, export-exposed names). The former has stabilized meaningfully on Beijing’s RMB 360 billion intervention; the latter remains hostage to the same global risk-off dynamics pressuring markets from Tokyo to Riyadh.
Frequently Asked Questions
Have Chinese stocks bottomed out in September 2026?
Not conclusively. Beijing’s roughly $54 billion capital injection into banks and insurers has provided policy support, but the broader index remains pressured by external factors — elevated oil prices and rising US Treasury yields — that are outside domestic policymakers’ control.
Why are Chinese tech and semiconductor stocks still attracting investment despite the selloff?
Investor appetite for Chinese AI self-reliance remains strong, evidenced by chipmaker Enflame Technology’s roughly $908 million oversubscribed IPO, even as broader indices like the Shanghai Composite and Hang Seng have declined.
What is the IMF’s 2026 growth forecast for China?
The IMF’s July 2026 World Economic Outlook update raised China’s 2026 growth forecast to 4.6%, reflecting relative resilience within a global economy otherwise strained by the Middle East conflict’s impact on energy-importing nations.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Beyond Paper Wealth: Unpacking Donald Trump’s Multibillion-Dollar Liquidity and Legal Crisis

Bitcoin & XRP 2026: Inside Crypto’s Institutional Era

Global Economy 2026: IMF Growth, AI Stocks & Market Risk

China’s Local Debt Race Against Time: Why Economists Demand Central Action Before the Deflation Window Closes

Money News: How to Protect Your Portfolio From Global Inflation

World Bank Projections: Emerging vs. Big Economies of Asia

IMF Reports 2026: What the Latest Data Means for the Global Economy

Singapore Stocks Outlook: A Safe Haven in the Asian Market?

China Stocks vs. Japan Stocks: Where Should You Invest in Late 2026?

VIX Index Explained: How to Trade Wall Street’s Fear Gauge Today

Commercial vs Residential Real Estate: Which Wins in 2026?

Presidential Stock Market Performance: How Trump’s Second Term Compares to History

2026 Real Estate Market News: Are We Heading for a Correction?

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025