
Analysis
‘Clear Leader’ in Southeast Asia: Analysts Overwhelmingly Bullish on Grab

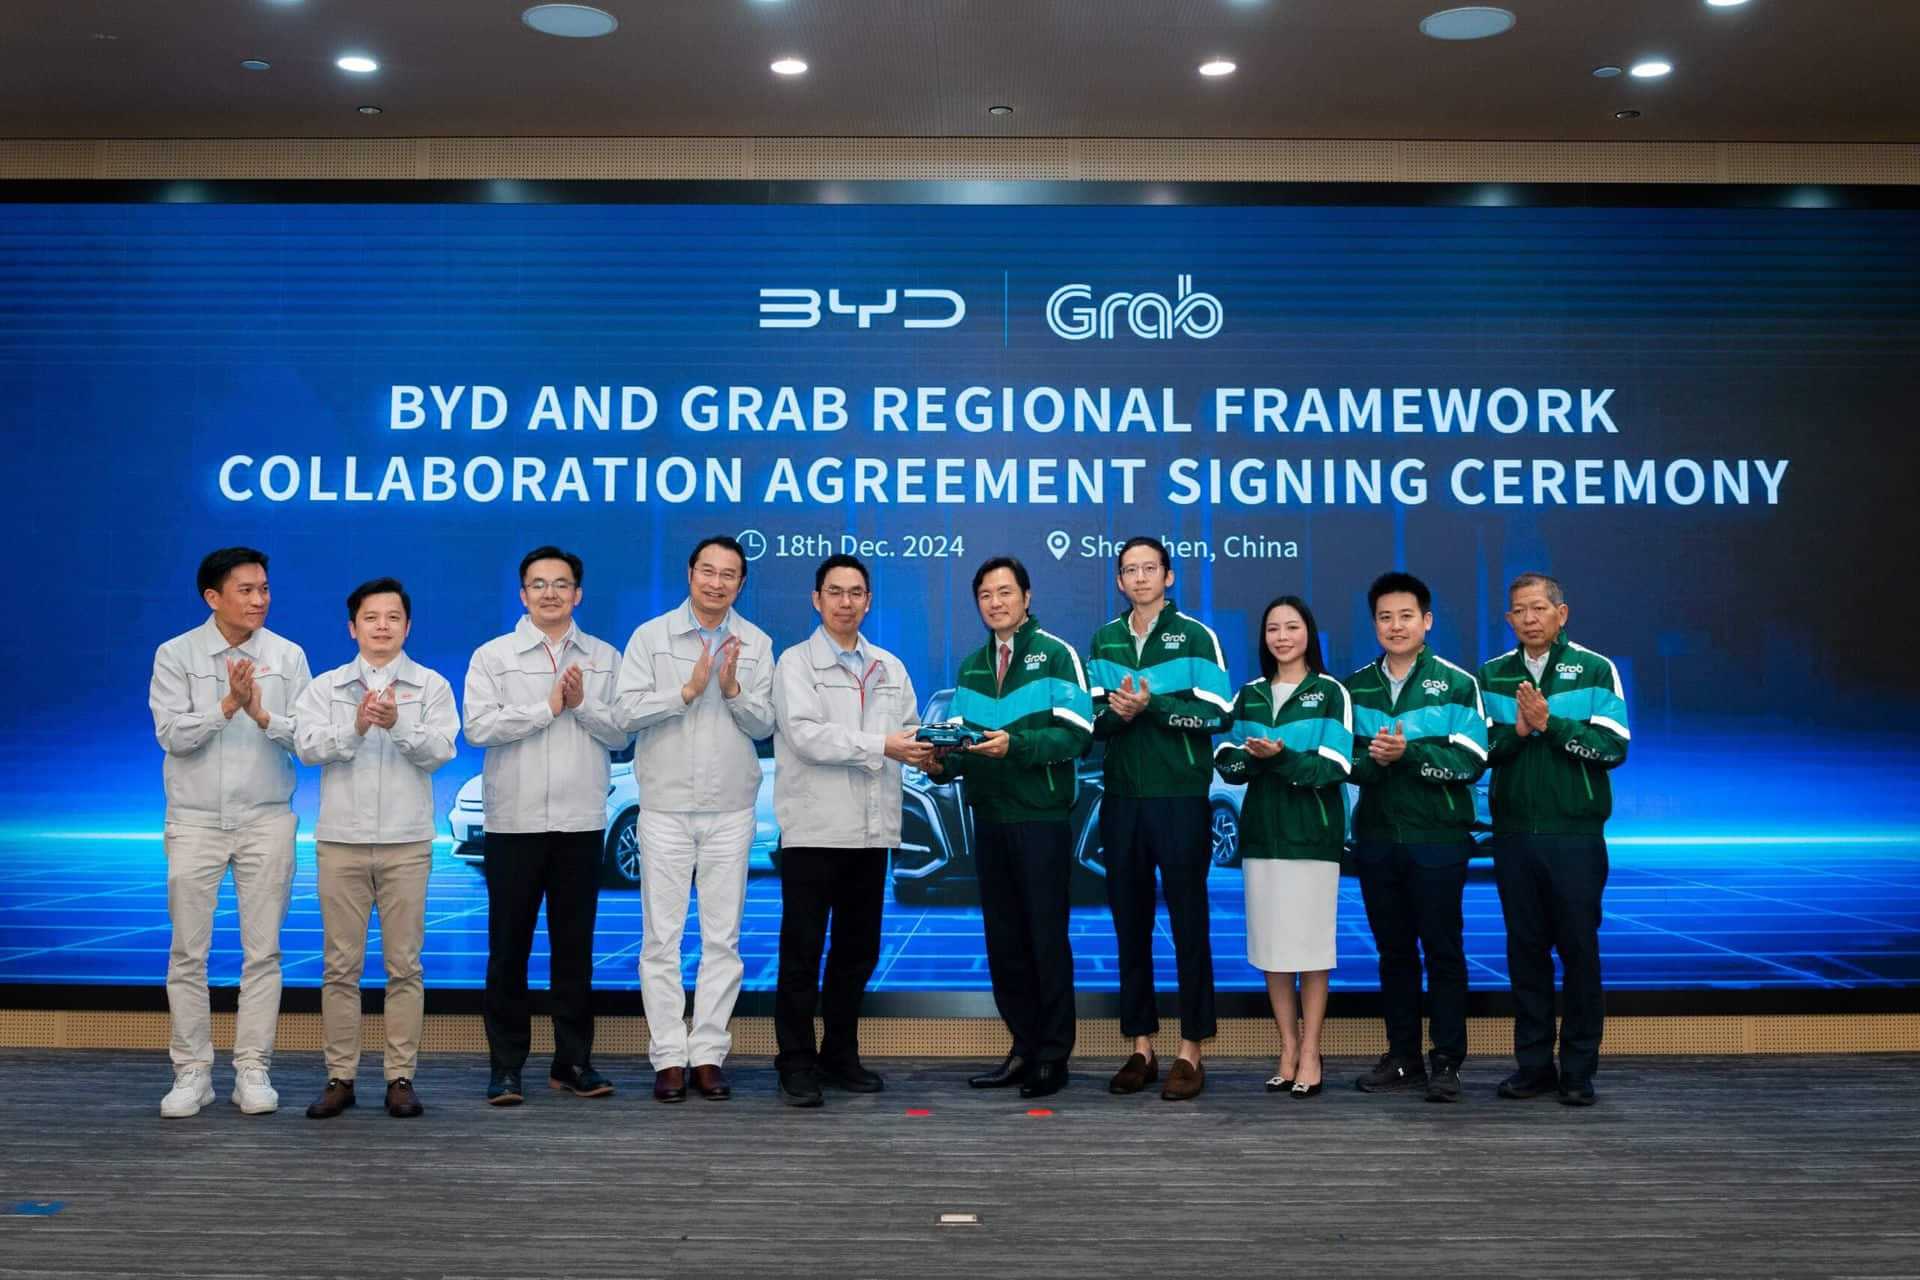
Grab Holdings (NASDAQ: GRAB) delivered its strongest-ever first quarter on May 5, 2026 — yet the stock still trades near a 52-week low. That disconnect, analysts say, is precisely the opportunity.
There is a particular kind of market moment that veteran investors learn to recognize: a fundamentally strong business, beset by a sudden regulatory headline, trading at a price that reflects panic rather than analysis. Grab Holdings finds itself squarely in that position today.
On May 5, the Singapore-headquartered super-app posted first-quarter 2026 revenues of $955 million — up 24% year-over-year and comfortably ahead of the $914 million analysts had pencilled in. Adjusted EBITDA surged 46% to a record $154 million, marking the company’s 17th consecutive quarter of adjusted EBITDA growth. Profit for the period reached $120 million, versus a mere $10 million a year earlier — a twelvefold improvement. Monthly transacting users climbed 16% to 51.6 million, while on-demand gross merchandise value hit $6.1 billion, accelerating into what is traditionally the company’s softest seasonal quarter.
By nearly every operational metric, Grab is performing like a company that has permanently turned the corner. Yet the shares were trading at roughly $3.87 as of this writing — close to a 52-week low of $3.48, and some 40% below the analyst consensus price target of approximately $6.28 to $6.56. That gap, implying upside of 65% to 70% or more, has become one of the more striking mispricings in emerging-market technology.
The explanation lies in a single regulatory bombshell from Jakarta — and why Grab’s management, and an overwhelming majority of Wall Street analysts, believe the market has dramatically overstated its impact.
Q1 2026: A Profit Machine Firing on All Cylinders
Grab’s Q1 2026 results did not merely beat expectations. They illustrated a business model that is simultaneously deepening its moat and broadening its margin profile across three interdependent pillars: mobility, deliveries, and financial services.
Mobility — Grab’s original ride-hailing engine — remains the crown jewel of the group’s P&L. Revenue rose 19% year-over-year to $337 million, with segment adjusted EBITDA climbing 24% to $198 million, affirming the group’s dominant position in the regional ride-hailing market. Strong GMV expansion was underpinned by continued growth in mobility monthly transacting users and the early dividends of AI-driven marketplace efficiencies, including the company’s “Turbo” driving mode, which management says has already increased driver earnings by 23% — a metric that is as much about driver retention and supply-side resilience as it is about technology.
Deliveries contributed revenue of $510 million, up 23% year-over-year, driven by GMV expansion and an increasingly profitable advertising business layered atop its food delivery platform. Of particular note: GrabMart, the group’s grocery delivery vertical, now accounts for 10% of deliveries GMV and is growing at 1.7 times the rate of food delivery. Grocery users order with 1.8 times the frequency of food-only users — a powerful indication of the stickiness and upward value migration that the super-app model enables.
Financial Services was the quarter’s standout growth story. Revenue jumped 43% year-over-year to $107 million, propelled by a gross loan portfolio that more than doubled to $1.44 billion — with management reiterating a target of $2 billion by year-end. Loan disbursals surged 67% to exceed $1 billion in the quarter. The segment continues to operate at a loss — adjusted EBITDA of negative $17 million — but that loss narrowed sharply from negative $30 million a year earlier, and the company has firmly reiterated its target of fintech segment adjusted EBITDA breakeven in the second half of 2026.
The balance sheet, meanwhile, provides formidable strategic optionality. Grab ended the quarter with $6.9 billion in gross cash liquidity and $5.0 billion in net cash liquidity — a war chest that underpins its recently launched $400 million accelerated share repurchase program, part of a previously approved $500 million buyback mandate. “This is a reflection of our conviction in Grab’s long-term value at these dislocated prices,” CEO Anthony Tan told investors. It is difficult to argue with his framing.
Full-year 2026 guidance was reaffirmed at revenue of $4.04 billion to $4.10 billion (implying 20–22% growth) and adjusted EBITDA of $700 million to $720 million (implying 40–44% growth). Trailing twelve-month adjusted free cash flow reached $489 million — a metric that underscores the underlying quality of the business in ways that standard EBITDA reporting often obscures.
The Analyst Consensus: Overwhelmingly Bullish, Carefully Differentiated
The analytical community’s view on Grab is about as unified as it gets in a stock where regulatory uncertainty warrants genuine debate. 26 of 27 Wall Street analysts currently rate the stock a Buy, with a consensus price target of approximately $6.28 to $6.56, implying upside of 65% to nearly 70% from current levels.
The range of price targets, however, reflects divergent views on the severity and duration of the Indonesia commission cap headwind:
| Firm | Rating | Price Target |
|---|---|---|
| Evercore ISI (Mark Mahaney) | Buy | $8.00 |
| Barclays | Outperform/Buy | $7.00 |
| Jefferies | Buy | $6.70 |
| Morgan Stanley | Overweight | $6.40 |
| HSBC | Buy | $6.20 |
| BofA Securities | Buy | $6.20 |
| Mizuho | Outperform | $6.00 (lowered) |
| JPMorgan | Overweight | $5.90 (lowered) |
| Barclays (conservative) | Buy | $4.50 |
The spread between the most optimistic and most conservative targets — $8.00 to $4.50 — reflects less a disagreement about Grab’s fundamental trajectory and more a calibration exercise around Indonesia’s regulatory timeline, the macroeconomic oil price environment, and the pace of the fintech segment’s path to profitability.
InvestingPro’s screening flags a PEG ratio of just 0.18 for Grab — strikingly low for a company growing revenue at 20%+ and EBITDA at 40%+. Moody’s, for its part, recently upgraded Grab’s corporate family rating to Ba2 with a stable outlook, citing continued earnings growth and its leading Southeast Asian market position. The credit analysts, it appears, are ahead of the equity market.
Regulatory Headwinds: The Indonesia Commission Cap, Unpacked
The regulatory development that rattled markets — and shaved tens of millions off Grab’s market capitalization in late April — deserves careful examination, because the initial reaction almost certainly overstated the structural risk.
On May 1, Indonesian President Prabowo announced a regulation capping ride-hailing platform commissions for two-wheel motorcycle-taxi (ojol) drivers at 8%, down from the current range of 15–20%. The announcement was a genuine surprise — Grab had specifically stated during its February 2026 Q4 earnings call that no commission cap changes were being proposed. The regulation also mandates expanded social protections and insurance for gig workers across deliveries and ride-hailing, which Grab had partly anticipated through a Rp100 billion driver welfare program announced in January 2026.
The headline risk is real: Indonesia represents approximately 17–19% of Grab’s Mobility GMV and roughly 20% of consolidated adjusted EBITDA, making it a material market. However, the actual scope of the cap has been significantly narrower than initial reports suggested.
During the Q1 earnings call, COO Alex Hungate delivered the crucial clarification: the 8% cap applies specifically to ojol two-wheel drivers, and that segment represents less than 6% of Grab’s total Mobility GMV. Four-wheel vehicle drivers, who earn substantially above Indonesia’s minimum wage, are not subject to the regulation in the same way. “We are therefore reiterating our expectations for Mobility margins to stabilize within the historical range,” Hungate said.
Grab’s mitigation levers are meaningful: fare adjustments, renegotiated incentive structures, and a cooperative posture with regulators aimed at “shaping a balanced implementation” of the decree. The fuel crisis sweeping Southeast Asia — which prompted Grab to temporarily raise its Singapore fuel surcharge from S$0.50 to S$0.90 per trip — is also providing cover for consumer-facing pricing adjustments that partially offset commission compression.
The broader regulatory question for Grab is structural, not episodic: Southeast Asian governments are increasingly treating digital platform operators as quasi-utilities, scrutinizing commission structures, data practices, and competitive behavior. That is a headwind Grab must manage continuously — but it is also a headwind that, given Grab’s embedded position in daily consumer life, is unlikely to prove fatal.
Competitive Moat: Why Grab Remains the Clear Regional Leader
The case for Grab’s competitive durability rests on a simple but powerful set of facts: no other regional operator comes close to matching its geographic breadth, ecosystem depth, or the compounding flywheel of its super-app model.
Grab operates across eight countries in Southeast Asia, a region of 680 million people with a rapidly expanding middle class, deepening smartphone penetration, and chronic underbanking. Its closest regional rival, GoTo (Gojek/Tokopedia), is overwhelmingly concentrated in Indonesia — a massive market, to be sure, but a geographically constrained competitive position that limits GoTo’s total addressable market.
The market share data tells a compelling story:
- Ride-hailing across Southeast Asia: Grab commands approximately 70% market share regionally, compared to GoTo’s Indonesia-focused position.
- Indonesia specifically (by order volume): Grab holds 63% of ride-hailing to GoTo/Gojek’s 36%, a data point that significantly complicates the narrative of GoTo as a serious regional threat.
- Southeast Asia food delivery: Grab leads with approximately 55% market share (equating to roughly $9.4 billion in GMV), while Foodpanda holds 15.8% and Gojek just 10.5%. ShopeeFood (Sea Group) and Thailand’s LINEMAN have shown growth at 8.8% and 8.1% respectively, but remain sub-scale at the regional level.
GoTo’s first-ever positive net income, achieved in late 2025, is a genuine competitive development — and a sign that the regional digital economy is maturing. But structural concentration of operations in Indonesia, the absence of a meaningful regional payments or lending network comparable to Grab’s, and limited corporate M&A firepower relative to Grab’s $5 billion net cash pile leave GoTo structurally disadvantaged as a pan-regional challenger.
Foodpanda, owned by Germany’s Delivery Hero, has been losing market share steadily; Grab’s acquisition of Foodpanda’s Taiwan operations for $600 million — secured at a roughly 30% discount to the price Uber was said to have considered — marks Grab’s first geographic expansion beyond Southeast Asia. Jefferies analysts view the deal as enabling Grab to “replicate its Southeast Asian delivery success in Taiwan, driven by affordability, reliability, and technology.” The EBITDA contribution is not expected before 2028, but the strategic logic — entering a high-density, digitally sophisticated market at distressed-asset pricing — is characteristic of Grab’s disciplined capital deployment.
SeaMoney (Sea Group’s fintech arm) and GoPay (GoTo’s digital payments unit) are legitimate fintech competitors, particularly in Indonesia and Vietnam. But neither offers the three-way flywheel — ride, eat, pay — at Grab’s regional scale. Network effects compound asymmetrically: the more users Grab adds to GrabPay, the more attractive its merchant offers become; the more merchants join, the more reason users have to keep the app active; the more active users there are, the richer the data set for credit decisioning in GrabFin. That is a virtuous cycle that took Grab thirteen years to build, and it cannot be acquired or replicated in a single funding round.
Growth Drivers: Fintech, AI, and the Path to 2028
The medium-term investment thesis for Grab rests on three compounding growth drivers that are still in relatively early stages.
Financial Services: The Margin Frontier. GrabFin’s gross loan portfolio doubling to $1.44 billion in a single year — with a $2 billion year-end target and disbursals exceeding $1 billion in Q1 alone — reflects the under-penetration of formal credit across Southeast Asia. An estimated 70% of adults in the region remain underbanked or entirely unbanked. Grab’s GX Bank (Malaysia) and GXS Bank (Singapore) are accumulating deposits and lending infrastructure at speed; combined deposits stood at $1.6 billion at quarter-end. When fintech reaches adjusted EBITDA breakeven in H2 2026, it will transition from a drag on group margins to an accretive driver — representing the single most significant near-term re-rating catalyst for the stock.
AI-Driven Efficiencies: Compounding the Flywheel. Grab’s AI infrastructure investment — which pushed regional corporate costs to $114 million in Q1 (management says this will now stabilize) — is already generating operational returns. Turbo driving mode’s 23% improvement in driver earnings is the most tangible example. The company is deploying AI across demand forecasting, dynamic pricing, credit scoring, fraud detection, and hyper-personalized in-app recommendations. CEO Anthony Tan has spoken of “leaning deeply into AI to out-serve our users,” and while such language is now ubiquitous across technology earnings calls, Grab’s data advantage — billions of transactions across ride, delivery, payment, and credit — gives its AI investment a differentiated training set that smaller regional players simply cannot replicate.
Regional Ecosystem Expansion. Grab’s partners — drivers, merchants, and food vendors — earned more than $15 billion on the platform in 2025, up 19% year-over-year. This is not just a financial statistic; it is the foundation of a political economy. When regulators in Jakarta or Kuala Lumpur consider regulatory interventions, the two to three million gig workers whose livelihoods depend on Grab’s marketplace represent a constituency that moderates the most punitive policy impulses. It is a structural mitigant that is rarely modelled in sell-side EBITDA scenarios, but it is real.
Looking toward 2028, analysts at Jefferies project meaningful EBITDA contribution from the Taiwan foodpanda integration, fintech segment profitability at scale, and continued GMV expansion across the core mobility and deliveries businesses — all compounding against a base of deep market share leadership.
Risks: A Balanced View
No credible investment analysis is complete without a clear-eyed accounting of the risks. For Grab, they are as follows:
Regulatory contagion. The Indonesia commission cap could inspire similar moves by regulators in Malaysia, Vietnam, or the Philippines — particularly as government interest in platform worker protections intensifies across the region. A coordinated regulatory tightening across multiple markets would require a more fundamental reassessment of the profit trajectory.
Fuel and macroeconomic volatility. Elevated fuel prices compress driver earnings and create upward pressure on Grab’s partner incentives, which reached $650 million in Q1 2026 (on-demand incentives at 10.5% of GMV). In a prolonged fuel crisis, the cost of keeping supply healthy could erode margin gains elsewhere.
Credit quality in lending. The loan book’s rapid expansion — doubling in a year — is a potential source of portfolio quality risk if Southeast Asian macroeconomic conditions deteriorate. Management says credit quality remains within risk appetite, but this warrants close monitoring as the portfolio scales toward $2 billion.
GoTo consolidation. A potential Grab–GoTo merger, which remains speculative despite persistent market discussion, could face lengthy antitrust review. A combined entity would hold an extraordinary concentration of market power — potentially approaching 99% in some Indonesian segments — creating genuine regulatory risk and execution complexity.
Integration of Taiwan operations. The Foodpanda Taiwan acquisition introduces a new geography with different consumer behaviors, competitive dynamics (iFood, local players), and regulatory requirements. Integration costs will weigh on near-term profitability before EBITDA contribution materializes post-2028.
The Investment Thesis: Dislocated Quality in a Structurally Growing Market
Grab’s current market valuation presents a familiar paradox: a company delivering record profitability, 17 consecutive quarters of EBITDA growth, a $5 billion net cash position, and a $489 million trailing free cash flow run rate — trading at a price that implies the market is discounting nearly everything that has gone right and pricing in everything that could go wrong.
The Indonesia commission cap is a real headwind. But its actual scope — affecting less than 6% of Mobility GMV — has been clarified, management has reiterated its full-year margin guidance, and Grab’s response has been measured and regulatory-cooperative rather than adversarial.
The deeper story is one of structural positioning in a region undergoing rapid digital transformation. Southeast Asia’s internet economy is forecast to reach $600 billion in GMV by 2030. Grab, with its 51.6 million monthly transacting users, eight-country footprint, growing fintech platform, and AI-powered operational flywheel, is the closest thing the region has to an indispensable digital infrastructure provider.
With 26 of 27 analysts maintaining Buy ratings, a consensus price target implying 65–70% upside, a PEG ratio of just 0.18, a Moody’s Ba2 credit upgrade, and management buying back $400 million of its own stock at these prices, the signals are pointing in a consistent direction.
The market, as is its occasional habit, appears to be confusing a regulatory headwind with a structural impediment. Analysts who have followed Grab since its 2021 SPAC listing — and through its long, disciplined journey from billion-dollar losses to sustained profitability — are not making that mistake.
Conclusion: The Long Game in Southeast Asia
Thirteen years ago, Anthony Tan and Tan Hooi Ling launched a modest ride-hailing app in Malaysia, pitching it to taxi drivers who had grown skeptical of a market moving beneath their feet. Today, Grab is the economic backbone of daily life for more than 50 million users across Southeast Asia’s most dynamic cities — connecting people with transport, food, credit, insurance, and income in a single application.
The Indonesia commission cap is a genuine test of regulatory relationship management and cost structure resilience. It is not an existential threat to a company holding $5 billion in net cash, generating nearly half a billion dollars in annual free cash flow, and growing adjusted EBITDA at 46% in what it describes as its softest seasonal quarter.
In markets like Southeast Asia, where regulatory landscapes shift and macroeconomic conditions fluctuate with greater frequency than in developed markets, the defining advantage is not the absence of headwinds. It is the institutional capacity to absorb, adapt, and continue compounding. Grab, by every operational and financial measure available, has demonstrated that capacity. The analysts who have spent years studying the company’s ecosystem have taken note.
The market, it seems, is still catching up.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Citibank & Dólar Estadounidense: Forex Playbook After the Xi-Trump Truce

How the Trump-Xi White House Summit Is Reshaping Mortgage Rates Today for Real Estate Investors

Indonesia Navigates Mega-Project Risks as China and Russia Eye the 2,772km Trans-Kalimantan Railway

Trump-Xi 2026 Summit Takeaways: The Trade Truce, Taiwan, and the AI Divide

Solar Panel Installation Cost in 2026: Why the Math Changed Overnight

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Auto Insurance Quotes: How to Get the Lowest Rate Without Losing Coverage

Huntington Online Banking: Full Features, Fees, and How It Compares in 2026

Apply for a Bank Account Online: What You Need and How Long It Actually Takes

World’s Largest Economies: Ranking the Top Global Powers

Business Loan: A Complete 2026 Guide to Rates, Types, and Qualifying

Fast Invoice Factoring: How to Turn Unpaid Invoices Into Cash Within 24 Hours

Investment Banking Services: What They Cost and How to Choose the Right Firm in 2026

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

BRICS+ Cross-Border Payments 2026: Interoperability Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

IMF & World Bank 2026 Global Economic Outlook: Growth, Inflation, Debt

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

High-CPM Finance Niches 2026: Publisher Monetization Blueprint

Middle East War Economics 2026: Oil Prices & Energy Markets
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025