
Analysis
What Does the Iran Conflict Mean for Global Central Banks? The Answers Unfortunately Depend on How Long the Conflict Lasts

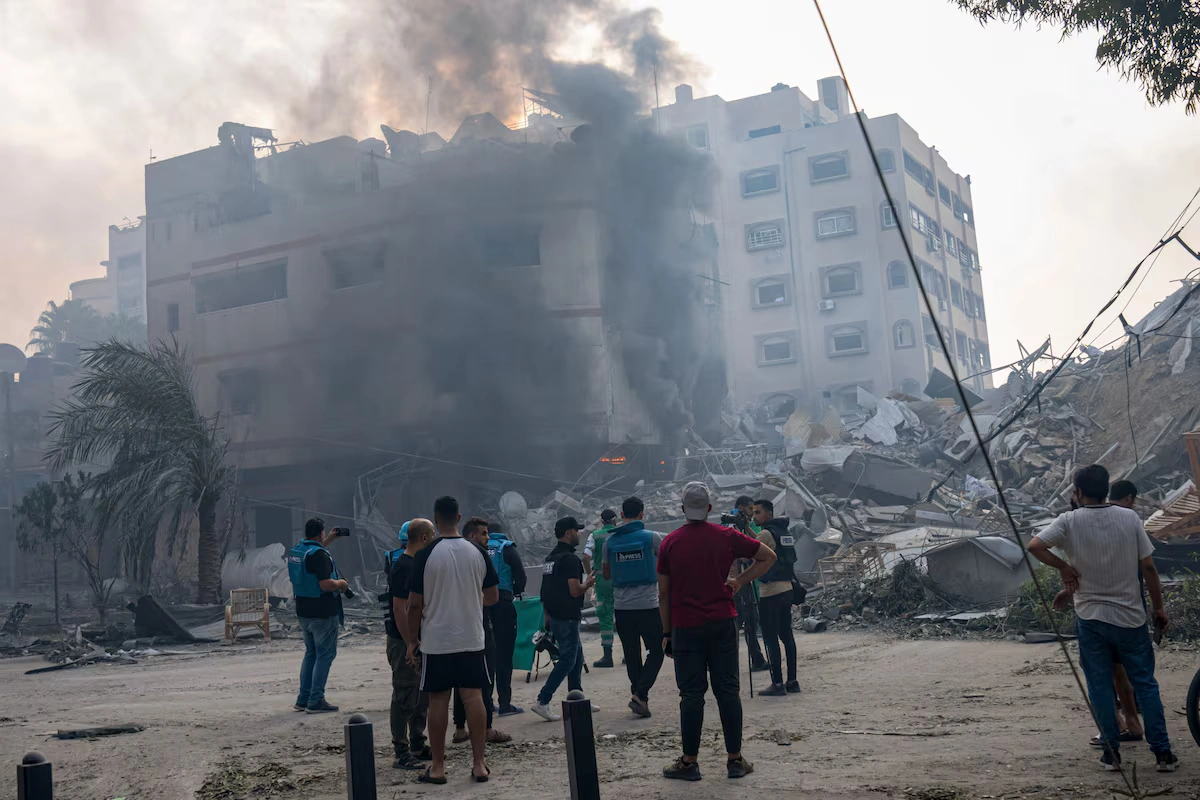
The strikes came before dawn on February 28, 2026. Within hours, the geopolitical architecture that central bankers had quietly priced into their models for years had collapsed — replaced by something far more volatile, far more dangerous, and infinitely harder to forecast. The US-Israel military campaign against Iran, which killed Supreme Leader Ayatollah Ali Khamenei along with more than 500 others in its opening salvo, did not just reshape the Middle East. It sent a seismic tremor through every trading floor, finance ministry, and central bank boardroom on the planet.
By the time Asian markets opened on March 3, the damage was already visible. Major indexes in Tokyo, Seoul, and Hong Kong shed between 2% and 2.5%. Gold — the world’s oldest fear gauge — surged past $5,330 per ounce, a record that would have seemed unthinkable even six months ago. Oil prices, already elevated by months of regional tension, lurched toward the $80–$100 per barrel range as traders frantically repriced the risk of Strait of Hormuz disruption. In Dubai and Abu Dhabi, explosions rattled skylines that had long marketed themselves as symbols of Gulf stability. Hezbollah activated across Lebanon’s southern border. US forces reported casualties in Kuwait.
Central banks — institutions built on the premise of calm, methodical deliberation — suddenly found themselves navigating a crisis with no clear runway.
The brutal truth, which policymakers in Washington, Frankfurt, Tokyo, and Mumbai are only beginning to articulate publicly, is this: what the Iran conflict means for global central banks depends almost entirely on how long the fighting lasts. Short-term containment leads to one playbook. A prolonged, multi-front war writes an entirely different one — and it is not a comfortable read.
The Oil Shock Ripple Effect
Start where every macroeconomist must start right now: oil. The oil shock from the Iran conflict is not merely a supply disruption story. Iran produces roughly 3.4 million barrels per day and controls strategic chokepoints through which nearly 20% of the world’s seaborne oil passes. As Reuters has reported, the preliminary market reaction already reflects deep anxiety about Hormuz closure scenarios, with Brent crude futures pricing in a war-risk premium not seen since the 2003 Iraq invasion.
But oil’s inflationary sting in 2026 arrives in a world that is structurally different from 2003 — or even 2022. Central banks in the US, Europe, and much of Asia spent two years aggressively tightening monetary policy to break post-pandemic inflation. Many were only beginning to ease. Rate cuts, cautiously telegraphed through late 2025, were supposed to provide relief to slowing economies. The Iran escalation has placed all of that in jeopardy.
A sustained move to $100/bbl or beyond would, according to JPMorgan’s commodities research desk, add approximately 0.5–0.8 percentage points to headline inflation across G7 economies within two quarters. For central banks already wrestling with “last-mile” disinflation — the stubborn core inflation that resists rate cuts — this is precisely the wrong kind of supply shock at precisely the wrong time.
Key inflationary transmission channels to watch:
- Fuel and energy — the most direct pass-through, affecting transport, manufacturing, and utilities within weeks
- Food prices — fertilizer costs, shipping rates, and agricultural logistics all move with oil
- Supply chain repricing — firms that endured 2022 may move faster to rebuild inventory buffers, driving input cost inflation
- Freight and insurance premiums — Gulf routing disruptions could spike global shipping costs by 30–60%, echoing Red Sea crisis dynamics from 2024
The Fed’s Dilemma in a Volatile World
No institution faces a more acute version of this dilemma than the US Federal Reserve. The impact of Iran war on the Federal Reserve is simultaneously an inflation problem, a growth problem, and a financial stability problem — all arriving at once.
Coming into February 2026, the Fed had cut rates twice from their 2024 peak and was widely expected to deliver two more cuts before year-end. That calculus is now suspended. The Fed finds itself caught between two uncomfortable poles: ease too aggressively, and it risks embedding a new inflation psychology at a moment when energy prices are spiking; hold rates too long, and it risks amplifying the contractionary demand shock that always accompanies serious geopolitical disruptions.
As the New York Times noted in its initial conflict coverage, investors are already pulling back from risk assets in patterns that mirror early COVID-era capital flight. The dollar, paradoxically, has strengthened — a typical safe-haven response — even as US equities fell. This complicates the Fed’s domestic picture: a stronger dollar tightens financial conditions without any Fed action at all.
Fed Chair messaging in the days since the strikes has been notably cautious. Expect extended “data-dependent” language that essentially means: we are waiting to see if this is a 10-day conflict or a 10-month one. The Iran geopolitical risks to monetary policy are simply too scenario-dependent for the Fed to commit to a forward path right now.
Short conflict (under 30 days): Fed likely stays on hold for one meeting cycle, resumes cut trajectory by Q2 2026 if oil retreats below $85/bbl. Prolonged conflict (3–6+ months): Fed pauses all easing indefinitely; potential rate hike discussion re-emerges if inflation re-accelerates above 3.5%.
ECB and BoE: Balancing Inflation and Growth
If the Fed’s dilemma is painful, the European Central Bank’s is arguably worse. The question of how the Iran war affects ECB rate cuts lands in a Eurozone economy that was already decelerating. Germany, never fully recovered from the energy shock of 2022–23, is particularly exposed. Europe imports roughly 90% of its oil needs, and unlike the US, it has no domestic production buffer to cushion a Gulf supply shock.
The ECB had been navigating a gentle easing cycle — the most delicate in its history — threading the needle between a weakening German industrial base and still-elevated services inflation in southern Europe. A sustained oil shock from the Iran conflict snaps that thread. ECB President Christine Lagarde faces the same stagflationary ghost that haunted her predecessor during the 2022 energy crisis: slowing growth and rising prices, with no clean policy response to either.
ING Think’s macro team estimates that a $20/bbl sustained oil increase above baseline adds roughly 0.4 percentage points to Eurozone CPI — enough to delay the ECB’s rate-cut path by at least two meetings. The Bank of England faces near-identical mathematics, compounded by the UK’s unique vulnerability to financial market volatility given London’s role as a global trading hub.
European central bank scenario matrix:
| Conflict Duration | ECB Response | BoE Response |
|---|---|---|
| Under 30 days | Pause cuts by 1 meeting | Pause cuts by 1 meeting |
| 1–3 months | Suspend 2026 cut cycle | Suspend 2026 cut cycle |
| 3–6 months | Consider emergency liquidity tools | Emergency repo window activation |
| 6+ months | Full stagflation protocol | Coordinated G7 response likely |
Asian Central Banks on High Alert
The dimension most underreported in Western financial coverage is the pressure now bearing down on Asian central banks amid Iran oil prices. And the pressure is severe — for reasons both economic and geopolitical.
Japan imports almost all of its energy. The Bank of Japan, only recently beginning its long-awaited normalization after decades of ultra-loose policy, faces a genuine threat to that trajectory. A sustained oil shock would push Japanese import costs sharply higher, weakening the yen and importing inflation through a channel the BoJ cannot easily offset with rate policy alone.
India’s Reserve Bank presents a different but equally acute case study. India is the world’s third-largest oil importer, and energy subsidies remain politically sensitive. The RBI, which had been managing a careful balance between rupee stability and growth support, now faces the prospect of renewed currency pressure as oil costs inflate the current account deficit. The Atlantic Council’s energy security desk has flagged India, Pakistan, and several Southeast Asian economies as particularly vulnerable to a prolonged Gulf conflict, given their lack of strategic petroleum reserve depth.
China occupies an ambiguous position. As a major oil importer, China suffers from higher prices. But China also has significant diplomatic and economic ties to Iran and may see strategic opportunity in a prolonged US military entanglement in the Middle East. The People’s Bank of China will likely prioritize yuan stability and domestic liquidity above all else, potentially accelerating yuan-denominated oil trade deals as a longer-term structural response.
Asian central bank pressure points at a glance:
- 🇯🇵 Bank of Japan — normalization path threatened; yen weakness accelerating
- 🇮🇳 Reserve Bank of India — current account stress, rupee under pressure, inflation uptick risk
- 🇰🇷 Bank of Korea — export growth headwinds; equity market selloff creating financial stability concern
- 🇨🇳 People’s Bank of China — yuan stabilization priority; watching US dollar dynamics closely
- 🇸🇬 Monetary Authority of Singapore — trade-dependent economy faces dual shock from oil and risk-off capital flows
uration Matters: Short vs. Long-Term Scenarios
Here is the honest reckoning that every central banker is running privately right now — and every investor should be running too.
Scenario A: Contained Conflict (Under 30 Days)
If the US-Israel campaign achieves its military objectives quickly, Iran’s retaliatory capability is degraded, and the Strait of Hormuz remains open, then oil markets could normalize toward $75–80/bbl within weeks. Gold would likely retrace from its record highs. Central banks — Fed, ECB, BoE, and the major Asian institutions — would pause briefly, absorb the data, and resume their pre-conflict trajectories by mid-2026. This is the market’s base case as of early March, reflected in the relatively contained (if painful) equity selloffs.
Scenario B: Prolonged Conflict (3–6+ Months)
This is where the geopolitical risks to the global economy in 2026 become genuinely systemic. A multi-month war involving Iranian missile campaigns, Hezbollah front activation, and potential Hormuz closure would constitute the most significant energy supply shock since 1973. In this scenario:
- Oil sustains above $100/bbl, potentially spiking toward $130–150/bbl in a Hormuz closure event
- Global inflation re-accelerates, forcing central banks into a new tightening cycle — or at minimum, abandoning all planned easing
- Recession risk in Europe rises sharply; US growth slows materially
- Emerging markets with dollar-denominated debt face a brutal combination of a strong dollar, high oil, and capital flight
- Central banks may be forced into rare coordinated action — reminiscent of 2008 and 2020 — to stabilize financial markets
As the Wall Street Journal’s economics desk has observed, the policy toolkit for stagflationary shocks is genuinely limited. You cannot simultaneously fight inflation and support growth through conventional rate policy. Something has to give.
The Deeper Question: Is Monetary Policy Even the Right Tool?
There is a broader, uncomfortable truth buried in all of this analysis. Central banks are being asked to manage consequences of a geopolitical crisis they had no hand in creating and no power to resolve. The Iran conflict and central banks narrative often implies that the right interest rate setting can somehow insulate economies from war. It cannot.
What monetary policy can do is prevent a supply shock from becoming a permanent inflation psychology, maintain financial system liquidity, and signal credibility to markets under stress. What it cannot do is replace the barrels of oil that stop flowing, rebuild the supply chains disrupted by Gulf instability, or restore the business confidence shattered by images of explosions in Dubai.
The Financial Times’ coverage of central bank responses has rightly noted that the real test will be coordination — between central banks, between fiscal authorities, and between allied governments on strategic petroleum reserve releases. The International Energy Agency has already begun consultations on coordinated SPR deployment, a move that could take as much as 1.5–2 million barrels per day of supply pressure off the market if executed at scale.
Central Bank Response Comparison Table
| Central Bank | Pre-Conflict Stance | Short Conflict Response | Prolonged Conflict Response |
|---|---|---|---|
| US Federal Reserve | Gradual easing | Pause cuts, hold | Halt easing; hike risk if inflation >3.5% |
| European Central Bank | Gentle easing cycle | Delay 1–2 cuts | Suspend cycle; stagflation protocol |
| Bank of England | Cautious easing | Hold and reassess | Emergency liquidity measures |
| Bank of Japan | Early normalization | Slow normalization | Pause; defend yen via intervention |
| Reserve Bank of India | Neutral/mild easing | Currency intervention | Rate hold; capital flow management |
| People’s Bank of China | Selective stimulus | Yuan stabilization | Accelerate alternative trade mechanisms |
| Bank of Korea | Hold | Hold; equity market monitoring | Emergency rate cut risk if recession |
What History Tells Us — And Why 2026 Is Different
The 1973 Arab oil embargo. The 1979 Iranian Revolution. The 1990 Gulf War. The 2003 Iraq invasion. Each of these conflicts produced oil shocks that reshaped monetary policy for years. But 2026 is different in several important ways that make simple historical analogies dangerous.
First, central banks enter this crisis with far less policy room than they had in most prior episodes. Interest rates, while off their peaks, remain above neutral in most major economies. Quantitative easing balance sheets are still elevated. The “whatever it takes” toolkit is not empty — but it is leaner.
Second, the global economy in 2026 is more financially interconnected than at any prior point in history. Sovereign wealth funds from the Gulf states manage trillions in global assets. A prolonged conflict could force asset liquidations that ripple through bond and equity markets in ways entirely unrelated to oil prices themselves.
Third — and perhaps most importantly — this conflict involves direct US military action, not proxy involvement. The geopolitical risk premium on the dollar, on US Treasuries as safe havens, and on the broader rules-based international economic order is being repriced in real time.
Conclusion: Diversify, Stay Informed, and Resist Panic
The honest answer to the question posed in this article’s headline is also the most unsatisfying one: we don’t know yet. The Iran conflict’s meaning for global central banks will be written in the days and weeks ahead as the military situation either stabilizes or deepens.
What we do know is this: central banks will be reactive, not proactive. They will watch oil, watch inflation expectations, watch currency markets, and watch credit spreads with extraordinary vigilance. They will communicate carefully and commit cautiously. And they will be managing the consequences of a war, not solving it.
For investors, the message is equally clear. Geopolitical risks to the global economy in 2026 are no longer tail risks — they are the central scenario. Portfolios built on the assumption of continued easing cycles and stable energy markets need urgent reassessment.
Consider speaking with a qualified financial advisor about:
- Energy sector exposure and commodity diversification
- Safe-haven asset allocation (gold, CHF, JPY in a contained scenario)
- Duration risk in bond portfolios given inflation uncertainty
- Emerging market exposure, particularly in oil-importing Asian economies
- Geographic diversification away from single-region concentration
The world’s central banks are doing what they always do in moments like this: buying time, gathering data, and hoping the politicians and generals resolve the crisis before they are forced to make decisions no monetary tool was designed to handle. The rest of us would be wise to prepare for the possibility that this time, the hoping may not be enough.
Sources & Further Reading:
- Reuters: How US-Iran tensions could shape world markets
- New York Times: Investors Brace for Stock Market’s Reaction
- Wall Street Journal: What the Iran Conflict Means for the Global Economy
- Financial Times: What does the Iran conflict mean for global central banks?
- JPMorgan Commodities Research
- Atlantic Council: Gulf Energy Security
- ING Think: Eurozone Macro Analysis
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Beyond Paper Wealth: Unpacking Donald Trump’s Multibillion-Dollar Liquidity and Legal Crisis

Bitcoin & XRP 2026: Inside Crypto’s Institutional Era

Global Economy 2026: IMF Growth, AI Stocks & Market Risk

China’s Local Debt Race Against Time: Why Economists Demand Central Action Before the Deflation Window Closes

Money News: How to Protect Your Portfolio From Global Inflation

World Bank Projections: Emerging vs. Big Economies of Asia

IMF Reports 2026: What the Latest Data Means for the Global Economy

Singapore Stocks Outlook: A Safe Haven in the Asian Market?

China Stocks vs. Japan Stocks: Where Should You Invest in Late 2026?

VIX Index Explained: How to Trade Wall Street’s Fear Gauge Today

Commercial vs Residential Real Estate: Which Wins in 2026?

Presidential Stock Market Performance: How Trump’s Second Term Compares to History

2026 Real Estate Market News: Are We Heading for a Correction?

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

BRICS+ Cross-Border Payments 2026: Interoperability Explained

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025