
AI
The AI Impact on Jobs: Augmentation, Deflation, and Survival

In early 2026, Arthur & Hayes, a mid-sized London accounting firm, quietly fired its bottom quintile of junior analysts. They replaced them not with offshore labour in cheaper time zones, but with a highly specialized, locally hosted instance of generative AI. The subsequent industry panic was predictable. Yet, the true AI impact on jobs is rarely as cinematic as mass layoffs orchestrated by a central algorithm. Instead, the global labour market is undergoing a silent, structural rewiring. We are shifting away from a binary panic over human obsolescence toward a colder, more clinical reality. This new era is defined by task unbundling, extreme cognitive wage deflation, and explosive productivity divergence. To survive this transition, we must abandon science fiction and look strictly at the macroeconomic tape.
The global conversation remains stubbornly trapped in a doom-loop of speculation. But the hard data tells a sharper, more specific story. According to the OECD’s 2026 Employment Outlook, roughly 27% of jobs in advanced economies rely heavily on skills that algorithms can currently execute with zero marginal cost. Still, automation is not the same as outright elimination. The Bank of England recently published findings indicating that while administrative roles are contracting at 4.2% annually, aggregate employment has held steady. This stability is driven by lateral workforce shifts into newly formed operational categories.
This creates a macroeconomic paradox. We are simultaneously experiencing acute talent shortages in systems engineering and a brutal hollowing out of middle-management cognitive labour. To make sense of this turbulence, executives and professionals require a new mental model. The restructuring of the workforce demands a colder analytical framework, broken down into three distinct realities.
1. The Myth of the Intact Job (Task Unbundling)
The first way to understand this shift is to separate the concept of a “job” from a “task.” On March 14th of this year, when lead researcher Dr. Elena Rostova at MIT CSAIL evaluated the economic viability of computer vision replacing human oversight, she found a glaring flaw in the mainstream narrative. Employers do not hire humans to perform single, isolated tasks. They hire humans to manage messy, highly bundled portfolios of responsibilities. Generative AI does not destroy entire jobs; it acts as a solvent, liquidating specific, repetitive tasks within them.
This task unbundling forces a radical reassessment of professional value. Consider a corporate lawyer. A junior associate spends perhaps 30% of their day drafting boilerplate contracts and conducting baseline discovery—tasks that language models now execute with near-perfect fidelity in seconds. The remaining 70% of their role involves client negotiation, strategic structuring, and reading the emotional temperature of a boardroom.
The World Economic Forum tracks the financial outcome of this dynamic as the “augmentation premium.” Workers who aggressively integrate artificial intelligence into their daily workflows are commanding a 15% wage premium over their un-augmented peers. The algorithm is not a rival employee. It is an aggressive filter that removes the most repetitive fractions of cognitive work, leaving only the high-judgment, uniquely human elements behind.
2. Generative AI Job Displacement and the Squeeze on Average
The second paradigm shift is the collapse of the cognitive middle class. For three decades, the financial premium attached to a university degree was driven by the corporate market’s insatiable demand for basic information processing. Generative models have effectively driven the marginal cost of producing average text, boilerplate code, and baseline financial analysis to zero.
This triggers a harsh economic reality. If your primary economic value lies in synthesizing public information into readable summaries, your market value is depreciating rapidly. MIT economist Daron Acemoglu refers to this dynamic as “so-so automation”—technology that is just competent enough to displace human labour, but not revolutionary enough to radically boost overall economic productivity. We are watching the automation of mediocrity.
Will AI replace my job?
AI will not entirely replace most jobs, but it will fundamentally restructure them. Roles heavily reliant on repetitive data processing, basic coding, or generic copywriting face severe wage deflation. Conversely, jobs requiring high-stakes physical intervention, complex strategic judgment, or intense human empathy remain highly protected.
The picture is more complicated than mere job losses. We are witnessing a stark bifurcation in the labour market. The ceiling for elite, highly skilled workers is rising exponentially. Today, AI tools allow a single talented programmer or financial analyst to achieve the output of a ten-person team. At the exact same time, the floor is falling out from under entry-level white-collar roles. The traditional corporate apprenticeship model—where junior staff learn the trade by executing tedious grunt work—is actively breaking down. If algorithms execute the foundational work, the pipeline for training the next generation of senior partners effectively vanishes.
3. Artificial Intelligence and the Future of Work: The Metamorphosis
The third and most difficult way to conceptualize the AI transition is through the lens of pure creation. Historically, technology creates entirely new categories of labour that were fundamentally unimaginable to previous generations. The invention of the electronic spreadsheet in the 1970s did not eradicate accountants; it birthed the modern, multi-billion-dollar financial modelling industry.
Today, we are seeing the genesis of what the National Bureau of Economic Research classifies as “frontier employment.” These are roles dedicated entirely to managing, auditing, and steering non-human intelligence. Global enterprises are desperately hiring AI compliance officers, algorithmic bias auditors, and synthetic data architects. By May 2026, corporate demand for specialized “AI alignment directors” in London and San Francisco outpaced traditional software engineering roles for the first time in history.
The downstream consequences for small and medium enterprises (SMEs) are profound. A boutique design agency of five people can now command the creative and operational output previously reserved for global firms carrying hundreds of staff members. This asymmetric power allows micro-businesses to bid on, and win, enterprise-level contracts. Yet, it also means that the technological barrier to entry has evaporated entirely. When anyone can generate infinite, high-quality digital assets for pennies, the core economic value shifts. Value moves away from the creation of assets toward the distribution, curation, and taste governing those assets. We are entering an era where editorial judgment and trusted, face-to-face human relationships hold the ultimate market premium.
The Luddite Fallacy or a Genuine Breaking Point?
Not everyone accepts this relatively measured view of task transition. A vocal, highly credentialed contingent of labour economists warns that applying historical frameworks to generative AI is a fatal analytical error. Previous technological revolutions—from the steam engine to the microchip—replaced physical labour or routine computational mathematics. Generative AI is the first technology to successfully substitute for human reasoning itself.
Critics argue that the “augmentation” defense is a temporary comfort. As foundational models scale, they will inevitably consume the high-judgment, strategic tasks we currently consider uniquely human. Stanford economist Erik Brynjolfsson warned earlier this year that the velocity of capability overhang in AI models outpaces the human ability to adapt. The International Monetary Fund (IMF) published a stark structural warning in late 2025, suggesting that up to 40% of global employment is critically exposed to AI disruption. Unlike past transitions in agriculture or manufacturing, the safety net of the modern service sector offers no geographic refuge.
If a machine can soon reason, write, and code better than the median college graduate, the fundamental social contract of the modern economy fractures. The opposing view asserts that we are not merely unbundling tasks; we are steadily marching toward absolute cognitive obsolescence. This camp argues that radical macroeconomic policy interventions, such as Universal Basic Income (UBI) or severe algorithmic taxation, will be required long before the decade ends.
The Final Calculation
The narrative surrounding artificial intelligence and the labour market is paralyzing precisely because it demands we hold contradictory truths simultaneously. We are facing unprecedented cognitive wage deflation, yet overall productivity for those who adapt is soaring. Algorithms are liquidating tasks at a startling pace, yet the market demand for high-level human judgment has never been more acute.
Executives, policymakers, and workers cannot afford the luxury of panic. The transition requires a ruthless, unsentimental audit of one’s own economic utility. If your market value is derived solely from processing existing information marginally faster than a human peer, you are competing in a race you have already lost. The premium now lies in ambiguity—in the messy, unquantifiable spaces where algorithms hallucinate, fail, and lack physical presence. The future of work belongs not to those who can out-compute the machine, but to those who know exactly what to ask it.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Nvidia altered its geographic revenue reporting methodology after the quarter ended July 2025, the period in which Singapore accounted for roughly 22 percent of total sales—approximately $10.2 billion. In subsequent disclosures, Singapore disappeared from the geographic breakdown. The change coincided with intensifying scrutiny of Singapore-based Megaspeed International and broader US export-control concerns around advanced AI chips. Wall Street Journal
The company moved from classifying revenue by customer billing location to classifying it by the location of the customer’s headquarters. Large amounts of revenue previously shown under Singapore were thereby reclassified under US-headquartered customers. Physical shipments that remained inside Singapore had always been a small fraction of the total; the issue is one of billing-hub transparency. Reuters Breakingviews
Investors, analysts, and regulators now have materially less visibility into sales routed through one of the world’s most important semiconductor contracting and invoicing centers at precisely the moment when diversion questions are most acute.
Table of Contents
- What Exactly Changed in Nvidia’s Reporting?
- Why Did Singapore Revenue Disappear from the Tables?
- What Is the Megaspeed Connection?
- How Material Was Singapore to Nvidia’s Revenue?
- How Does This Affect NVDA Transparency and Governance?
- What Should Investors Watch Next?
- Key Takeaways
- Frequently Asked Questions
What Exactly Changed in Nvidia’s Reporting?
Through the quarter ended 27 July 2025, Nvidia presented geographic revenue according to the location where the customer was billed. Under that method Singapore ranked among the company’s largest markets. Beginning with the following quarter the company switched to the location of the customer’s corporate headquarters. Restated historical figures moved the bulk of the former Singapore amount into the United States line. Wall Street Journal
The change is permissible under accounting rules; it is the timing and the resulting loss of visibility that have drawn attention.
Why Did Singapore Revenue Disappear from the Tables?
Singapore has long functioned as a regional billing, contracting, and holding-company hub for technology firms even when the physical product ships elsewhere. Nvidia itself had previously noted that the great majority of items invoiced in Singapore were destined for other countries. Once headquarters location became the classification key, any customer whose parent was US-domiciled ceased to appear under Singapore regardless of where the invoice was raised. Reuters
What Is the Megaspeed Connection?
Megaspeed International, a Singapore-registered cloud and data-center company, became the subject of reporting concerning large purchases of Nvidia chips and questions about whether those chips reached restricted end-users. Nvidia placed Megaspeed on an internal block list. The reporting-methodology change occurred in the same narrow window. US officials have examined possible diversion pathways through third-country intermediaries. Wall Street Journal
The temporal overlap does not by itself prove causation, but it has led investors to ask for a clearer explanation.
How Material Was Singapore to Nvidia’s Revenue?
At its peak under the old method, Singapore represented 22 percent of quarterly revenue—more than $10 billion in a single quarter and a dramatic rise from earlier years. Singapore’s share of Nvidia’s billing had climbed sharply as AI demand accelerated, reflecting both genuine Asia-Pacific growth and the city’s role as an invoicing center. Wall Street Journal and Reuters
How Does This Affect NVDA Transparency and Governance?
Reduced geographic granularity makes it harder for outsiders to monitor concentration risk and potential export-control exposure in real time. While total company revenue is unchanged, the loss of a previously prominent line item lowers the quality of disclosure precisely when external scrutiny is highest. Some investors and commentators have argued that Nvidia should provide supplemental information to restore visibility. Wall Street Journal
Timeline of Key Events
| Period | Singapore Visibility | Concurrent Development |
|---|---|---|
| Through July 2025 quarter | Explicit ~22 % of sales | Peak billing share |
| Shortly thereafter | Removed from geographic table | Methodology switch; Megaspeed block |
| Subsequent quarters | Limited public detail | Ongoing export-control focus |
What Should Investors Watch Next?
Management commentary on the rationale for the change, any supplemental geographic or end-market data, updates on export-control investigations, and the trajectory of data-center revenue in Asia-Pacific under the new classification. The upcoming earnings cycle offers a natural opportunity for clarification.
Key Takeaways
- Singapore once represented approximately 22 percent of Nvidia revenue under billing-location reporting.
- The company switched to headquarters-based reporting and Singapore disappeared from the tables.
- The timing overlaps with Megaspeed scrutiny and Nvidia’s internal block-list decision.
- Physical shipments remaining in Singapore were always small; the issue is billing transparency.
- Investors have less granular data with which to assess diversion and concentration risks.
Frequently Asked Questions
Did Nvidia stop selling to customers who invoice in Singapore?
No. The change affects classification and disclosure, not necessarily underlying commercial relationships.
How much revenue was reclassified?
Billions of dollars previously presented under Singapore were largely moved to the US-headquartered category in restated figures.
Is the reporting change related to export controls?
The company has not confirmed a direct link, but the timing and the Megaspeed context have led many observers to examine the two together.
Does the change affect the accuracy of total revenue or earnings?
No. Consolidated revenue and profit figures are unaffected; only the geographic breakdown is less detailed.
What would improve transparency from here?
Supplemental disclosure on billing-hub activity, end-customer regions, or export-compliance metrics would address the principal investor concern.
Conclusion
Nvidia’s decision to cease breaking out Singapore revenue after that market reached 22 percent of sales has reduced transparency at a sensitive juncture for export controls and investor confidence. For finance and technology audiences the episode illustrates how billing hubs, disclosure choices, and national-security rules intersect in the AI supply chain. Clearer communication from the company—whether through supplemental data or explicit explanation—would help restore the usefulness of geographic reporting for one of the world’s most systemically important semiconductor businesses. Until then, the Singapore line item’s disappearance remains a live governance and risk-monitoring issue.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
In an era defined by global economic volatility, supply chain fracturing, and the relentless search for post-pandemic growth drivers, middle powers face a stark choice: passively import technological paradigms dictated by foreign tech superpowers or aggressively architect a sovereign framework that harnesses next-generation efficiencies. Under Prime Minister Anthony Albanese, Australia has chosen the latter.
Navigating the delicate equilibrium between accelerating productivity gains and enforcing robust governance, the Albanese administration’s strategic pivot toward artificial intelligence (AI) has emerged as a compelling blueprint for modern statecraft. Far from a mere policy footnote, Australia’s calculated embrace of AI integration is positioning the nation’s economy for an unprecedented transformation—one projected to inject billions into the domestic ledger while safeguarding social cohesion.
The Productivity Imperative: Bridging the Gap
For years, advanced economies have grappled with sluggish productivity growth—a trend that has severely tested traditional fiscal and monetary levers. Australia has been no exception, confronting multi-decade lows in labour productivity growth that have squeezed profit margins, constrained real wage progression, and fueled cost-of-living anxieties.
Enter artificial intelligence. Economic modelling highlights that large-scale AI adoption could unlock up to AUD $142 billion annually for the Australian economy by 2030, serving as a multi-factor productivity catalyst. Rather than viewing technological automation as a displacement threat, Canberra’s policy machinery has reframed AI as an essential force multiplier across key national sectors—from mining optimisation and agricultural tech to precision manufacturing under the Future Made in Australia agenda.
Small and medium-sized enterprises (SMEs)—the lifeblood of the domestic economy—stand to gain immensely. By automating administrative burdens, streamlining compliance, and optimising supply chain logistics, AI integration allows local businesses to redirect capital toward innovation and high-value creation.
Pioneering a World-First Regulatory Framework
What separates Australia’s approach from the fragmented regulatory environments of the United States or the heavy-handed compliance models of the European Union is its proactive, harmonised architecture.
In July 2026, the Albanese government unveiled a world-leading national AI framework designed to provide certainty for investors while establishing strict guardrails for ethical deployment. Key pillars of this strategy include:
- Sovereign Standards and Intellectual Property Protection: Australia became a global pioneer by enacting clear protections ensuring that local creative works, literature, music, and journalistic output cannot be scraped for AI training models without explicit artist consent and compensation.
- Streamlined Compliance for Frontier Investments: By establishing unified national standards, the framework cuts through bureaucratic red tape, offering international investors expedited approval pathways conditional on adherence to safety and security benchmarks.
- A Binding Social Licence: The framework emphasises that technology must serve human agency. Ensuring public trust remains paramount; algorithms cannot operate as black boxes when critical public services, employment markets, and national security are involved.
Navigating the Geopolitical and Economic Crosswinds
Australia’s economic strategy does not exist in a vacuum. As great power competition reshapes global trade and globalisation pivots toward regional resilience, Canberra is leveraging its vast reserves of critical minerals, rare earths, and clean energy assets.
AI acts as the computational glue binding these traditional resource strengths with future-facing capabilities. For instance, optimising the extraction and processing of critical minerals required for global energy transitions relies heavily on advanced machine learning models and automated logistics. By coupling its natural resource abundance with top-tier university research and skilled graduate pipelines, Australia is making a compelling pitch to global venture capital: come build here, on Australian terms.
Comparative Strategic Advantages
| Strategic Pillar | Traditional Model | Australia’s AI-Integrated Approach |
| Productivity Driver | Capital investment & raw volume expansion | Multi-factor efficiency via sovereign AI deployment |
| Regulatory Stance | Reactive policy or unbridled laissez-faire | Proactive, world-first unified national standards |
| Workforce Strategy | Reliance on lagging skills adaptation | Empowering workers through institutional AI literacy and secure transitions |
| IP & Innovation | Lax protections for digital creators | Enforceable ownership rights over AI training inputs |
The Road Ahead: Can Australia Stick the Landing?
While the macroeconomic projections are dazzling, translating policy ambition into structural reality carries inherent risks. The success of Albanese’s vision will ultimately be judged by execution metrics over the remainder of the decade:
- Skills Alignment: Ensuring that the national education and vocational training sectors can rapidly upskill workers to meet the demands of an AI-augmented labour market.
- Cybersecurity Resilience: As critical infrastructure becomes increasingly digitised and reliant on automated machine-learning networks, national security frameworks must scale defensively to prevent state-sponsored cyber exploitation.
- Equitable Distribution: Ensuring that productivity dividends do not concentrate solely within major metropolitan tech hubs, but actively flow to regional communities and working-class Australians.
Conclusion
Australia’s economic narrative under the Albanese administration is shedding the old tropes of the “lucky country” relying purely on cyclical commodity booms. Instead, it is writing a new chapter of purposeful economic design. By harmonising technological disruption with rigorous ethical standards and worker-centric policies, Australia is proving that middle powers do not have to be passive spectators in the digital revolution—they can help write the rules of the game.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
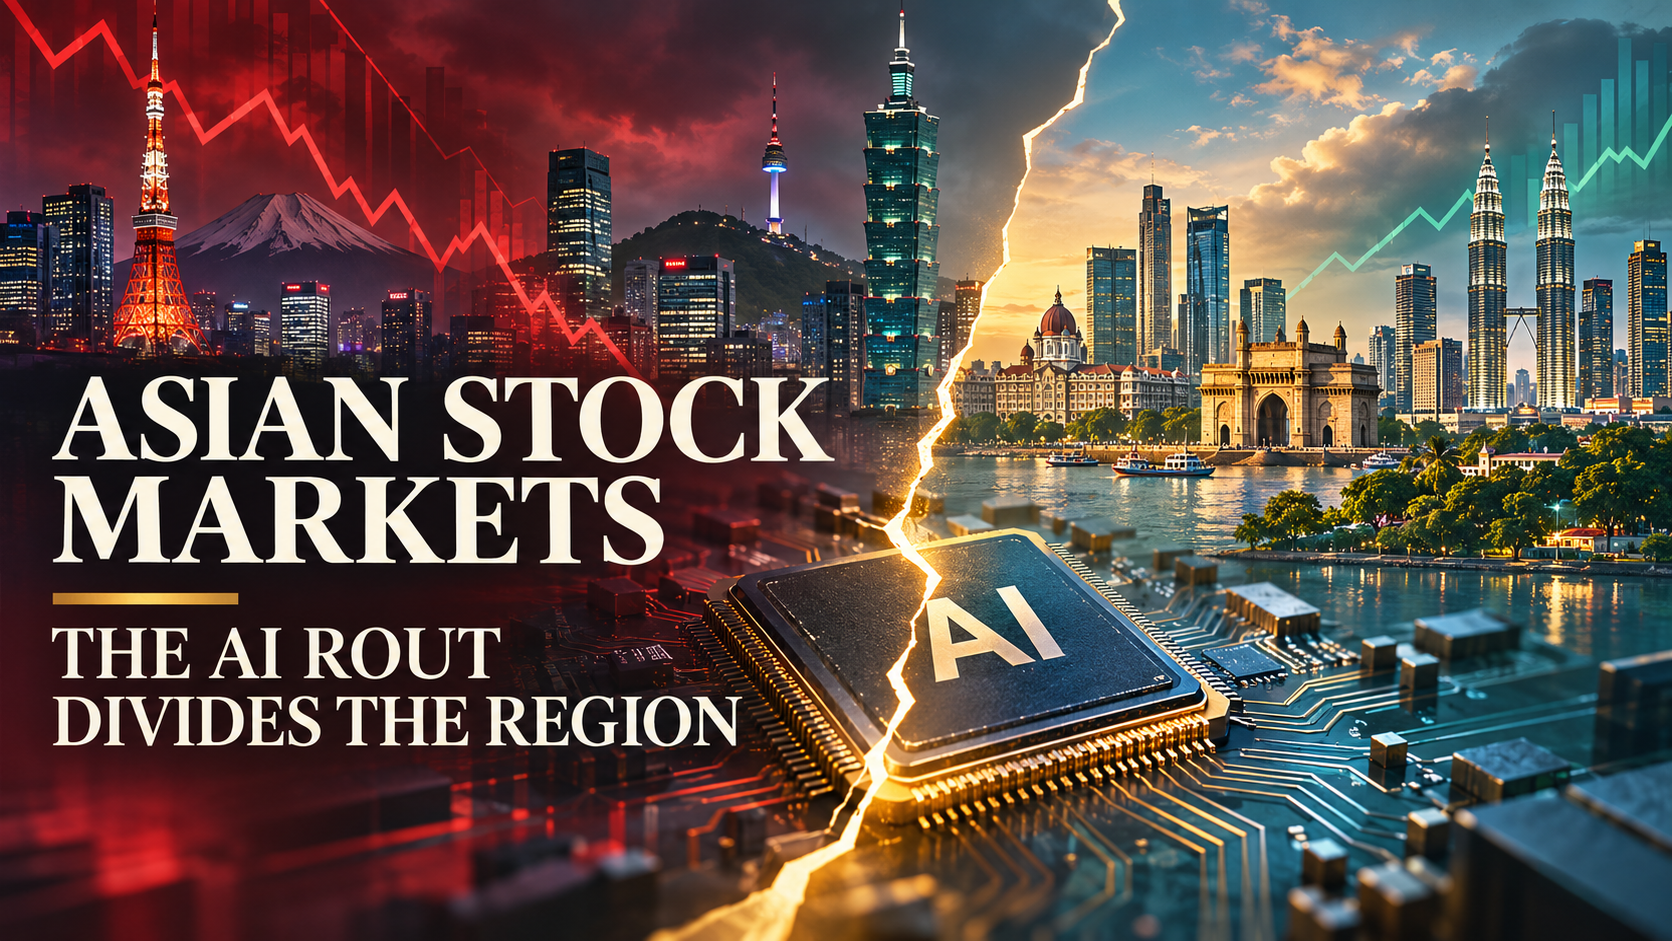
The global AI retreat is not producing a uniform Asian reaction. The crucial dividing lines run through semiconductors, imported energy and domestic earnings.
The global AI retreat is not producing a uniform Asian reaction. The crucial dividing lines run through semiconductors, imported energy and domestic earnings. This analysis draws on primary documents and contemporaneous reports available on November 6, 2026; subsequent market movements or policy announcements may change the outlook.
Asian equities illustrate the danger of treating the region as a single asset class. Reuters reported on November 6 that South Korea’s Kospi had fallen about 8% and Japan’s Nikkei about 5% during the regional technology rout, while India’s Nifty 50 advanced roughly 0.51%. The divergence is notable because investors had spent years viewing Asian markets through a shared narrative of AI-led investment and export growth.
The IMF’s October Asia-Pacific outlook anticipated regional growth easing from 4.8% in 2026 to 4.4% in 2027, while still contributing disproportionately to global expansion. That is a strong headline but no guarantee for any individual exchange or company.
Chip supply chains create asymmetric risk
Japan, South Korea and Taiwan occupy different parts of the semiconductor, component and manufacturing ecosystem. Memory producers, equipment makers and foundries benefit when chip production and installation accelerate. Their shares can also fall sharply if markets question the volume, margins or ultimate returns on AI investment.
It is simplistic to equate the market reaction with the disappearance of AI demand. A business may continue growing while its share price corrects because valuations previously assumed flawless execution for years. Investors must separate an actual order cancellation from a fall in the multiple they are willing to pay for those orders.
India offers a different earnings composition.
India’s benchmarks include substantial financial, consumer and domestic-facing businesses. Lower imported crude prices can improve macroeconomic expectations through inflation, the trade balance and corporate margins. Reuters reported strong foreign buying on November 5 as sentiment improved. Such resilience can be meaningful even though it may reverse on later sessions.
An index’s headline performance can also conceal divergence. Financials may rise while smaller companies, richly valued technology suppliers or exporters weaken. A well-constructed comparison checks market breadth and earnings concentration instead of stopping at one benchmark return.
China and Hong Kong face their own constraints.
Chinese and Hong Kong-listed assets respond to property conditions, domestic consumption, export restrictions, currency dynamics and policy credibility. Their technology exposure overlaps with but is not identical to the U.S. AI trade. If global investors rotate away from expensive semiconductor leaders, relative valuations can help other markets—but only where credible profit growth supports them.
Exchange-rate effects complicate international performance. A local index can rise in home currency and still lose value for an investor whose base currency strengthens. Cross-border comparisons should therefore state whether results are in local currency or U.S. dollars.
Energy import dependence changes the ranking
The World Bank commodity outlook projects an elevated oil-price environment in 2026. Higher fuel prices reduce household purchasing power and raise transport and production costs in import-dependent economies. A reversal can offer relief, but the benefit varies with subsidy structures, hedging and exchange rates.
For Asian investors, the most revealing basket is not simply “technology versus everything else.” It includes oil-import sensitivity, export revenues, cash generation, financing costs and regulatory conditions. This is why a global shock can produce deeply divergent Asian sessions.
What a closer look at the source record shows
The available record supports a useful separation between confirmed developments and interpretation. The first column below identifies the type of evidence; the second explains the analytical use, not an independently measured market statistic.
| Research focus | How it informs this story |
|---|---|
| Confirmed evidence | Reuters Asian market divergence |
| Interpretive opportunity | Contrast national sector mixes |
| Secondary question | Use oil import exposure |
| Next verification | Track earnings guidance from memory suppliers and export manufacturers alongside crude prices and foreign portfolio flows. |
The research priority is relevance rather than sheer citation volume. Repeated references to the same press release do not represent independent confirmation, and authoritative data can support a narrower claim than an ambitious headline suggests. Wherever a numerical fact is used, the source date and stated coverage should travel with it.
How to interpret the evidence without overclaiming
The regional average hides national balance sheets. Manufacturers, banks, households and governments experience an oil shock differently. Even countries in the same region may face opposite effects through exports, import bills and currencies. In this article’s subject—Asian stock markets 2026—that distinction prevents superficially precise figures from becoming misleading conclusions. A credible account should explain exactly which evidence supports each inference and what would change the analysis.
The most useful comparison holds time and currency constant. Always align trading dates and specify whether reported returns are local-currency returns, translated-dollar returns or total returns. Otherwise, a comparison can be precise in appearance and misleading in substance. Track earnings guidance from memory suppliers and export manufacturers alongside crude prices and foreign portfolio flows. These checks are important because individual data points can be correct while the story assembled from them is incomplete.
Three specific tests make the coverage stronger:
- Contrast national sector mixes. Ask what the underlying observation actually measures, which population or companies it covers, and how recent it is. A relevant primary document outweighs a popular unsourced claim.
- Use oil import exposure. Compare plausible explanations and resist attributing every market or policy movement to one event. When an observed change has several possible causes, explain which are supported and which remain hypotheses.
- Separate multiple compression from demand. Describe what new fact would falsify the prevailing interpretation. Reporting that cannot be revised in the face of new evidence is advocacy, not analysis.
Three Asian market paths worth distinguishing
Technology spending stabilises. Asian chip exporters could recover if cloud companies reaffirm orders and memory suppliers report stable contract pricing. The recovery would still be uneven: a foundry, a memory producer and a consumer-electronics manufacturer respond to different demand drivers. Confirmation should come from corporate order books and earnings rather than a single regional index rebound.
A deeper investment retrenchment. If financing and power constraints delay new data-centre capacity, export-orientated producers in Japan, South Korea and Taiwan could face prolonged multiple compression and order revisions. Currency volatility may intensify foreign-investor returns, while an oil-price rebound would again pressure importers. The IMF’s regional growth projection would remain a baseline, not proof that equity earnings are safe.
Domestic-market rotation persists. India could continue to outperform on better energy terms of trade, bank earnings and household consumption even while North Asian technology stocks remain volatile. Yet an inflow-driven rally becomes fragile if valuations run ahead of earnings. Compare domestic profits, net foreign flows and oil import costs within each country before making regional generalisations.
A practical research checklist
A reader evaluating this issue should first open the primary sources linked in the article and check their publication dates. Next, identify the specific claim being tested, its units and its geographic or institutional scope. Then compare that evidence with at least one independent account, asking whether the sources are reporting the same underlying data or repeating one another. Finally, distinguish a dated observation from a prediction and note the developments that would demand an update.
For a working editorial desk, this sequence is equally important. A clearly dated article can remain valuable after prices or politics change if its explanations endure and its volatile numbers are identified as snapshots. An article that quietly presents yesterday’s quote as today’s fact, by contrast, loses credibility even when the broader argument is sensible.
Questions readers are asking
Why did India outperform some Asian markets on November 6?
Reuters highlighted lower oil prices, foreign inflows and rotation away from AI-related names as important contributors.
Are all Asian technology stocks exposed equally?
No. Memory, foundry, equipment, consumer electronics and software firms face different customers and valuation risks.
Does lower oil help every Asian country?
No. Net importers often benefit, while exporters and energy producers can be hurt, subject to domestic policy and exchange rates.
Which data matters for an Asia comparison?
Synchronised index closes, local currency moves, industry weights, foreign flows, sovereign yields and corporate earnings.
The judgement
The global AI retreat is not producing a uniform Asian reaction. The crucial dividing lines run through semiconductors, imported energy and domestic earnings. The most responsible conclusion is conditional: Track earnings guidance from memory suppliers and export manufacturers alongside crude prices and foreign portfolio flows. The argument should evolve when new source material is published, rather than being defended simply because it made a compelling headline on November 6. For readers, the value is a clearer distinction among what has already happened, what remains uncertain and what developments would actually change the decision.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Lisa Su: AMD Is Now a “Data Center First Company” – 2027 Outlook

Reasons for Falling US Gas Prices in November 2026: A Seasonal Shift

SoftBank’s $3.7 Billion Turbine Loss: What the AI Power Bet Reveals

Hong Kong Land Acquires Wheelock Place and Renames It Landmark Orchard

DBS PayLah China QR Expansion: Now Accepted at Over 100 Million Merchants

Nvidia Stops Reporting Singapore Revenue After It Hit 22% of Sales: What Investors Need to Know

Global Trade and Tariffs 2026:WTO Barometer Still Shows Growth

Extended Producer Responsibility Changes and the UK Hospitality Sector

GDP and Economic Growth in the US: How It’s Measured, Current Trends

Economic Globalization: How Global Trade Shapes the US Economy, Jobs, and Consumers

Best Life Insurance Companies in the United States 2026: Our Top 5 Picks

Pakistan Auto Policy 2026-31 Explained: EV Tax Cuts, $6 Billion Export Target

When Dollar Debt and Food Imports Collide: The Currency Squeeze

Why Freight and Storage Costs Keep Food Prices High After Oil Falls

Dow Jones Today: Dow Slips 237 Points After the Worst Day Since April 2025

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

SSI November 2026 Payment: Why Benefits Arrive October 30

2027 Federal Tax Brackets: New IRS Rates and Standard Deductions Explained

Singapore Stock Market Outlook 2027: The STI’s Bank-and-Yield Test

IMF Global Outlook 2027: The Recovery Is Real, but the Divide Is Growing

World Bank Debt Report 2026: The $9.4 Trillion Burden Behind the Recovery

Stock Market Crash 2026? What the November Rout Actually Tells Us

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Global Markets Today: The AI Sell-Off Has Become a Test of Liquidity

Democrats Won Congress. Can They Fix the U.S. Economy

Global Finance 2027: Debt, Inflation and AI Are Pulling the Economy Apart
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis9 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis9 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks10 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment10 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy11 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy11 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025