
Opinion
Boeing’s 500-Jet China Deal: Trump-Xi Summit’s $50B Game-Changer

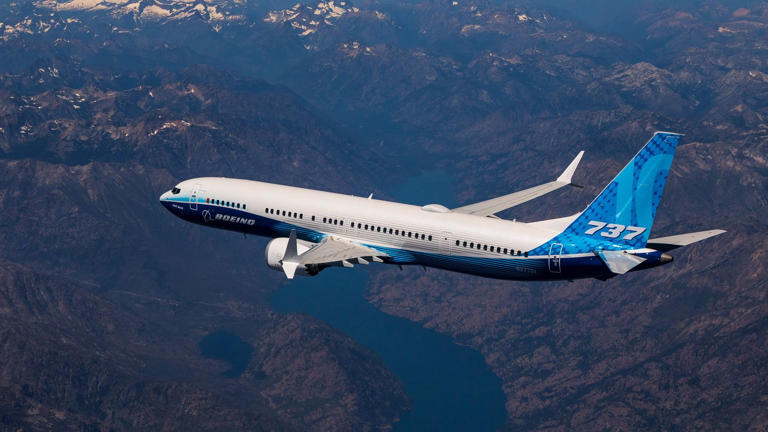
On a Friday afternoon in early March, Boeing’s stock did something it hadn’t done in months: it surged. Shares of the aerospace giant jumped as much as 4 percent — the best performance on the Dow Jones Industrial Average that day — after Bloomberg reported that the company is closing in on one of the largest aircraft sales in its 109-year history. The prize: a 500-aircraft order for 737 Max jets from China, to be unveiled when President Donald Trump makes his first state visit to Beijing since 2017 — scheduled for March 31 to April 2.
If confirmed, the deal would represent nothing less than Boeing’s formal re-entry into the world’s second-largest aviation market after years of diplomatic cold-shouldering, safety-related groundings, and trade-war turbulence. It would also cement a pattern that has quietly defined Trump’s second term: the systematic use of America’s largest exporter as a diplomatic sweetener in geopolitical negotiations.
The Numbers Behind the Boeing 737 Max China Deal
Let’s be precise about what is reportedly on the table. According to people familiar with the negotiations cited by Bloomberg, the headline figure is 500 Boeing 737 Max jets — narrowbody, single-aisle workhorses that form the backbone of Chinese domestic aviation. Separately, the two sides are in advanced discussions over a widebody package of approximately 100 Boeing 787 Dreamliners and 777X jets, though that portion of the deal is expected to be announced at a later date and would not feature in the Trump-Xi summit communiqué.
At current list prices — the 737 Max 8 carries a sticker price of roughly $101 million per aircraft — the narrowbody package alone would approach $50 billion in nominal terms before the standard deep discounts that large airline orders attract. Factor in the widebody tranche, and the full package could eventually represent the single largest bilateral aviation deal ever struck between the United States and China.
Boeing itself declined to comment. China’s Ministry of Commerce did not respond to requests outside regular hours. The White House offered no immediate statement. But the market spoke clearly enough.
A Decade of Order Drought — and Why China Needs Boeing Now
To appreciate the magnitude of this potential agreement, consider the context. China once made up roughly 25 percent of Boeing’s order book. Today, Boeing holds only 133 confirmed orders from Chinese airlines — approximately 2 percent of its total book. Investing.com That collapse in Chinese demand was not accidental. It was the deliberate consequence of a cascade of crises: the global grounding of the 737 Max following two fatal crashes in 2018 and 2019, the trade tensions of Trump’s first term, and the pandemic-era freeze on civil aviation procurement.
Yet Chinese airlines have been quietly suffocating under constrained fleet capacity. Aviation analysts and industry sources say China needs at least 1,000 imported planes to maintain growth and replace older aircraft. WKZO The country’s carriers — Air China, China Eastern, China Southern — are operating aging fleets while passenger demand has rebounded sharply. The arithmetic of Chinese aviation is unforgiving: a country of 1.4 billion people, a rapidly expanding middle class, and a domestic network that still relies heavily on Western-certified jet technology cannot simply wait indefinitely for political stars to align.
Beijing has also been hedging. China is simultaneously in talks for another 500-jet order with Airbus that would be in addition to any Boeing deal — negotiations that have been in on-off discussions since at least 2024. WKZO But Airbus has its own capacity constraints and delivery backlogs. The reality is that both European and American planemakers are needed to feed China’s aviation appetite, which gives Boeing considerable strategic leverage — if it can navigate the politics.
Trump’s Boeing Diplomacy: A Playbook Refined
There is a recognizable pattern here, and it is worth naming explicitly. Trump has used Boeing as a tool to sweeten accords with other governments Yahoo Finance, and the China deal fits squarely within that framework. Earlier in his second term, large Boeing orders from Gulf carriers and Southeast Asian airlines followed Trump diplomatic visits — deals that generated political headlines and tangible employment commitments in American manufacturing states.
The Beijing summit, however, would be the most significant deployment of this strategy yet. US-China trade tensions have been acute in early 2026. Trump threatened to impose export controls on Boeing plane parts in Washington’s response to Chinese export limits on rare earth minerals. Yahoo Finance During earlier trade clashes, Beijing ordered Chinese airlines to temporarily stop taking deliveries of new Boeing jets — before resuming later that spring. WKZO
That on-off pattern illustrates the extraordinary vulnerability of commercial aviation to geopolitical temperature. Unlike soybeans or semiconductors, a Boeing 737 Max is not a fungible commodity. It requires years of certified maintenance infrastructure, pilot training, and regulatory framework built around American aviation standards. Both sides know this, which is precisely why aircraft orders have become such potent bargaining chips.
The planned summit structure — Trump in Beijing from March 31 to April 2, followed by Xi visiting Washington later in the year — also suggests a two-stage negotiation architecture. The 737 Max order would serve as a confidence-building gesture at the first meeting; the widebody 787 and 777X tranche would follow as trust is consolidated.
Boeing’s Recovery Trajectory: Why Timing Matters
For Boeing CEO Kelly Ortberg, the timing of a China breakthrough could scarcely be more critical. Boeing’s total company backlog grew to a record $682 billion in 2025, primarily reflecting 1,173 commercial aircraft net orders for the year, with all three segments at record levels. Boeing Yet the Chinese market has remained conspicuously absent from that recovery story.
Boeing has achieved FAA approval to increase 737 Max production to 42 jets per month, a significant step toward restoring manufacturing capacity, and the company plans to raise 787 Dreamliner output to 10 aircraft per month during 2026. Investing.com In short, for the first time in several years, Boeing actually has the industrial capacity to absorb a massive new order. Management has targeted approximately 500 737 deliveries in 2026 and 787 deliveries of roughly 90–100 aircraft, while targeting positive free cash flow of $1–3 billion for the year. TipRanks
A confirmed China order of this scale would not merely boost the backlog — it would validate the entire recovery narrative. It would signal to Wall Street that the 737 Max safety rebound is complete, that Chinese regulators have definitively recertified the aircraft, and that geopolitical risk has sufficiently receded to justify multi-year procurement commitments. As Reuters reported, Boeing’s share price rose 3.7 percent on the news — but analysts caution that several sticking points remain unresolved, and a deal is not yet assured.
Aviation Ripple Effects: What a China Mega-Deal Means for Global Travelers
The significance of a Boeing 737 Max China order in 2026 extends well beyond corporate balance sheets. Chinese carriers operating newer, more fuel-efficient 737 Max jets would dramatically expand route networks — both domestically and internationally. The 737 Max 10, capable of flying roughly 3,300 nautical miles at maximum range, opens trans-regional routes that older Chinese narrowbody fleets cannot economically serve.
For the global travel industry — and for the Expedia-era traveler booking multi-stop itineraries across Asia — this translates into more competitive airfares, denser flight schedules out of Chinese hub airports, and expanded connectivity between Chinese secondary cities and international destinations. Tourism economists estimate that each percentage point increase in seat capacity on a major international corridor correlates with a 0.6 to 0.8 percent increase in inbound tourist arrivals. A Chinese aviation expansion of this magnitude, fuelled by 500 new-generation jets, would register meaningfully in global travel demand forecasts through the late 2020s.
The geopolitical calculus cuts the other way too. Should talks collapse — perhaps due to escalation over Taiwan, renewed rare-earth export controls, or a postponement of the Trump visit, which Bloomberg noted could occur if the ongoing US-Iran situation deteriorates — Boeing’s China exposure remains an open wound rather than a healed scar.
Historical Context: The Ghosts of Boeing-China Deals Past
This would not be the first time a US presidential visit to China generated a headline Boeing order. In 2015, during Barack Obama’s final engagement with Xi Jinping, Chinese carriers placed orders for over 300 Boeing jets — a deal that at the time was celebrated as a pillar of the bilateral commercial relationship. It took less than four years for that relationship to unravel under the dual pressures of the MAX crisis and Trump’s first-term tariffs.
The lesson is not that such deals are illusory. It is that they are fragile by design — deeply dependent on the political weather. A Boeing 500-plane order tied to Trump’s Beijing summit is, in that sense, simultaneously a genuine commercial transaction and a diplomatic performance. Its durability will depend less on what is signed in Beijing in April than on what is negotiated, month by month, in the trade relationship that follows.
Forward Outlook: Promise, Risk, and the Long Game
Boeing’s aircraft stand to feature prominently in whatever trade framework emerges from the Trump-Xi summit. But seasoned observers of US-China commercial aviation will note that a similar mega-deal euphoria surrounded Airbus last year — and ultimately failed to materialize. Given the fraught geopolitical backdrop, Boeing’s order bonanza is not assured, and two people familiar with the talks have specifically cautioned that deal completion remains uncertain. Yahoo Finance
What is certain is this: the structural demand is real, the production capacity is finally in place, and the political incentive on both sides has rarely been stronger. For Boeing, recapturing even a fraction of what was once a market that constituted a quarter of its order book would represent a transformation of its strategic position. For China’s airlines, new Boeing jets mean competitive fleets, lower operating costs, and the capacity to serve a travelling public that has never stopped wanting to fly.
The planes, as ever, are ready. The question is whether the politics will let them take off.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Inflation stopped being a 2022 story and became a 2026 one again, and most portfolios were not rebuilt for it.
US consumer prices rose 0.4% in August and 3.4% over twelve months, with core inflation at 2.4%. Headline inflation peaked near 4.2% in May before easing.
The uncomfortable part is why it eased — and why it may not keep easing.
Key Takeaways
- Where inflation stands: US CPI at 3.4% annually, core at 2.4%, both above the Fed’s 2% target.
- Energy is the swing factor. Energy prices are up roughly 16.3% over the year.
- The driver is geopolitical, not monetary. Energy prices remain elevated due to the ongoing Middle East conflict.
- Central banks turned hawkish again. J.P. Morgan notes rhetoric has hardened, especially in emerging markets.
- Most “inflation hedges” are not. Only a handful of assets have historically tracked unexpected inflation.
What the Current Inflation Actually Is
Understanding the composition matters more than the headline, because different inflation requires different hedges.
| Component | August 2026 Move | Annual |
|---|---|---|
| Headline CPI | +0.4% | +3.4% |
| Core CPI | +0.3% | +2.4% |
| Energy | +2.1% | ~+16.3% |
| Shelter | +0.3% | Persistent |
| Food | +0.1% | Moderate |
The gap between 3.4% headline and 2.4% core is the entire story. Roughly a full percentage point of US inflation is energy, and energy is a function of the Strait of Hormuz rather than of monetary policy.
The July data showed the mechanism clearly. Energy prices fell 1.5% for the month following a 5.7% decrease in June, yet still showed an annual increase of 14.7% after sharp earlier gains including a 10.9% surge in March just after the attacks against Iran began.
Then August reversed it: gasoline rose sharply and headline inflation picked up again.
This is supply-shock inflation, not demand inflation. That distinction determines which hedges work.
Why This Inflation Is Hard for Central Banks
Interest rates are a demand tool. They do not produce oil.
J.P. Morgan Global Research began the year forecasting that global inflation would remain stable through 2026, but the energy price spike and strong global growth momentum are now stoking inflation and paving the way for monetary tightening. Central bank rhetoric has become more hawkish, particularly in emerging markets, with the ECB and Bank of Japan expected to raise rates.
That is the inversion investors must internalise: for the first time since 2022, the plausible next move in several major economies is up, not down.
EY’s assessment flags the persistence risk directly: geopolitical tensions and energy market volatility could generate renewed price pressures, while lingering tariff pass-through and strong investment tied to the AI buildout continue to support inflation in selected goods and technology-related categories.
Note the AI point. Information technology commodities rose 1.4% month-on-month in July, led by a 3.5% increase in computer prices. The AI buildout is itself inflationary in hardware categories.
What Actually Hedges Inflation
Most assets marketed as inflation hedges protect against expected inflation, which is already in the price. What you need protection against is unexpected inflation.
Tier 1: Direct Hedges
Inflation-linked bonds (TIPS and equivalents). Principal adjusts with CPI. This is the only asset explicitly contracted to track inflation. The trade-off is real yield risk: if real rates rise, TIPS still lose value.
Commodities and energy exposure. When inflation is energy, energy assets are a direct hedge rather than a correlated one. This is the cleanest match to the current shock. The cost is extreme volatility and negative roll yield in contango markets.
Short-duration bonds and cash. Not glamorous, but reinvesting at rising rates beats holding long-duration paper through a tightening cycle.
Tier 2: Partial Hedges
Equities with pricing power. Companies that can raise prices faster than costs preserve real earnings. Sectors with genuine pricing power — energy, some industrials, branded consumer staples, infrastructure — behave differently from the index.
Real assets. Infrastructure, timber, farmland and property with short lease terms reprice with inflation. Property with long fixed leases does not.
Floating-rate credit. Coupons reset upward. Credit risk rises in the same environment, so this is a partial hedge at best.
Tier 3: Unreliable Hedges
Gold. Works in currency debasement and crisis episodes. Its correlation with CPI is weak and inconsistent.
Bitcoin. Marketed as an inflation hedge; has behaved as a high-beta risk asset, falling roughly 50% from its October 2025 peak during a period of rising inflation.
Long-duration growth equities. Actively harmed by the rate response to inflation.
| Asset | Hedges Expected Inflation | Hedges Unexpected Inflation | Main Risk |
|---|---|---|---|
| TIPS | Yes | Yes | Real rate moves |
| Energy/commodities | Partly | Yes | Volatility, roll cost |
| Short-duration bonds | Yes | Partly | Reinvestment timing |
| Pricing-power equities | Yes | Partly | Margin compression |
| Short-lease real assets | Yes | Partly | Illiquidity |
| Gold | Inconsistent | Inconsistent | No contractual link |
| Long-duration bonds | No | No | Duration loss |
A Practical Rebuild
You do not need to restructure a portfolio around a 3.4% CPI print. You need to remove the positions that break in it.
- Audit your duration. The single biggest inflation vulnerability in most portfolios is long-dated fixed income. Check weighted average duration before anything else.
- Check your real return, not your nominal return. A 4% nominal gain against 3.4% inflation is a 0.6% real gain.
- Add explicit, not implicit, protection. A small TIPS allocation does what a “diversified” equity sleeve only claims to do.
- Hold energy exposure if your inflation is energy-driven. Match the hedge to the shock.
- Keep equity exposure. Over long horizons, equities have outpaced inflation more reliably than any alternative. Do not solve a two-year problem with a twenty-year mistake.
- Review internationally. Inflation is not uniform. Emerging market central banks have turned notably more hawkish than developed peers.
The Purchasing Power Reality
The uncomfortable macro backdrop: real economic conditions are cooling alongside inflation, with wage growth lagging price growth, meaning workers’ purchasing power is flat to negative.
For investors, that has a second-order effect. Consumer-facing businesses without pricing power face volume compression at exactly the moment their input costs rise. Sector selection matters more in this environment than it does in a normal one.
What This Means for the Global Market in 2027
Base effects will do the heavy lifting. By year-end, the base effect from the April–May 2026 peaks rolls out of the twelve-month calculation. If monthly readings stay low, the year-over-year rate could drop to 2.5–3.0% by December — a milestone likely to trigger rate-cut guidance.
That improvement is mechanical, not structural. A falling headline rate driven by base effects does not mean the underlying energy vulnerability is resolved.
Watch core, not headline. If core CPI drifts toward 2% the Fed has cover. If it stalls or reverses, it signals underlying pressure that policy must address regardless of oil.
The September CPI release on 14 October is the pivot point. Another 3%-plus gasoline gain suggests supply tightness; a 1–2% reversal marks August as an anomaly.
Emerging market importers face the worst of it. Countries importing energy without AI-export revenues absorb the shock with no offset — a dynamic both the IMF and World Bank have flagged as the defining 2026–27 divergence.
Frequently Asked Questions
What is the current US inflation rate?
US CPI rose 3.4% over the twelve months to August 2026, with core inflation at 2.4%. Headline inflation peaked near 4.2% in May before easing.
What is the best hedge against inflation?
Inflation-linked bonds such as TIPS offer the only direct contractual link to CPI. For energy-driven inflation specifically, commodity and energy equity exposure has been the closest match.
Is gold a good inflation hedge?
Gold’s correlation with CPI is weak and inconsistent. It has performed better as a currency-debasement and crisis hedge than as a pure inflation hedge.
Will inflation fall in 2027?
Base effects from the 2026 peaks should mechanically lower the annual rate toward 2.5–3.0% by December 2026. Whether it stays there depends on energy prices and core inflation persistence.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The World Bank’s June 2026 assessment carries a phrase that should stop any investor mid-scroll: a “lost decade” of development for many emerging markets.
Global growth is projected to slow from 2.9% in 2025 to 2.5% in 2026 — the lowest rate since the COVID-19 pandemic — amid weaker prospects for energy-importing economies and those directly affected by hostilities.
Within that aggregate, Asia is splitting into two distinct groups. Understanding which side an economy falls on is now the primary emerging-market allocation decision.
Key Takeaways
- Global growth: 2.5% in 2026, firming in 2027–28 as energy supplies recover and trade strengthens.
- The revision was brutal. January 2026 projected 2.6% with an upward revision; June cut it.
- India remains the outlier. FY2026-27 growth of 6.6%, rebounding to 7.2% in FY2027-28.
- China decelerates. Growth slowing to 4.4% in 2026 from 4.9%.
- The 2020s are on track to be the weakest decade for global growth since the 1960s.
The Two Reports That Define 2026
The World Bank publishes Global Economic Prospects twice a year, and the gap between the January and June 2026 editions is the story.
January: Cautious Optimism
The January report described a global economy proving more resilient than anticipated despite persistent trade tensions and policy uncertainty, with growth easing to 2.6% in 2026 before rising to 2.7% in 2027 — an upward revision from the previous June forecast.
About two-thirds of that upgrade came from the United States alone.
June: The Energy Shock
By June, the Middle East conflict had driven sharp energy price increases and the projection fell to 2.5%, with emerging market and developing economies facing the weakest per capita income growth since the pandemic.
The Bank explicitly notes that the conflict’s impact on global trade has been partly offset by robust AI-related investment, while consensus inflation expectations picked up notably following the energy price surge. Local-currency bond yields and external bond spreads remained higher in commodity importers.
That last sentence is the whole emerging-market thesis in one line: commodity importers are paying more to borrow at exactly the moment they need to borrow more.
Asia’s Two Tiers
| Economy | Projection | Position |
|---|---|---|
| India | 6.6% FY26-27, 7.2% FY27-28 | Domestic-demand-led, upgraded |
| China | 4.4% in 2026 (from 4.9%) | Export-supported, stimulus-dependent |
| EMDEs (all) | 4.0% in 2026 (from 4.2%) | Slowing |
| EMDEs excl. China | 3.7% in 2026 | Flat versus 2025 |
| United States | 2.2% in 2026 | Tax-incentive supported |
The EMDE-excluding-China figure of 3.7%, unchanged from 2025, is the number that matters most and gets quoted least. Strip out China, and the developing world is not slowing — it simply is not accelerating. Stagnation at a level too low to close income gaps.
The India Case
India stands apart in the June projections. Growth is projected to moderate to 6.6% in FY2026-27 — a 0.1 percentage point upgrade relative to January — before rebounding to 7.2% in FY2027-28, a 0.6 point upgrade.
The moderation reflects private demand cooling under input cost pressures. The rebound reflects structural factors:
- Trade agreements. Implementation of major FTAs with the EU, UK and Australia is described as crucial to offsetting cooling merchandise demand from traditional Western markets.
- FDI sustainability. Trade agreements and structural business reforms are expected to sustainably support inflows across the forecast horizon.
- Fiscal trade-offs. Lower fuel taxes and GST reforms temporarily erode the revenue base, requiring a shift toward slower public capex growth and current spending cuts to avoid deficit spikes.
That last point is the underappreciated risk. India’s growth upgrade is partly financed by revenue concessions that must eventually be reversed or absorbed.
The China Case
China’s projected slowdown to 4.4% in 2026 came with an upward revision of four-tenths of a percentage point from the previous June forecast, attributed to fiscal stimulus and increased exports to non-US markets.
That revision has since been validated by trade data. The question for 2027 is whether export strength can persist if global demand slows to the 2.5% pace the Bank projects.
China’s position is structurally different from India’s: externally driven where India is domestically driven, stimulus-dependent where India is reform-dependent.
What the “Lost Decade” Framing Actually Means
The World Bank’s language is deliberately stark. If current forecasts hold, the 2020s are on track to be the weakest decade for global growth since the 1960s and too low to avert stagnation and joblessness in emerging market and developing countries.
The distributional evidence is concrete: at the end of 2025, nearly all advanced economies enjoyed per capita incomes exceeding their 2019 levels, but about one in four developing economies had lower per capita incomes than before the pandemic.
Chief Economist Indermit Gill framed the underlying tension precisely: the global economy has become less capable of generating growth while appearing more resilient to policy uncertainty — a divergence he warned cannot persist without fracturing public finance and credit markets.
Investment Implications by Tier
Tier 1 — Energy importers in the technology value chain. India, Vietnam, Malaysia, Taiwan, Korea. AI-related export revenues offset higher energy costs. Currency and equity performance has held up.
Tier 2 — Energy exporters outside the conflict zone. Gulf states excluding those directly affected, parts of Africa and Latin America. Favourable terms of trade, fiscal space expanding.
Tier 3 — Energy importers outside the technology chain. Pakistan, Bangladesh, Sri Lanka, Kenya, much of Sub-Saharan Africa. Higher import bills, higher borrowing costs, no offsetting export windfall.
Tier 3 is where sovereign stress concentrates. Higher local-currency bond yields and wider external spreads in commodity importers mean refinancing costs rise as fiscal positions deteriorate.
What This Means for the Global Market in 2027
The 2027 recovery is conditional on two assumptions. Activity is expected to firm in 2027–28 as energy supplies recover and trade strengthens. Both require the conflict to de-escalate. Neither is guaranteed.
AI adoption is the identified upside. The Bank names artificial intelligence adoption, clean energy investment and regional trade agreements as potential long-term recovery catalysts. Only the first is currently delivering at scale.
Sovereign debt is the accumulating risk. Elevated yields in commodity importers compound every year they persist. A 2027 refinancing wave at current spreads would strain multiple frontier sovereigns simultaneously.
Regional trade agreements are the underrated policy lever. India’s FTA implementation is the clearest test case. If it delivers the projected FDI and export offset, it becomes a template for the rest of emerging Asia.
Compare the IMF and World Bank carefully. The Fund projects 3.0% for 2026; the Bank projects 2.5%. The difference is methodological — PPP versus market exchange rate weighting — not a disagreement about the world.
Frequently Asked Questions
What is the World Bank’s global growth forecast for 2026?
The June 2026 Global Economic Prospects projects global growth slowing to 2.5% in 2026, down from 2.9% in 2025 — the lowest rate since the pandemic.
What is India’s projected GDP growth?
India is projected to grow 6.6% in FY2026-27 before rebounding to 7.2% in FY2027-28, both upgrades relative to January 2026 projections.
Why are World Bank and IMF forecasts different?
The World Bank weights using market exchange rates while the IMF uses purchasing-power-parity weights, which gives more weight to faster-growing emerging economies.
What does “lost decade” mean for emerging markets?
The Bank warns the 2020s could be the weakest decade for global growth since the 1960s, with roughly one in four developing economies having lower per capita incomes at end-2025 than in 2019.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The International Monetary Fund has revised its view of the world economy three times in nine months, and the direction of travel is clear.
Global growth is now projected at 3.0% for 2026 and 3.4% for 2027 — down from the 3.5% average recorded across 2024–25.
The headline number, though, is the least interesting part of the report. What matters is why the Fund revised, and which economies it thinks will absorb the damage.
Key Takeaways
- The July 2026 forecast: 3.0% growth in 2026, 3.4% in 2027, broadly unchanged cumulatively from April.
- Two opposing forces. The Middle East war drags; the AI-driven technology cycle lifts.
- The split is not rich versus poor. It is energy exposure and position in the technology value chain.
- Inflation reversed course. The Fund projected headline inflation rising to 4.4% in its April assessment.
- Risks remain tilted downside. Longer conflict, AI expectation resets and fragmentation dominate the risk register.
The Forecast Trajectory Through 2026
| Report | 2026 Growth | 2027 Growth | Framing |
|---|---|---|---|
| October 2025 WEO | ~3.2% | 3.2% | Steady resilience |
| January 2026 Update | 3.3% | 3.2% | Revised slightly up |
| April 2026 WEO | 3.1% | 3.2% | “Reference forecast” under war |
| July 2026 Update | 3.0% | 3.4% | War drag vs AI lift |
Read as a sequence, this tells a story that a single data point cannot. January was optimistic: the Fund saw technology investment, fiscal and monetary support and accommodative financial conditions offsetting trade policy shifts.
Then war broke out.
April: The Reference Forecast
The April 2026 WEO abandoned the traditional baseline entirely. It presented instead a reference forecast predicated on the assumption that the war would have limited duration, intensity and scope, with disruptions fading by mid-2026, consistent with commodity futures prices as of 10 March.
That is an unusual methodological choice and worth understanding. The Fund was explicitly saying: we cannot forecast this, so here is a conditional projection plus scenarios.
Chief Economist Pierre-Olivier Gourinchas framed the reversal directly: the global economy had been on a steady trajectory around 3.3% and the Fund was looking to upgrade its projections before the war stopped that momentum, with inflation rising to 4.4%.
He identified three transmission channels: higher energy and food prices themselves; persistence in wage and price inflation; and a confidence shock.
The adverse scenario modelled oil prices rising 80% and gas prices 160% from the second quarter of 2026 relative to January assumptions.
July: The AI Offset
The July Update introduced the year’s most important analytical point. The modest slowdown reflects the effects of the Middle East war being partly offset by accelerated demand-driven momentum in the global technology cycle, thanks to advances in artificial intelligence and its adoption.
Critically, the impact varies by two dimensions at once:
- Energy exporters outside the conflict zone benefit from favourable terms of trade.
- Economies plugged into the technology-led upturn experience stronger activity even if they are energy importers.
- Energy importers with limited participation in the technology value chain see activity weaken.
That third category is where the damage concentrates. It captures much of South Asia, Sub-Saharan Africa and parts of Latin America — economies paying more for energy without the AI export revenues to offset it.
This is the single most actionable framework in the 2026 IMF reporting. It explains why Japan and Korea have outperformed while frontier importers have stalled.
What the Reports Say About Major Economies
The January Update projected advanced economy growth of 1.8% in 2026 and 1.7% in 2027, with the United States expanding 2.4% in 2026 supported by fiscal policy and a lower policy rate, before settling at 2.0% in 2027 with a near-term boost from corporate investment tax incentives.
On inflation dynamics, the Fund noted inflation in China rising from low levels, while inflation in India was expected to return to near-target levels after a 2025 decline driven by subdued food prices.
Russia was projected to maintain growth of 1.1%.
Why Investors Should Read IMF Reports Differently
Most market participants treat the WEO as a headline number. Three better uses:
- The revision direction beats the level. A forecast cut from 3.3% to 3.0% tells you more about policy trajectory than the absolute figure does.
- The scenarios are the real content. The April adverse scenario’s 80% oil assumption is a stress test you can apply to your own portfolio.
- The country tables are underused. Annex Table 1’s selected-economy real GDP growth figures cover economies accounting for approximately 83% of world output.
How the IMF and World Bank Differ
The two institutions use different methodologies and produce different numbers for the same year. The IMF projects 3.0% global growth for 2026 on purchasing-power-parity weights. The World Bank projects 2.5% using market exchange rate weights.
Neither is wrong. PPP weighting gives more weight to faster-growing emerging economies. Market-rate weighting reflects actual dollar-denominated output. Quote the one that matches your analytical frame — and never compare the two headline figures directly.
Risks the Fund Flags
- Longer or broader conflict. The reference forecast assumes containment. It is an assumption, not a projection.
- AI expectation reset. A reassessment of expectations surrounding AI-driven productivity could significantly weaken growth and destabilise financial markets.
- Geoeconomic fragmentation. Trade and technology bloc formation raises costs structurally.
- Elevated public debt. Combined with eroding institutional credibility, this heightens vulnerabilities.
- Defence spending trade-offs. The Fund specifically warns policies must carefully manage the trade-offs involved in ramping up defence expenditure.
What This Means for the Global Market in 2027
3.4% in 2027 is a recovery forecast, not a boom. It sits well below the 2000–19 historical average of 3.7%, and the Fund expects growth to settle near that lower rate in the medium term.
The AI offset is a concentrated bet. If the technology cycle disappoints, there is no second offsetting force in the model. The war drag remains; the lift disappears.
Inflation persistence is the policy trap. Rising headline inflation alongside slowing growth limits how far central banks can cut, which in turn limits the equity valuation support markets have priced.
Energy-importing frontier economies face a structural squeeze. Pakistan, Bangladesh, Sri Lanka, Kenya and similar economies sit precisely in the Fund’s worst-affected category.
Watch the October 2026 WEO. It will be the first full report to assess whether the war disruptions actually faded on the assumed timeline. If they did not, the reference forecast framework collapses and forecasts move materially lower.
Frequently Asked Questions
What is the IMF’s global growth forecast for 2026?
The IMF projects 3.0% global growth in 2026 and 3.4% in 2027, down from the 3.5% average recorded in 2024–25.
Why did the IMF cut its 2026 forecast?
The Middle East war raised energy prices and inflation while denting confidence. This drag is only partly offset by AI-driven demand in the global technology cycle.
How often does the IMF publish the World Economic Outlook?
Twice yearly as full reports (April and October), with shorter Updates in January and July.
Do the IMF and World Bank forecasts agree?
They differ by methodology. The IMF’s 3.0% for 2026 uses PPP weights; the World Bank’s 2.5% uses market exchange rates. The two headline numbers are not directly comparable.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Asian Stock Markets 2026: Japan, China, Pakistan & More

Mortgage Rates Today 2026: Full Rate Guide & Forecast

Beyond Paper Wealth: Unpacking Donald Trump’s Multibillion-Dollar Liquidity and Legal Crisis

Bitcoin & XRP 2026: Inside Crypto’s Institutional Era

Global Economy 2026: IMF Growth, AI Stocks & Market Risk

China’s Local Debt Race Against Time: Why Economists Demand Central Action Before the Deflation Window Closes

Money News: How to Protect Your Portfolio From Global Inflation

World Bank Projections: Emerging vs. Big Economies of Asia

IMF Reports 2026: What the Latest Data Means for the Global Economy

Singapore Stocks Outlook: A Safe Haven in the Asian Market?

China Stocks vs. Japan Stocks: Where Should You Invest in Late 2026?

VIX Index Explained: How to Trade Wall Street’s Fear Gauge Today

Commercial vs Residential Real Estate: Which Wins in 2026?

Presidential Stock Market Performance: How Trump’s Second Term Compares to History

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

BRICS+ Cross-Border Payments 2026: Interoperability Explained

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters

Leveraging Viral AI & Climate Hashtags for Brand Growth on X
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025