
Analysis
When Financial and Geopolitical Waves Collide: We Are Living in a ‘Barbell’ World Where International Threat Meets Technological Opportunity

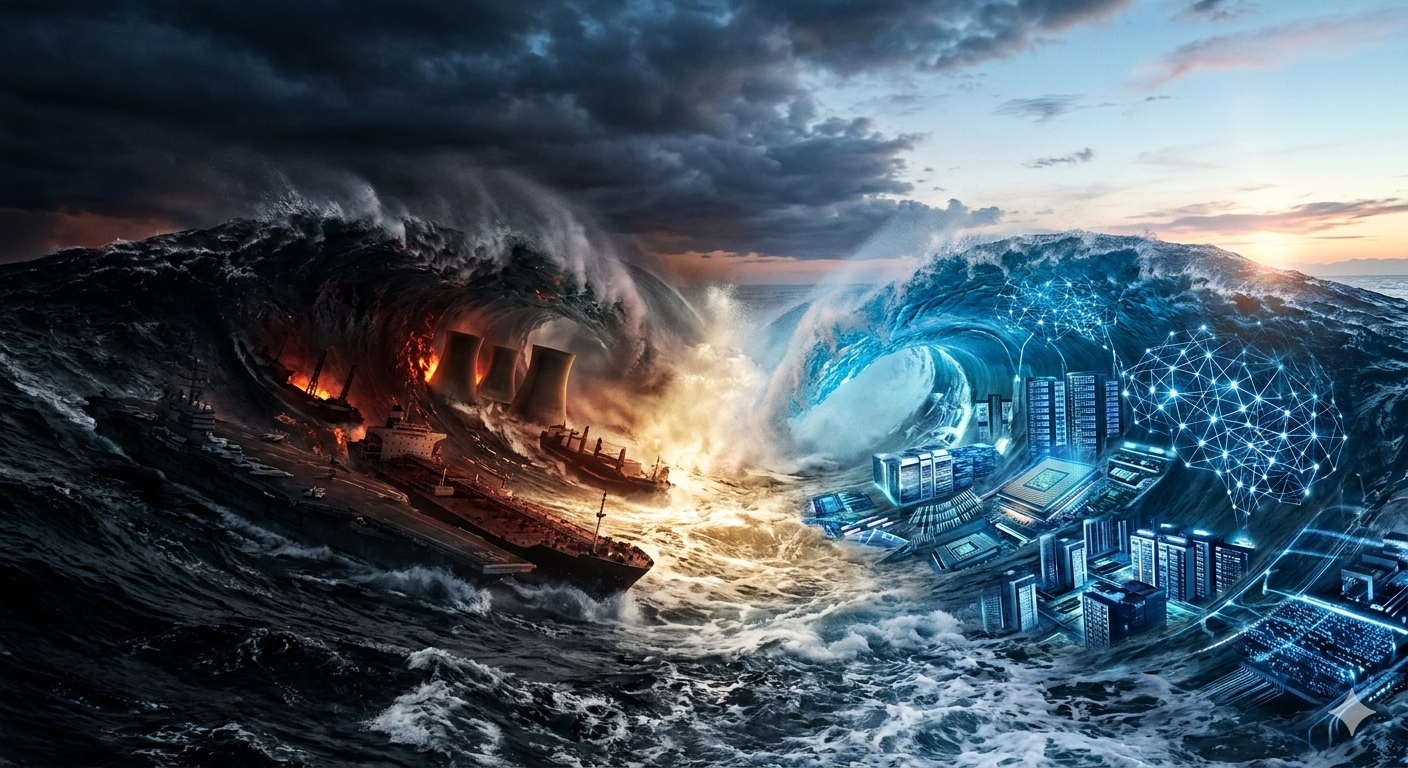
The Ocean Metaphor That Explains Everything Right Now
Picture two enormous waves, each born in a different ocean, each gathering force over years of invisible sub-surface pressure. The first is a geopolitical wave — dark, warm, and chaotic — driven by nuclear brinkmanship in Tehran, carrier fleets massing in the Strait of Hormuz, and a semiconductor cold war fought in export-control filings rather than trenches. The second wave is technological — cooler, brighter, almost luminescent — powered by $650 billion in AI capital expenditure, a once-in-a-century rewiring of computing infrastructure, and the earliest signs of genuine machine intelligence reshaping how entire economies function.
These are the moments when financial and geopolitical waves collide. Not a metaphor. A measurable, quantifiable event — visible in gold’s safe-haven surges, in oil’s volatility premium, in the divergence between defence stocks and software multiples. The collision zone is not some future horizon. It arrived on the morning of March 1, 2026, as smoke cleared over Iranian skies and data centres in Virginia drew more power than mid-sized nations.
Understanding this collision — and profiting from it, or at least surviving it — requires a new mental model. Scholars of risk call it the barbell world 2026: a structure in which the middle hollows out, and the extremes become the only places worth standing.
What Is the ‘Barbell World’? Taleb, Haldane, and the Death of the Middle
The barbell is Nassim Nicholas Taleb’s gift to investors: weight on both ends, nothing in the centre. In portfolio terms, it means pairing ultra-safe assets with highly speculative ones, abandoning the comfortable mediocrity of the middle. As contributing Financial Times editor and former Bank of England chief economist Andy Haldane has articulated in early 2026, this metaphor now describes the global economy itself — a barbell economy in which extreme geopolitical fragility at one end coexists with an extreme technological super-cycle at the other, with the “moderate, stable middle” of globalised, rules-based integration hollowing out at accelerating speed.
The barbell strategy geopolitics framework recognises something counterintuitive: the threats and the opportunities are not opposites. They are, in many ways, the same force refracted through different lenses. Semiconductor export controls drive AI chip nationalism — and chip nationalism turbocharges domestic AI investment. Iranian nuclear confrontation spikes oil prices — and oil-price spikes fund the sovereign wealth funds now pouring capital into data centres in Abu Dhabi and Riyadh. The barbell does not resolve the tension. It profits from it.
The IMF’s January 2026 World Economic Outlook captured the paradox in a single sentence: global growth remains “steady amid divergent forces,” with “headwinds from shifting trade policies offset by tailwinds from surging investment related to technology.” The headline number — 3.3% global growth for 2026 — masks a structural bifurcation that is, by now, impossible to ignore.
Wave 1: The Geopolitical Rupture
Iran, the Strait of Hormuz, and the Return of Great-Power Brinksmanship
As these words are written, the most consequential geopolitical confrontation since Russia’s 2022 invasion of Ukraine has just entered a new, dangerous phase. The 2026 Iran-United States crisis, years in gestation, reached its inflection point on February 28, when American and Israeli forces conducted strikes on Iranian nuclear infrastructure — the culmination of months of naval build-up, a domestic uprising that killed thousands of Iranian citizens, and a diplomatic dance in Geneva that ultimately could not bridge the gulf between Washington’s demand for full enrichment dismantlement and Tehran’s red lines.
The strategic and financial consequences are cascading in real time. ING Bank strategists had already warned that “the market will continue to price in a large risk premium” as long as military outcomes remained uncertain, with oil volatility serving as the transmission mechanism from the Strait of Hormuz to every fuel-dependent supply chain on earth. With the Strait handling roughly 20% of global oil flows, any sustained disruption is not an oil-market story — it is an inflation story, a shipping story, a sovereign-debt story for import-dependent emerging markets.
What makes 2026 different from previous Middle Eastern crises is the capital-flight dynamic. Iran’s deep economic fragility — compounded by a 20-day internet blackout, hyperinflationary collapse, and international isolation — has accelerated the flight of Iranian private capital toward Dubai, Istanbul, and Toronto. This is one tributary feeding into a broader pattern of geopolitical risks 2026 reshaping global capital flows. The Geopolitical Risk (GPR) Index, compiled by economists at the Federal Reserve, has registered multi-decade spikes in early 2026 not seen since the immediate aftermath of 9/11.
US-China Decoupling and the Silicon Curtain
The Iran shock does not exist in isolation. It is the loudest instrument in an orchestra of ruptures. The United States, under executive orders signed in January 2026, imposed a 25% tariff on Nvidia’s H200 and AMD’s MI325X AI processors under Section 232 national security authority — a seismic escalation of what researchers at the Semiconductor Industry Association have called the “Silicon Curtain.” Washington’s stated rationale is acute: the US currently manufactures only approximately 10% of the chips it requires domestically, making it, in the administration’s own words, “heavily reliant on foreign supply chains” in a way that “poses a significant economic and national security risk.”
The EU, meanwhile, designated Iran’s Islamic Revolutionary Guard Corps as a terrorist organisation on January 29, 2026 — a step Brussels had resisted for years — tightening a transatlantic security alignment that is simultaneously fracturing over trade, defence spending, and the terms of any post-Ukraine settlement. The Economist Intelligence Unit’s 2026 Risk Outlook flags EU-China “de-risking” as a slow-motion financial and geopolitical collision of its own: European manufacturers pulling semiconductor and rare-earth supply chains away from Chinese suppliers at significant near-term cost, hoping to avoid the kind of dependency that left Germany exposed when Russian gas was weaponised in 2022.
Add space militarisation — China’s deployment of inspector satellites capable of disabling orbital assets, the US Space Force’s accelerating budget — and the picture emerges of a world in which the infrastructure underpinning the global economy (shipping lanes, satellite communications, semiconductor supply chains, energy corridors) is being securitised faster than markets can reprice the risk.
Wave 2: The Technological Super-Cycle
AI Capex and the $650 Billion Signal
Against this darkness, a second signal pulses with near-blinding intensity. The four dominant hyperscalers — Alphabet, Amazon, Meta, and Microsoft — have collectively committed to capital expenditures exceeding $650 billion in 2026 alone, according to Bloomberg data. Amazon’s guidance alone — $200 billion — exceeds the annual capital investment of the entire US energy sector. Goldman Sachs Research estimates total hyperscaler capex from 2025 through 2027 will reach $1.15 trillion — more than double what was spent in the three years prior.
This is not a bubble signal, or not straightforwardly one. TSMC, the foundational manufacturer of advanced semiconductors, raised its 2026 capital expenditure guidance to an unprecedented $52–56 billion, with 70–80% directed at 2-nanometer node ramp-up — the technological frontier. ASML, sole producer of the High-NA EUV lithography machines that make those nodes possible, issued 2026 revenue guidance of €34–39 billion and watched its shares surge 7% on the news. These are not speculative bets. They are supply chains being built, atom by atom, to sustain an AI geopolitical volatility 2026 environment in which compute supremacy has become a national security asset.
The Intelligence Layer
What is being built with this capital matters as much as the scale. The transition underway is from AI as productivity tool to AI as autonomous economic agent — what industry insiders are calling “Agentic AI.” Legal discovery, financial auditing, intelligent logistics routing, molecular drug design: these are no longer experimental use cases. They are live deployments. The IMF’s January 2026 update explicitly cited “technology investment” as one of the primary forces offsetting trade policy headwinds — a remarkable acknowledgement, from an institution not known for technological optimism, that technological opportunity geopolitical threat dynamics are now macro-relevant at a sovereign level.
In shipping and logistics, the convergence is particularly striking. Intelligent vessel routing systems, now standard aboard the largest container fleets, are incorporating real-time geopolitical risk feeds — rerouting automatically around contested waters, repricing insurance dynamically as carrier deployments shift. The Red Sea disruption, which cost global supply chains an estimated $10 billion per month in additional routing costs during its 2023–24 peak, has become the template stress-test for every logistics algorithm now being trained on conflict-probability data.
The Collision Zone: Markets, Capital Flight, and Volatility
Gold, Oil, and the Barbell Portfolio
As someone who has advised central banks and institutional investors on crisis-era portfolio construction, I find the current market configuration both fascinating and vertiginous. The financial geopolitical collision is leaving fingerprints across every asset class. Gold has surged beyond $3,100 per troy ounce — a level that structural gold bulls have long predicted but that has arrived compressed in time by simultaneous central bank buying from emerging market sovereigns, Iranian capital flight, and a resurgence of the geopolitical risk premium that dominated the Cold War era. Morningstar’s portfolio managers describe this as “structural distrust in monetary policy pushing gold to new record highs” — a framing that gestures at something deeper than a crisis hedge.
Oil, meanwhile, is exhibiting the bifurcated volatility pattern characteristic of barbell world 2026 conditions: the spot price is elevated on supply-risk premiums while the forward curve reflects base-case demand moderation from Chinese economic slowdown and an OPEC+ consensus favouring gradual supply restoration. ING’s commodities strategy desk, quoted by CNBC, notes that “targeted and brief” military action may produce a short-lived spike, while a sustained conflict with active Strait of Hormuz disruption would keep prices elevated on supply risks indefinitely. Markets are pricing both scenarios simultaneously — hence the unusually wide options skew.
The 10-year US Treasury yield has climbed to 4.29%, partly on the “Warsh Shock” of the White House’s nomination of the hawkish Kevin Warsh as Federal Reserve Chair successor to Jerome Powell. At the same time, Nasdaq has retreated into negative territory for the year as investors rotate from capital-intensive AI infrastructure plays into industrials, financials, and energy — the “HALO trade” (Heavy Assets, Low Obsolescence) that is, in microcosm, a barbell in practice.
Winners and Losers: The Barbell Investment Playbook
Nations
Winners in the barbell economy are those positioned at the productive extremes: the United States (AI infrastructure, defence contracting, LNG exports as Middle East supply is disrupted), India (fastest-growing major economy at 6.3% per the IMF, semiconductor assembly buildout, demographic dividend), and the Gulf Arab states (petrodollar recycling into sovereign AI investment, geopolitical insulation from Iran-US conflict). Saudi Aramco’s $110 billion investment in AI and data-centre infrastructure — announced in partnership with NVIDIA in late 2025 — is the clearest illustration of how hydrocarbon windfalls from geopolitical risk are being reinvested in the technological opportunity that same geopolitical risk is helping to accelerate.
Losers are the trapped middles: European manufacturers caught between US tariff pressure and Chinese competition, unable to move decisively toward either extreme; emerging-market commodity importers who face the double blow of higher oil prices and tighter dollar financing conditions; and the “SaaS middle layer” of software companies that neither own the AI infrastructure nor the consumer applications that monetise it — a cohort that suffered an estimated $1.2 trillion in market value erosion in February 2026 alone as “seat compression” fears took hold.
The Critical Minerals Angle
The barbell strategy geopolitics of 2026 runs through the earth itself. Lithium, cobalt, gallium, germanium — the critical minerals that underpin both AI hardware and clean-energy infrastructure — are overwhelmingly concentrated in China, the DRC, and a handful of other states that have learned to treat resource access as a geopolitical instrument. China’s export controls on gallium and germanium, progressively tightened since 2023, are the resource-dimension equivalent of the semiconductor trade war: a slow chokepoint on Western technological ambition. Nations that control these supply chains — Australia, Canada, Chile, Morocco — are experiencing a quiet investment renaissance.
Travel, Mobility, and the Global Supply Chain Under Stress
For business travellers, cross-border investors, and the logistics professionals who keep the global supply chain in motion, the barbell world has become viscerally immediate. Air cargo routes have been repriced as overflights of Iranian airspace are suspended — adding 45–90 minutes to key Europe-Asia freight lanes and triggering the first meaningful spike in business-travel insurance premiums since the COVID-19 lockdowns. Business-travel management companies report a 34% increase in “geopolitical disruption” policy claims in Q1 2026, while luxury travel demand — concentrated in the Gulf, Singapore, and Switzerland — remains stubbornly resilient, a pattern consistent with the barbell: the premium end holds, the volume middle is squeezed.
Supply-chain rerouting is the structural story beneath the headline drama. The World Bank’s January 2026 Global Economic Prospects notes that “the 2020s are on track to be the weakest decade for global growth since the 1960s,” yet trade finance for alternative routing — through the Suez Cape route, through Central Asian rail corridors, through emerging East African port infrastructure — is growing at double-digit rates. Investors in port infrastructure, air cargo logistics, and specialised freight insurance are positioned at the productive extreme of the barbell, benefiting from the very disruptions that are costing importers.
Cross-border investment flows are similarly bifurcating: away from politically exposed middle-income economies toward either the safe haven (Singapore, Switzerland, UAE) or the frontier opportunity (India, Vietnam, Saudi Arabia). The comfortable middle ground of “globalised, stable, rules-based” investment — the default of the post-1990 era — is becoming increasingly difficult to find.
Policy Prescriptions for the Barbell Era
What Governments Must Do
The barbell economy is not, in itself, a policy choice — but the policy response to it is. Governments that navigate it well will do three things simultaneously.
First, they will invest at the technological extreme with the urgency the moment demands. The European Union’s delayed response to AI infrastructure investment — constrained by fiscal rules, regulatory caution, and a structural preference for horizontal competition policy over vertical industrial strategy — is already manifesting in a widening competitiveness gap. The IMF’s January 2026 World Economic Outlook is explicit: “technology investment, fiscal and monetary support, accommodative financial conditions, and private sector adaptability offset trade policy shifts.” The operative word is “and” — no single lever is sufficient. Europe has the fiscal space and the monetary conditions but has yet to mobilise the industrial strategy.
Second, they will build genuine supply chain diversification — not the reshoring rhetoric that substitutes political sloganeering for the hard, slow work of building alternative supplier relationships, securing critical mineral agreements, and investing in port and logistics infrastructure that makes alternative routes commercially viable. The nations that started this work in 2022, following Russia’s invasion, are three years ahead of those starting now.
Third, and most counterintuitively, they will invest in diplomatic infrastructure — the unglamorous apparatus of back-channel communication, multilateral institution maintenance, and conflict de-escalation that looks expensive in peacetime and priceless in crisis. The Geneva talks between the US and Iran — however they ultimately resolve — were enabled by Omani mediation capacity built over decades. That capacity is a form of geopolitical infrastructure as real as a data centre and harder to rebuild once lost.
The Economist’s Verdict
As someone who has spent two decades watching financial and geopolitical cycles intersect, the 2026 configuration is genuinely novel in one key respect: the speed of the collision. Previous instances of great-power competition, technological disruption, and financial volatility interacted over years or decades. The current cycle is operating on a quarterly cadence — a direct consequence of AI’s ability to compress decision timescales in both markets and military planning.
The World Bank Global Economic Prospects January 2026 offers a sober diagnostic: “global growth is facing another substantial headwind, emanating largely from an increase in trade tensions and heightened global policy uncertainty,” while simultaneously documenting the “surge in AI-related investment, particularly in the US” that kept 2025 growth 0.4 percentage points above forecast. The same report warns that “one in four developing economies had lower per capita incomes” than before the pandemic — a reminder that the barbell’s productive extremes are not universally accessible.
The AI geopolitical volatility 2026 dynamic poses a specific challenge to central bank credibility. The Federal Reserve’s mandate — stable prices, maximum employment — was calibrated for a world in which supply shocks were temporary and productivity growth was predictable. Neither condition holds. Oil supply shocks from Middle Eastern conflict are persistent in their uncertainty, not temporary. AI-driven productivity acceleration is real but uneven, concentrated in the capital-rich firms and nations that can afford the barbell’s technological extreme. The risk of monetary policy error — tightening into a geopolitical supply shock, or easing into an inflationary AI-investment boom — has rarely been higher.
The Middle Is Dead. The Extremes Are Alive.
There is something both clarifying and terrifying about living in a barbell world. The familiar topography of the post-Cold War international order — moderate integration, predictable multilateralism, gradual technological change — is gone. In its place: extreme geopolitical rupture coexisting with extreme technological transformation, and a middle ground that offers neither the safety of the barbell’s defensive end nor the returns of its offensive one.
The international threat meets technological opportunity paradox of 2026 is, ultimately, a resource allocation problem at civilisational scale. Every dollar that flows into a data centre instead of a weapons system is a bet that the technological wave will crest before the geopolitical one breaks. Every dollar flowing into gold instead of AI equity is the opposite bet. The tragedy — and the opportunity — is that both bets are simultaneously rational.
For investors, the playbook is uncomfortable but clear: build the barbell. Own the defensive extreme (gold, energy infrastructure, defence logistics, critical mineral producers, sovereign AI plays in the Gulf) and own the offensive extreme (AI infrastructure beneficiaries, semiconductor capital equipment, biotechnology powered by AI drug discovery). Exit the middle: undifferentiated SaaS, geopolitically exposed consumer brands in contested markets, anything whose value depends on the restoration of a stable, rules-based international order that is not coming back in this decade.
For policymakers, the imperative is starkly different: work to compress the barbell. Invest in the institutions, agreements, and infrastructure that rebuild some version of the productive middle — not as nostalgia for a world that no longer exists, but as the architecture of one that might. The waves have collided. The question is whether we build something new in the wreckage, or simply ride the extremes until one of them overwhelms us.
The middle is dead. The extremes are alive. Choose yours carefully.
Citations & Sources
- World Bank Global Economic Prospects, January 2026 — https://www.worldbank.org/en/news/press-release/2026/01/13/global-economic-prospects-january-2026-press-release
- IMF World Economic Outlook Update, January 2026 — https://www.imf.org/en/publications/weo/issues/2026/01/19/world-economic-outlook-update-january-2026
- Bloomberg: Big Tech $650B AI capex 2026 — https://www.bloomberg.com/news/articles/2026-02-06/how-much-is-big-tech-spending-on-ai-computing-a-staggering-650-billion-in-2026
- Goldman Sachs: AI Companies May Invest More Than $500B in 2026 — https://www.goldmansachs.com/insights/articles/why-ai-companies-may-invest-more-than-500-billion-in-2026
- CNBC: US-Iran Nuclear Talks, Trump Deadline, Oil Prices — https://www.cnbc.com/2026/02/25/us-iran-talks-nuclear-trump-oil-prices-war-conflict.html
- CNBC: US-Iran Talks Conclude, Oil Risk — https://www.cnbc.com/2026/02/27/us-iran-nuclear-talks-oil-middle-east.html
- Al Jazeera: Iran says US must drop excessive demands — https://www.aljazeera.com/news/2026/2/27/iran-says-us-must-drop-excessive-demands-in-nuclear-negotiations
- Bloomberg: US-Iran Nuclear Talks, Trump Deadline — https://www.bloomberg.com/news/articles/2026-02-26/us-iran-to-hold-nuclear-talks-as-trump-s-deal-deadline-looms
- Wikipedia: 2026 Iran–United States Crisis — https://en.wikipedia.org/wiki/2026_Iran%E2%80%93United_States_crisis
- PBS NewsHour: Iran Nuclear Timeline — https://www.pbs.org/newshour/world/a-timeline-of-tensions-over-irans-nuclear-program-as-talks-with-u-s-approach
- World Bank Global Economic Prospects Full Report — https://www.worldbank.org/en/publication/global-economic-prospects
- IMF WEO Update Full PDF, January 2026 — https://www.imf.org/-/media/files/publications/weo/2026/january/english/text.pdf
- TradingEconomics: World Bank 2026 GDP Forecast + AI Chip Tariffs — https://tradingeconomics.com/united-states/news/news/516773
- Morningstar: AI Arms Race Investment Landscape 2026 — https://global.morningstar.com/en-ca/markets/ai-arms-race-how-techs-capital-surge-will-reshape-investment-landscape-2026
- Yahoo Finance/CNBC: Big Tech $650B in 2026 — https://finance.yahoo.com/news/big-tech-set-to-spend-650-billion-in-2026-as-ai-investments-soar-163907630.html
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Global Supply Chain Vulnerabilities: From Eurasian Trade Corridors to Food Consumer Recalls

Why 5% U.S. Treasury Yields Signal a Global Market Regime Shift.

Federal Reserve Defies White House Pressure: Inside Trump’s Demand for Sub-1% Interest Rates After Historic 2026 Rate Hike

How Rising Interest Rates Impact Gig Economy Apps: DoorDash, Uber, and Urban Services

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

DoorDash Driver Payouts, Fee Structures, and Market Competition Analysis

OPINION:Breaking the 3.5% Growth Trap: How Pakistan Can Build a High-Productivity Export Economy

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

Asian Markets Analysis: Navigating Volatility in China, Japan, and Singapore Stocks

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Fed Rate Hike Projections vs. Trump’s Interest Rate Policy: What Global Markets Expect Next

Singapore Stocks: The Ultimate Safe Haven for Markets and Finance in 2026?

State Farm’s $5B Dividend 2026: Who Qualifies & Payout Dates

US-China Relations in Q3 2026: Trade Tariffs and Supply Chain Risks

SpaceX Starship Flight 14: First Orbital Attempt & Starlink V3 Launch Explained

Top 30 Stocks for Investment in PSX for Massive ROI in 2026

The 2026 Crypto Regulatory Shift: What It Means for Institutional Investors

AI Chip Stocks 2026: The Best Semiconductor Investments Beyond Marvell

AI-Powered Training: The Next Multi-Billion Dollar Ecosystem in Fitness

Tween Back-to-School Trends 2026: What’s Driving the $85B Season

10-Year Treasury Yield Hits 4.80%: What It Means for Rates & Portfolios

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

Shein Clothes Quality & Safety in 2026: What Lab Tests Show

Fidelity Investments Review 2026: SPAXX Yields & Zero-Fee Funds

MRVL Earnings 2026: Why Marvell Sank Despite Beating Estimates

China’s US$10.8 Billion Trade Shortcut: Why the Pinglu Canal Matters
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis7 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis7 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Analysis7 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Banks8 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Investment8 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy9 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy9 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025