
Banks
Bank of England AI Kill Switch vs Singapore MAS Agentic AI Rules

The Bank of England has, for the first time, publicly questioned whether its existing rulebook can contain the risks posed by autonomous artificial intelligence agents operating inside financial markets — a question that Singapore‘s Monetary Authority of Singapore (MAS) effectively answered months earlier with a formal agentic-AI risk toolkit built alongside two dozen banks and insurers. The contrast between a major Western regulator now sketching hypothetical “kill switches” and an Asian regulator already operationalizing agentic-AI governance illustrates how unevenly the world’s financial supervisors are adapting to the same technological shift.
Sarah Breeden, the Bank of England’s deputy governor for financial stability, told the European Central Bank’s Sintra forum that the financial system is evolving toward one that “operates more autonomously, at scale and speed,” and that relying on a human in the loop for every AI agent action is no longer realistic, according to the Bank of England’s published speech text. Her remarks mark a departure from the Bank’s long-standing position that existing, technology-agnostic frameworks were sufficient to supervise AI-driven finance.
What the Bank of England Is Actually Proposing
Breeden’s speech outlined a set of “mitigants” under active study rather than confirmed policy: market-wide circuit breakers or kill switches capable of halting trading if faulty AI models trigger a correlated meltdown, and “enhanced recovery” arrangements that would allow one bank to take over another’s core functions during a crisis. The Bank, working alongside Germany’s Bundesbank and the Bank for International Settlements, is running simulations of scenarios in which AI trading agents — trained on similar data and reacting to identical market signals — execute the same trades simultaneously, amplifying volatility precisely when markets are least able to absorb it.
The scale of the exposure is not hypothetical. A Cambridge Centre for Alternative Finance survey cited by Breeden found that 52% of finance firms are already deploying agentic AI in some capacity, according to coverage from Banking Exchange. Breeden also noted that AI capability, which doubled roughly every seven months in 2019, is now doubling closer to every four months — an acceleration she described as already exceeding policymakers’ expectations.
Unlike generative tools that respond to individual prompts, agentic AI is designed to complete multi-step tasks with limited human intervention — executing trades, initiating payments, and interacting with counterparty systems without requiring approval at each step. That autonomy is precisely what concerns the Bank: existing frameworks were built around human decision points that agentic systems are designed to bypass.
Singapore’s Head Start: Project MindForge
While London debates hypothetical guardrails, Singapore‘s MAS has already moved from consultation to implementation. In March 2026, MAS announced the conclusion of phase two of Project MindForge, publishing an AI Risk Management Toolkit developed in collaboration with a consortium of 24 banks, insurers, and capital markets firms, according to MAS’s official release. The toolkit’s centerpiece is an AI Risk Management Operationalisation Handbook that gives financial institutions practical guidance for managing risk across traditional AI, generative AI, and emerging agentic AI systems.
Notably, Singapore’s underlying supervisory guidelines — first proposed in a November 2025 consultation — explicitly instruct financial institutions to build human override and kill-switch capability directly into agentic systems from the outset, rather than retrofitting them after a crisis has demonstrated the need. Kenneth Gay, MAS’s Chief FinTech Officer, framed the toolkit’s release as a step toward ensuring the responsible adoption of AI across the industry, according to MAS’s release.
This is a materially different regulatory posture than the one described by Breeden. Where the Bank of England is still exploring whether guardrails are needed, MAS has already codified expectations around AI inventories, materiality-based risk assessments, board-level accountability, and lifecycle controls covering autonomous decision loops. The consultation period for MAS’s underlying guidelines closed on January 31, 2026, with institutions expected to comply within a 12-month transition window — placing full enforcement around early 2027, well ahead of any comparable UK framework currently under discussion.
Why the Divergence Matters for Global Capital Flows
The regulatory gap between Singapore and the UK is not merely academic. As global banks and asset managers build cross-border agentic AI systems — trading desks that operate across London, Singapore, and New York simultaneously — inconsistent supervisory expectations create genuine compliance friction. A trading agent built to Singapore’s MindForge standard, with embedded override capability and documented lifecycle controls, may already satisfy requirements that the Bank of England has not yet finalized, giving institutions with Singapore operations a practical head start in demonstrating AI governance maturity to global regulators.
This dynamic reinforces Singapore’s broader ambition to position itself as Asia’s trusted node for AI-era financial infrastructure. MAS has pursued a parallel, integration-led approach to tokenized finance through initiatives such as Project Guardian and the Global Layer One framework, a public-private collaboration involving the Bank of England, the Banque de France, and major global commercial banks. The convergence of these initiatives — agentic AI governance on one track, tokenized settlement infrastructure on another — suggests Singapore is deliberately building the regulatory scaffolding for a financial system in which autonomous agents and digital money coexist as standard infrastructure rather than experimental technology.
The Stakes for Financial Stability
Breeden’s own framing of the risk is instructive: the goal, she said, is ensuring that the next “technology surprise” does not become a test of financial stability. The Bank’s Financial Policy Committee is due to publish an updated assessment of AI-related financial stability risk on July 7, with Breeden noting that AI infrastructure investment, historically funded through large technology companies’ cash flows and equity, is increasingly reliant on debt financing in newer and more complex structures — a shift the Bank has already flagged as increasing the potential financial stability consequences of any sharp correction in AI-related asset prices.
For regulators everywhere, the practical question is no longer whether agentic AI will operate inside core financial infrastructure — the Cambridge survey data suggests that threshold has already been crossed — but whether supervisory frameworks, kill switches, and recovery protocols can be built and tested before the next AI-driven market stress event arrives rather than after it.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


For US homebuyers, the mortgage question in 2026 is about more than the direction of the next interest-rate announcement. The practical issue is whether the full cost of a home fits a household’s finances without depending on an uncertain future refinance.
Freddie Mac’s Primary Mortgage Market Survey reported a 7.40% average for a 30-year fixed mortgage on 8 October 2026, compared with 7.28% a week earlier. The 15-year average was 6.73%. These are weekly market benchmarks, not offers available to every applicant. Actual pricing depends on the borrower, property, loan structure and lender.
Earlier forecasts can now look optimistic because they were produced under different conditions. The right response is to compare current evidence with current costs, rather than assume that a predicted decline must eventually arrive on schedule.
Why the Federal Reserve does not set your mortgage rate
The Federal Reserve influences short-term financial conditions, but a long-term fixed mortgage is priced through a broader market. Investors consider expected inflation, future interest rates and the return available from other securities. Lenders also account for operating costs and the characteristics of the loan.
Mortgage rates can therefore move before a central bank announcement. If investors expect a decision, its likely effect may already be reflected in prices. Rates can even rise after an announcement that appears supportive if the accompanying outlook is less reassuring than expected.
Long-term bond yields are useful context, but they are not a complete mortgage calculator. The spread between those yields and mortgage pricing also changes. A borrower should avoid treating one Treasury-market headline as a precise prediction of the next lender quotation.
A forecast is different from an affordable offer
A national rate forecast can help explain the direction of market expectations. It cannot determine an individual applicant’s approved rate. Credit history, down payment, loan size, occupancy and other factors influence the quote.
Comparisons also become misleading when products differ. A low advertised rate may require upfront points. A shorter term may carry a lower rate but a much higher monthly payment. A variable-rate product may begin attractively while exposing the borrower to later changes.
The Consumer Financial Protection Bureau’s homebuying resources provide a useful starting point for understanding the borrowing process and comparing mortgage documents. For a real decision, written terms from lenders matter more than a promotional headline or a general market prediction.
What a one-percentage-point difference means
Consider an illustrative $300,000 loan repaid over 30 years at a fixed rate. At 6%, monthly principal and interest would be approximately $1,799. At 7%, the payment would be about $1,996. At 8%, it would be around $2,201.
These figures are calculated examples, not lender quotes. They exclude property taxes, insurance, mortgage insurance, homeowners’ association charges and maintenance. They nevertheless show why apparently small changes in rates matter to household cash flow.
The comparison also demonstrates the danger of shopping only by house price. Two buyers purchasing the same property at different rates can face substantially different monthly obligations. Conversely, a price reduction may offset part of a rate increase. The useful unit of comparison is the complete payment and cash requirement, not either variable in isolation.
The monthly payment is only the beginning
Ownership creates expenses that a principal-and-interest calculator does not capture. Taxes and insurance can change over time. Repairs arrive irregularly. A roof replacement or plumbing problem may not respect the timing of a household’s savings plan.
Closing costs also affect affordability. A borrower who uses nearly all available cash for the purchase may have a manageable scheduled payment but little room for disruption. That distinction matters when employment or other income is uncertain.
A practical budget should separate predictable monthly expenses from reserves for less frequent costs. It should also include the costs of moving and setting up the home. Furniture, utilities and immediate repairs are easy to overlook because they occur outside the mortgage contract, yet they can materially change the first year’s financial experience.
How to compare points and fees
Mortgage points involve paying an upfront amount in exchange for a particular rate arrangement. Whether that trade makes sense depends on the exact offer and how long the borrower expects to keep the loan.
Suppose two otherwise comparable offers differ by $3,000 in upfront cost and $75 in monthly principal and interest. A simple cash-flow comparison produces a 40-month break-even period. That is only an illustration: a full comparison would consider other fees, balances, tax treatment where relevant and the time value of money.
The main lesson is to connect upfront charges with the intended holding period. Someone expecting to sell or refinance soon faces a different calculation from someone planning to keep the same mortgage for many years. A lower rate is not automatically the least expensive overall offer.
Rate locks reduce one uncertainty
A rate lock can protect specified pricing for a defined period, subject to the agreement’s conditions. The details matter: expiry dates, extension charges and changes to the application can affect the result.
The Wall Street Journal’s recent reporting on rate locks describes borrowers seeking more protection as rates rise. That does not establish that the longest available lock is best for every buyer. Its value depends on the expected closing timeline and cost.
Before choosing, ask what happens if the purchase is delayed, whether any float-down feature exists, and which changes could alter the quoted terms. A clear written explanation is more useful than a verbal assurance that the rate is protected. Locking a rate also does not remove the need to complete underwriting and satisfy other conditions.
Refinancing later is an option, not a guarantee
The idea of buying now and refinancing after rates fall can be appealing. It remains conditional on several things: market rates must become attractive, the borrower must qualify, the property must meet relevant requirements, and the savings must justify the costs.
Income, credit history and home value can change. A lower national rate does not ensure an individual borrower will receive an economical offer. Refinancing can also extend the repayment period, reducing the monthly payment while changing the total interest paid over time.
A stronger affordability test asks whether the initial loan works if refinancing never becomes attractive. Potential future savings can then be treated as an additional benefit rather than the assumption holding the purchase together. This is particularly important for households already stretching their monthly budget.
Buying versus waiting requires more than a rate prediction
Waiting has possible benefits and costs. It may allow more savings, improved credit or a clearer employment outlook. It also means continuing to pay rent and accepting uncertainty about future home prices, supply and borrowing costs.
Buying has its own trade-offs. It can provide stability for someone planning a long stay, but it reduces flexibility and creates transaction costs if plans change. A purchase motivated primarily by fear of missing out may not fit the household’s actual needs.
Compare realistic scenarios rather than one ideal outcome. What if rates remain near current levels? What if the desired home becomes cheaper but financing becomes more expensive? What if a job change requires relocation? A decision that remains workable across several plausible outcomes is less dependent on successful market timing.
What to watch next
The most relevant indicators include inflation data, long-term bond yields, credit conditions and lender competition. Housing supply also matters: lower mortgage rates would not automatically make homes affordable if prices rose enough to offset the financing improvement.
Update comparisons using the same loan amount, term, lock period and fee assumptions. Record the date of each quote because market conditions can change quickly. If one offer appears dramatically cheaper, identify the reason before treating it as an equivalent product.
Mortgage rates in 2026 remain a major affordability constraint, but forecasting them is only part of the decision. The more dependable approach is to compare complete offers, protect a realistic cash reserve and purchase only within a budget that works under the loan’s actual terms. The calculations here are educational examples rather than personalised mortgage advice.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Mortgage rates near 7% change the refinance math. Learn how to calculate your break-even point, weigh closing costs, and decide if refinancing still pays.
Key Takeaways
- Freddie Mac’s weekly average for a 30-year fixed mortgage reached 7.28% for the week ending October 1, 2026, up from 6.00% in early March.
- Refinancing pays off only when monthly savings recover closing costs within the years you plan to stay in the home.
- Use this formula: total closing costs ÷ monthly savings = months to break even.
- Closing costs commonly run 2% to 6% of the loan amount, so a $300,000 refinance could cost $6,000 to $18,000.
- A lower rate is not automatically a better deal. Term length, cash-out amounts, and how long you stay all change the answer.
Search Intent Summary
Most people searching for refinancing want to answer one question: “Will refinancing save me money, and when?” This guide gives you the calculation, the current rate context, and the questions to ask before you sign.
Where Mortgage Rates Stand Right Now
The rate environment has shifted sharply in 2026. Freddie Mac’s Primary Mortgage Market Survey, which averages rates for well-qualified borrowers on conventional loans, showed the 30-year fixed at 6.00% in early March. By September, rates had moved above 6.7%, and the survey put the 30-year at 7.28% for the week ending October 1.
That matters because many homeowners who refinanced in 2020 or 2021 locked in rates well below 4%. Those borrowers have little reason to refinance today. Others who bought in 2024 or 2025 may have hoped for a drop that has not arrived.
Rates set weekly averages, but your offer depends on your credit score, loan-to-value ratio, and loan type. Freddie Mac’s survey describes a strong borrower profile, so your actual quote may differ. The Federal Reserve Economic Data (FRED) series for the 30-year rate is useful if you want to track the long-run trend yourself.
Calculating Whether Refinancing Makes Sense
The core calculation is simple, and most lenders will give you the inputs.
Step 1: Add up your closing costs. These include lender origination fees, appraisal, title insurance, recording fees, and sometimes prepaid interest and escrow deposits. The Consumer Financial Protection Bureau’s Loan Estimate form lists each charge, and you should compare these forms from at least three lenders.
Step 2: Find your monthly savings. Subtract your new principal-and-interest payment from your current one. Don’t count changes to taxes or insurance, since those would apply either way.
Step 3: Divide. Closing costs divided by monthly savings gives your break-even point in months.
Here is a hypothetical example. Suppose your closing costs are $6,000 and your new payment is $250 lower each month. Dividing gives 24 months. If you plan to stay for ten years, you keep roughly $24,000 in savings beyond the break-even point, minus any interest you pay on a new loan term.
Now consider the reverse. If you expect to sell in two years, that same refinance produces almost no net benefit.
The Hidden Variables Most Guides Skip
Many refinance decisions go wrong because the monthly payment is the only number people compare. Several other factors matter.
Restarting the clock. If you were 8 years into a 30-year loan and refinance into another 30-year loan, you lower the payment but add years of interest. Shortening the term to 15 or 20 years can raise the payment while cutting total interest sharply. Choose the term based on your total cost, not just the monthly figure.
Rolling costs into the loan. No-closing-cost refinances are not free. The lender either charges a higher rate or adds fees to your balance. Adding fees to principal raises the amount you owe and pushes your break-even point later. Compare the two options side by side.
Cash-out refinancing. Taking equity out in cash raises your balance and usually your rate. The money may be useful for home improvements, but it turns a rate decision into a debt decision. Be honest about what the cash will fund.
Your time horizon. A refinance that takes four or five years to break even can still be a good move if you expect to stay for a decade. The Georgia state housing team’s refinancing guidance puts it plainly: you need to recover costs while you still own the home.
Comparing Your Options
| Scenario | Closing Costs | Monthly Savings | Break-Even | Works If You Plan To Stay |
|---|---|---|---|---|
| Rate-and-term, same term | $6,000 | $250 | 24 months | 2+ years |
| Shorter term (30 to 15 years) | $6,000 | $0 to -$100 | Not a savings play | Stays cheaper overall |
| No-closing-cost refi | $0 upfront | $250 | Depends on rate increase | Under 3 years |
| Cash-out | $6,000 | Varies | Often not a savings play | Only if cash has clear value |
The table shows why one number never settles the question. A shorter-term refinance can raise the monthly payment while still saving thousands in interest.
Practical Strategy Before You Apply
Start by pulling your current loan statement and checking the interest rate, remaining balance, and remaining term. Then request Loan Estimates from at least three lenders on the same day. Quotes that arrive on different days can differ because rates move daily.
Ask each lender for the exact closing cost total and the rate for each term option. Run the break-even math on each one. If the difference between offers is small, the lender’s service and speed matter more.
Check your credit before you apply. A higher score can lower your rate enough to change the break-even point. Pay down revolving balances if you can do so cheaply, and avoid opening new credit lines during the process.
Watch the Thursday Freddie Mac release, but treat it as a trend signal rather than a quote. Your lender’s daily rate is what you can lock.
Future Outlook
Nobody can reliably predict where rates go next. The Federal Reserve’s decisions, Treasury yields, and inflation data all feed into mortgage pricing. Waiting for a drop has a cost too, because a delayed refinance means fewer months of savings. The better question is whether the numbers work at today’s rate for the years you plan to stay.
Frequently Asked Questions
Is it worth refinancing when rates are above 7%?
It depends on your current rate. If your existing loan is at 6% or above, a refinance at today’s rates usually won’t save money. If your current rate is well above the market, run the break-even calculation before deciding. Staying in your home for a long time can still make a higher-rate refinance worthwhile, but only if the savings justify it.
How much do refinancing closing costs usually run?
Expect roughly 2% to 6% of your loan amount, according to Bankrate’s refinancing guide. On a $300,000 loan, that works out to about $6,000 to $18,000. Lenders vary, and some fees can be negotiated.
How do I calculate my refinance break-even point?
Divide your total closing costs by your monthly payment savings. For example, $6,000 in costs and $250 in monthly savings gives a 24-month break-even point. If you plan to move before that date, refinancing may cost you money.
Should I choose a shorter loan term when refinancing?
A shorter term usually reduces total interest but raises the monthly payment. It fits best if you can afford the higher payment without strain. A longer term lowers the monthly payment but increases the lifetime interest you pay, so compare total costs, not just the monthly figure.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
AI
Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power
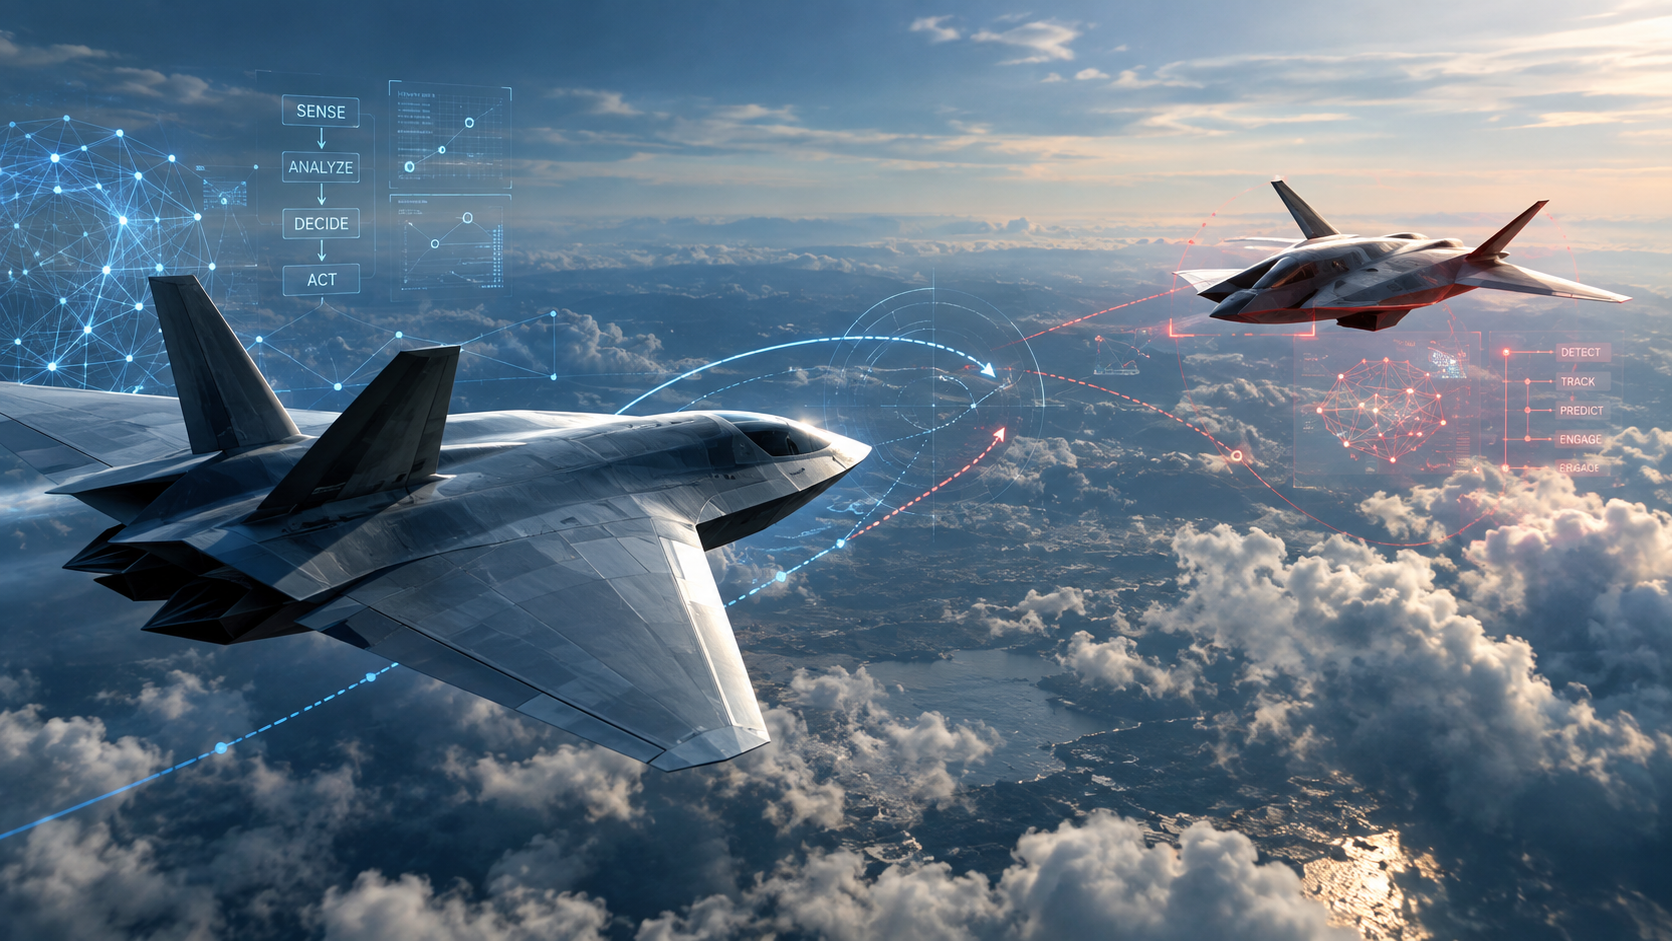
The military balance of power across the Indo-Pacific is undergoing a fundamental transformation. As both the United States and China transition artificial intelligence from simulator environments to front-line fighter jets, the primary threat of accidental military escalation in international airspace is shifting from human pilot miscalculation to machine learning error.
While much of the diplomatic discourse surrounding military AI focuses on nuclear command and strategic autonomy, the most immediate danger lies in tactical air intercepts over contested waters like the South China Sea and the Taiwan Strait. Without clear, bilateral rules of engagement (RoE) specifically tailored for autonomous aircraft, a routine encounter between uncrewed combat air vehicles (UCAVs) could trigger a rapid, unintended escalation ladder that human command structures cannot arrest in time.
The Dawn of Mach-Speed Autonomy
The race to field autonomous combat aircraft is no longer theoretical; it is an operational priority for both Washington and Beijing.
Under the U.S. Air Force’s Collaborative Combat Aircraft (CCA) initiative, the Pentagon plans to field at least 1,000 AI-enabled “loyal wingmen”—uncrewed aircraft designed to fly alongside crewed platforms like the F-35 and Next Generation Air Dominance (NGAD) fighters. Experiments conducted under the DARPA Air Combat Evolution (ACE) program have already demonstrated that AI agents can successfully outmaneuver human pilots in visual-range dogfights, adapting to tactical dynamic shifts at sub-second speeds. Details outlined by the U.S. Department of Defense emphasize the imperative of responsible autonomy, yet tactical real-time execution in contested zones remains a major wild card.
Concurrently, the People’s Liberation Army Air Force (PLAAF) is aggressively pursuing its own uncrewed platforms. Chinese defense contractors have showcased platforms such as the FH-97A and the WZ-8, designed to perform autonomous reconnaissance, electronic warfare, and forward-line air-to-air suppression. Research published by the RAND Corporation indicates that Beijing views military AI integration as a “force multiplier” capable of offsetting traditional U.S. power projection advantages in the First Island Chain.
The Escalation Trap: Why AI Changes Air-to-Air Tactics
In conventional intercept scenarios involving piloted aircraft—such as a Chinese J-16 intercepting a U.S. RC-135—human pilots operate under established visual signals, radio frequencies, and the multilateral Code for Unplanned Encounters at Sea (CUES). When a human pilot assesses intent, they rely on visual cues, physical distance, and tactical behavior to gauge aggression versus standard shadowing.
When two autonomous or semi-autonomous systems intercept one another, these human buffers disappear:
- Compression of the OODA Loop: Machine-learning algorithms operate on microsecond decision cycles. If an autonomous aircraft interprets a standard radar lock, electronic jamming pod, or evasive banking maneuver by an opposing drone as an incoming attack vector, its predictive neural networks may trigger defensive or pre-emptive maneuvers instantly.
- The “Black Box” Problem: Deep neural networks operate via complex pattern matching rather than deterministic logic trees. As noted in security studies by the Center for Strategic and International Studies (CSIS), predicting how an edge-deployed military AI model will respond to unpredictable real-world inputs (such as spoofed GPS or unexpected weather events) remains an unsolved challenge.
- Loss of Signaling Nuance: Human pilots can de-escalate a confrontation by rocking wings, pulling back on throttles, or establishing radio contact. Autonomous systems lack standard mechanisms to convey ambiguous or non-hostile intent to an opposing nation’s algorithmic system.
+-----------------------------------------------------------------------+
|                       THE ACCIDENTAL ESCALATION LOOP                 |
|                                                                       |
|   [U.S. Autonomous CCA]  <--- Sensor Query --->  [PLA Autonomous UCAV]|
|            |                                            |             |
|   Algorithm perceives                               Algorithm perceives|
|   evasive banking as hostile                         radar lock as     |
|   targeting signal                                  pre-emptive strike|
|            |                                            |             |
|            v                                            v             |
|   Automated Countermeasure                       Automated Deficit    |
|   Deployments (Chaff/Jamming)                    Tracking & Target    |
|            |                                     Acquisition          |
|            +-------------------+------------------------+             |
|                                |                                      |
|                                v                                      |
|             HUMAN COMMANDERS NOTIFIED POST-DISCHARGE                  |
|             (Escalation threshold crossed in <3 seconds)             |
+-----------------------------------------------------------------------+
The Existing Governance Vacuum
Multilateral efforts to regulate military AI have made modest progress, but they fall short of addressing tactical air intercepts.
The Responsible AI in the Military Domain (REAIM) summits and the U.S.-led Declaration on Responsible Military Use of Artificial Intelligence and Autonomy offer general principles regarding human oversight, command structure integrity, and rigorous testing. Similarly, diplomatic analysis published by the Brookings Institution highlights that high-level bilateral summits between Washington and Beijing have opened initial dialogues on AI risk reduction.
However, these broad political declarations lack operational mechanics. They do not define:
- What constitutes a hostile act by an autonomous platform in international airspace.
- What standardized electronic signals an uncrewed system must broadcast to declare peaceful transit.
- How machine-to-machine communications should function during an unintended proximity event.
Without concrete, technical protocols embedded directly into aircraft software suites, high-level political commitments will fail the moment silicon meets silicon over the Western Pacific.
A Four-Pillar Blueprint for U.S.-China AI Air Engagement
To mitigate the risk of an unintended confrontation, defense officials and technical experts from the United States and China must establish a dedicated Autonomous Air De-confliction Framework. Analysts writing in Foreign Affairs repeatedly note that arms control in the digital age requires technical solutions co-designed alongside strategic policy.
1. Hard-Coded Strategic Fail-Safes
Both nations should agree to hard-code deterministic “red lines” into autonomous flight control systems that cannot be overridden by machine-learning models. These include hard caps on maximum speed increases during close encounters, mandatory stand-off distances when intercepting uncrewed platforms, and automated weapon system lock-outs unless explicit human authority is transmitted.
2. Standardized Autonomous Identification Friend-or-Foe (A-IFF)
Similar to transponder systems used in commercial aviation, military uncrewed systems operating in international airspace should transmit a standardized, cryptographically signed “Autonomous Platform Intent” signal. This broadcast would inform nearby air units of the flight’s mission state, autonomous level (e.g., tethered to human lead vs. fully autonomous), and non-aggressive flight path vector.
3. Machine-to-Machine De-confliction Hotlines
Traditional voice-based communication links—such as the U.S.-China Defense Telephone Link—are too slow to manage algorithmic interactions. A modern de-confliction protocol requires an automated, low-latency data channel between U.S. Indo-Pacific Command and the PLA Eastern/Southern Theater Commands. This channel would automatically ping human operators the instant two opposing autonomous platforms enter a designated safety perimeter.
4. Joint Synthetic Simulation and Stress-Testing
Before deploying advanced autonomous fighters at scale, defense laboratories from both nations should participate in joint track-sharing and simulated scenario stress-tests. By running algorithmic models against each other in virtual environments, both sides can identify edge cases where neural networks misinterpret opponent maneuvers, allowing software engineers to patch systemic vulnerabilities before they manifest in real air combat.
The Imperative of Algorithmic Restraint
The integration of artificial intelligence into air warfare is an inevitable reality driven by strategic competition and technological momentum. However, autonomy without governance introduces an unacceptable level of operational risk.
If Washington and Beijing fail to establish clear rules of engagement for autonomous combat jets today, they risk allowing computer algorithms to dictate the timing and conditions of a major-power conflict tomorrow. Establishing guardrails for AI air power is not a sign of military weakness—it is a mandatory requirement for strategic stability in the 21st century.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Hormuz Diesel Shortage: Why Crude Oil Recovery Isn’t Enough

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Jeff Bezos Three-Day Workweek View: What He Really Said

Celeste Frozen Pizza Discontinued: What Conagra Confirmed

US–China Critical Minerals Competition: Why a Trade Deal Cannot Fix Every Supply Risk

Oil Price Outlook 2026: How Supply Risks Reach Fuel Bills, Inflation and Business Costs

AI in Business 2026: Why Faster Employees Do Not Automatically Mean Higher Profits

Mortgage Rates in 2026: Why They Remain High and How to Compare the True Cost

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Global Economic Outlook 2026: Growth, Inflation and Risks

Trump–Putin Diesel Deal: Why Zelensky Is Angry and What It Means for Fuel Prices

Anthropic Draws the Line: Why Claude’s New Usage Policy Explicitly Bans ‘Cruel Behavior’ Toward AI

Ynon Kreiz & Mattel’s Digital Transformation: Franchise Strategy and Financial Growth

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

World’s Largest Economies: Ranking the Top Global Powers

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

Stock Market Today: Dow Climbs 500 Points as Markets Shake Off Inflation Jitters
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025