
Analysis
Commerzbank UniCredit Takeover Bid: Why Shareholders Said No

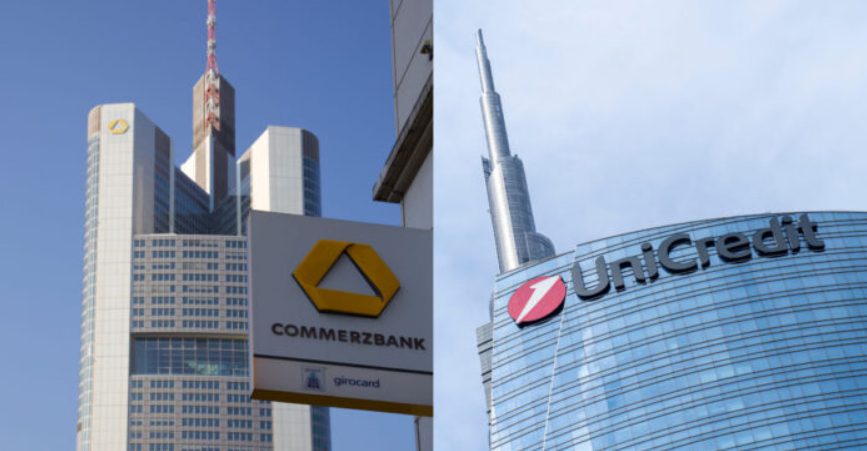
Bettina Orlopp stepped onto the stage in Wiesbaden on 20 May 2026 to something rare in German banking: applause. Shareholders rose to cheer the chief executive as she dismissed UniCredit’s €35 billion takeover bid as an opportunistic attempt to seize control without paying for it. The moment crystallised a rebellion. Despite months of pressure from Italy’s second-largest lender, only 0.02% of Commerzbank shares had been tendered by 19 May. The hostile offer wasn’t merely unwelcome. It was, in the words of the board’s formal reasoned statement, financially inadequate and strategically hollow.
The battle for Commerzbank is unfolding at a precarious moment for European finance. The European Central Bank has long championed cross-border consolidation to deepen the banking union and equip continental lenders to compete with American megabanks. Yet the Franco-German axis that once drove integration has frayed, and national capitals have rediscovered their appetite for financial sovereignty.
Commerzbank, which finances roughly 30% of German foreign trade and serves 24,000 corporate client groups, sits at the intersection of these colliding forces. A spokesman for Germany’s Finance Ministry reiterated Berlin’s position in early May: a “hostile, aggressive takeover” of a systemically important bank would be unacceptable. The statement was not diplomatic nuance. It was a warning shot. Behind it lies a harder reality. Germany’s federal government still holds a 12.7% stake in Commerzbank, a residual from the €18.2 billion bailout during the 2008 financial crisis, and has openly considered raising that holding to secure a blocking position. What looks like a standard M&A contest is, in fact, a stress test for whether European banking union can survive national interest.
Inside the Commerzbank UniCredit Takeover Bid
On 5 May 2026, UniCredit published its offer document for the Commerzbank UniCredit takeover bid, proposing an exchange ratio of 0.485 new UniCredit shares for each Commerzbank share. Based on the three-month volume-weighted average price determined by BaFin, the implied value stood at €34.56 per share by mid-May. That figure sat almost 5% below Commerzbank’s closing price of €36.48 on 15 May, and well under the €41.50 median target price assigned by independent equity analysts. The Economist promptly labelled it a “lowball bid,” noting that the terms valued the whole bank at roughly €35 billion ($41 billion) yet offered more than an 8% discount to the market price prevailing the day before publication. It was, by any conventional standard, an opportunistic opening gambit rather than a generous proposal.
Commerzbank’s board needed less than two weeks to reach a verdict. On 18 May, the Board of Managing Directors and the Supervisory Board issued a formal reasoned statement pursuant to Section 27 of Germany’s Securities Acquisition and Takeover Act. Their conclusion was unambiguous: shareholders should reject the offer. The document argued that UniCredit’s plan was “neither sound nor convincing,” that synergy assumptions were described by UniCredit itself as “speculative,” and that the proposed dismantling of Commerzbank’s international network would gut its ability to finance the export-oriented German Mittelstand. Jens Weidmann, chairman of the Supervisory Board and former Bundesbank president, warned that the share-exchange structure meant Commerzbank shareholders who accepted would simply inherit the execution risk as future UniCredit owners.
The market listened. By 19 May, a negligible 0.02% of shares had been tendered. At the AGM in Wiesbaden the following day, Orlopp strode onto the stage to applause. She told the hall that UniCredit’s bid was “an attempt to take over Commerzbank at a price that does not properly reflect the fundamental value and potential of our bank.” Employees held signs reading “UniCredit Go Away!” The message was unmistakable. This was not a target negotiating for a better price. It was a management team and workforce that genuinely believed the standalone future was brighter than the combined one.
Why the Commerzbank Momentum 2030 Strategy Makes UniCredit’s Math Look Shaky
The analytical case against UniCredit’s bid rests on a simple proposition: Commerzbank is already delivering what Orcel promises, and it is doing so without the trauma of a merger. On 8 May, the bank unveiled its updated “Momentum 2030” roadmap alongside first-quarter results that beat expectations. Operating profit rose 11% year-on-year to a record €1.4 billion. Net profit climbed 9% to €913 million. Revenues reached €3.2 billion, driven by a 9% surge in net commission income to an all-time high of €1.1 billion. The cost-income ratio improved three percentage points to 53%. These were not projections. They were settled facts from the first three months of 2026.
Why is Commerzbank rejecting UniCredit’s offer? The board argues the bid provides no adequate premium and lacks a credible plan. The implied €34.56 value falls short of the €36.48 share price and far below analyst targets near €41.50. The board believes its standalone “Momentum 2030” strategy creates greater value with lower execution risk than UniCredit’s vague restructuring proposal.
Building on this momentum, Commerzbank raised its full-year 2026 net profit target to at least €3.4 billion, up from the previous “more than €3.2 billion.” By 2028, it now expects a net return on tangible equity of around 17%, rising to roughly 21% by 2030. Net profit is targeted to reach €4.6 billion in 2028 and €5.9 billion in 2030, while revenues should grow from €13.2 billion this year to €16.8 billion by decade’s end. That implies a 6% compound annual growth rate. The bank also plans to invest €600 million in artificial intelligence through 2030, expecting €500 million in annual efficiency gains from 2030 onwards and a 10% redeployment of capacity toward customer-facing roles. Perhaps most tellingly for shareholders, Commerzbank intends to return approximately half of its current market capitalisation through dividends and buybacks by 2030, maintaining a 100% payout ratio until its CET 1 ratio reaches 13.5%. The record dividend of €1.10 per share approved at the AGM is the down payment on that promise.
The picture is more complicated for UniCredit. Its own outside-in analysis, published in April as “Commerzbank Unlocked,” projected that Commerzbank could reach a net profit of €5.1 billion by 2028 under UniCredit’s stewardship. Yet Commerzbank’s board dismissed that presentation as “highly aggressive” and hostile, arguing it inaccurately assessed revenue losses, IT integration costs, and headcount reductions. The Banker reported that the board viewed the plan as undermining “the fundamental trust essential to the banking business.” When a target’s management disputes not just your price but your industrial logic, the bidder has a credibility problem that no exchange ratio can fix.
What a Hostile Takeover Would Mean for German Banking and European M&A
If UniCredit somehow prevails, the consequences would ripple far beyond Frankfurt and Milan. Commerzbank is not a generic mid-tier lender. It is the leading bank for Germany’s Corporate Clients business, accounting for approximately 30% of the country’s foreign trade financing. Its international network spans more than 40 countries, and its Polish subsidiary mBank serves around 6 million customers. Dismantling that network, as UniCredit’s plan reportedly envisages, would weaken the financial plumbing that supports Germany’s export-driven Mittelstand. That is why Berlin has drawn a line. The Finance Ministry’s spokesman did not mince words in early May: a hostile takeover of a systemically relevant bank was “unacceptable.”
The political defence may harden further. Berlin retains a 12.7% stake and has shown no inclination to sell into UniCredit’s offer. A blocking position would transform that residual crisis-era holding into an active defensive weapon. It would also signal that Germany, once the architect of European banking union, now views cross-border consolidation through the lens of national interest first and supranational efficiency second. That shift carries risks for the entire continent. If every major bank merger triggers a race between capitals to protect domestic champions, the ECB’s vision of a unified European banking market will remain a theoretical construct.
For Commerzbank’s 40,000-plus employees, the immediate risk is more tangible. The works council has warned that UniCredit’s integration could eliminate thousands of jobs. Commerzbank’s own analysis cited substantial headcount reductions envisaged by UniCredit, complex IT integration, and revenue losses from overlaps in the Corporate Clients business. Either scenario would represent a seismic shock to Frankfurt’s labour market and to the bank’s internal culture. The transformation agreement already negotiated with employee representatives for Commerzbank’s standalone 3,000-position reduction looks modest by comparison, and it was concluded with social safeguards and redeployment programmes that a hostile acquirer would have little incentive to honour.
Regulatory timelines add another layer of uncertainty. Even if acceptance levels rose, UniCredit has stated that closing would not occur before the first half of 2027, pending ECB, BaFin, and competition clearances. The offer document cites 2 July 2027 as the outer limit. In an environment where interest rates, geopolitics, and German electoral politics could shift dramatically within 14 months, that is an eternity. Shareholders who accept today would lock in an illiquid, uncertain consideration denominated in UniCredit shares, exposed to every twitch in Italian sovereign risk and eurozone sentiment. The structure alone is a deterrent.
UniCredit’s Counter: Scale, Synergy, and the Case for European Consolidation
To steel-man UniCredit’s position is to start from a premise that Commerzbank’s board rejects but many institutional investors once accepted: that the German bank had underperformed for years before Orlopp’s turnaround. Andrea Orcel, UniCredit’s chief executive and a veteran of Goldman Sachs, Merrill Lynch, and UBS, has pursued this deal since 2024. He argues that Commerzbank’s “Momentum” plan is merely catching up to where the bank should already be, and that true competitiveness requires scale. UniCredit’s April presentation projected that Commerzbank could achieve a net return on tangible equity above 19% by 2028 and roughly 23% by 2030 under its ownership, figures that exceed even Commerzbank’s newly raised standalone targets. The industrial logic is not frivolous. Combining Commerzbank with UniCredit’s existing German subsidiary, HypoVereinsbank, would create the country’s largest lender by certain measures, surpassing Deutsche Bank in selected corporate segments. Cost synergies from overlapping IT systems, branch networks, and back-office functions could, in theory, reach billions of euros. And Orcel is correct that European banking remains fragmented relative to the American market, where JPMorgan Chase alone commands a market capitalisation greater than the sum of Europe’s top five lenders. The ECB, under Christine Lagarde, has consistently welcomed cross-border tie-ups as a means to deepen the banking union and improve global competitiveness. There is also a shareholder-level argument. UniCredit’s own stock has re-rated strongly since Orcel took the helm, and the bank has returned billions through buybacks and dividends. Investors who trust his execution record might reasonably conclude that he could do for Commerzbank what he has done for his own institution. Yet the offer’s structure betrays a lack of conviction. By proposing a bare-minimum exchange ratio with no cash alternative and no clarity on ultimate control, UniCredit is asking Commerzbank shareholders to swap a surging standalone equity story for a speculative merger script with a 14-month settlement horizon. It’s a lot to ask for no premium.
The stand-off between Commerzbank and UniCredit is therefore not merely a quarrel over price. It is a contest between two competing visions of European finance. One vision, championed by Orcel and the ECB, holds that scale and cross-border integration are prerequisites for global relevance. The other, articulated by Orlopp and backed by a surprisingly assertive Berlin, insists that a profitable, systemically important national champion can deliver superior returns to shareholders while preserving strategic autonomy. Both sides can marshal data to their cause. Yet the burden of proof in any takeover lies with the bidder, and UniCredit has so far failed to meet it. Its offer is underwater, its acceptance rate is negligible, and its strategic plan has been dismissed by the target’s board as speculative. What follows, however, is unlikely to be graceful retreat. Orcel has spent two years and billions of euros building a stake that now approaches 30%. He didn’t come this far to fold. The summer of 2026 will determine whether European banking union advances by force or stalls on the barricades of national interest. For now, the yellow flag of Commerzbank still flies over Wiesbad
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

IREN Stock in 2026: AI Cloud Growth, Bitcoin Transition and the Risks Investors Miss

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Peso Mexicano vs Dólar Estadounidense: A Practical USD/MXN Guide for October 2026

Is the Stock Market Open on Columbus Day 2026? NYSE, Nasdaq and Bonds Explained

Concert Ticket Prices in 2026: Dynamic Pricing, Fees and How to Buy Safely

High-Yield Savings Accounts in 2026: How to Compare APY Without Chasing a Headline

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Social Security 2027 COLA Announcement: Date, Formula and What Retirees Should Check

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025