
Policy
Boomers vs Young Adults: Why the Net Worth Gap Is More Complicated Than It Looks

It is tempting to compare baby boomers’ wealth with that of today’s young adults and declare one generation successful and another left behind. But the numbers can tell very different stories depending on whether the measure is total wealth, median household net worth, age-adjusted wealth or access to housing. A fair comparison needs to show all four.
The Federal Reserve’s Distributional Financial Accounts track aggregate household wealth by generation and other categories. These accounts are valuable for understanding where assets sit in the economy, but aggregate ownership is not the same as the balance sheet of a typical person. A large generation approaching retirement has had decades longer to accumulate homes, retirement assets and business interests.
Total wealth is not typical wealth
Suppose a group of older households collectively owns far more financial assets than a group of younger households. That fact alone does not show that every older household is comfortable or that every younger household is struggling. Averages and aggregates can be distorted by a small number of wealthy families. Median net worth—the household exactly in the middle of a distribution—often answers the everyday reader’s question more directly.
Comparisons should also disclose whether they use individuals or households, and whether households are grouped by the age of the primary respondent. A multi-generational household cannot be cleanly assigned to one age cohort without a convention.
The housing split is central
A recent discussion of Federal Reserve survey data in Investopedia highlights a particularly striking difference within households in their 30s: owners accumulated equity while nonowners experienced a much weaker wealth picture. This is a reminder that the most consequential divide may exist inside a generation, not only between two generations.
Homeownership can build wealth through principal repayment and capital appreciation, but owners also face maintenance, taxes, interest costs and concentration risk. Renters may invest financial savings instead, although high rents can limit their capacity to do so. Good analysis avoids treating homeownership as an unconditional guarantee of prosperity.
The time-period trap
Boomers bought homes, entered workplaces and invested under very different combinations of interest rates, tuition costs, wages and asset valuations. Young adults today face a different set of trade-offs. Comparing a 65-year-old’s assets with a 25-year-old’s assets naturally produces a gap even if economic opportunity were unchanged. A better test compares people at similar ages across historical periods, ideally adjusting for inflation and household composition.
Even that test is imperfect. Retirement systems have changed, defined-benefit pensions are valued differently from personal retirement accounts, and life expectancy alters the amount of saving required. A headline that simply says one generation has multiples more wealth will miss those structural differences.
A practical framework for young households
Net worth equals assets minus liabilities. The first priority is to track both categories consistently rather than become discouraged by a national wealth total that includes billionaire fortunes. A household can improve its position by reducing high-cost debt, maintaining emergency liquidity, contributing to tax-advantaged retirement accounts where appropriate, and choosing housing costs that leave room for saving.
Investment choices depend on horizon and risk tolerance. Someone saving for a deposit in two years faces a different trade-off from someone investing for retirement over 30 years. Short-term market returns should not dictate the financial plan. Nor should social-media comparisons to much older households.
The public-policy question
The intergenerational wealth debate ultimately concerns affordability and access. Housing supply, student debt, real wage growth, employer retirement coverage and inherited wealth shape opportunity. Policies may help one part of the young population while leaving another behind. An effective analysis asks who benefits, who bears the cost, and whether a measure expands long-run asset-building capacity.
The strongest conclusion is that cohort averages are useful warning lights, not a complete social diagnosis. Age matters; so do geography, family resources, education, homeownership and the ability to recover from financial shocks.
A concrete example of why the metric changes the headline
Imagine one group with ten households: nine have modest retirement savings while one owns a large business. Their average wealth could be high even though the typical household has little financial cushion. In another group, many people own modest homes but few are exceptionally rich. The groups might reverse places depending on whether the journalist reports the mean, median or total assets. The same caution applies to inflation: a nominal gain can partly reflect higher asset prices rather than improved purchasing power. A useful generational comparison should therefore show the measure, age range, survey year, household definition and inflation adjustment in the chart subtitle. Without those details, the most eye-catching generational wealth ranking can be the least informative.
Frequently asked questions
Are boomers wealthier than Gen Z?
In aggregate, older cohorts generally control more accumulated wealth. That is not equivalent to saying every boomer is wealthier than every Gen Z adult, or that the cohorts have had equal time to save.
What is the best number to compare?
Use inflation-adjusted median household net worth for similar age groups and years, alongside homeownership and debt measures.
Can young adults close the gap?
Personal saving helps, but housing affordability, incomes, access to benefits and broader economic conditions also matter.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Social Security
Social Security 2027 COLA Announcement: Date, Formula and What Retirees Should Check
The 2027 Social Security cost-of-living adjustment has not been officially announced as of October 12, 2026. This analysis is based on information available at the research cutoff; verify developing prices, schedules and rules before publication.
The 2027 Social Security cost-of-living adjustment has not been officially announced as of October 12, 2026. The Bureau of Labor Statistics plans to release September inflation figures on October 14, supplying the final monthly input needed for the third-quarter calculation. Social Security says it will announce the next COLA in October. Avoid websites that state a projected percentage as though it were a confirmed benefit increase. Sources: Social Security Administration and SSA COLA announcement summary.
The important context competitors can overlook
The adjustment compares the July-to-September average of the CPI-W with the corresponding average in the prior base period, then rounds the percentage increase to one decimal place. It is not based simply on September year-over-year headline CPI. The confirmed 2026 COLA was 2.8%, which is an historical reference, not the 2027 outcome. Even once the percentage is announced, Medicare deductions, withholding and individual benefit amounts can make net deposits differ from a headline example. For primary-source checks and current reporting, see Social Security Administration and Bureau of Labor Statistics calendar. The key distinction is pre-announcement accuracy; translate formula into household budget.
A practical way to use this information
Bookmark the SSA COLA page rather than a social post. After the announcement, multiply your existing gross monthly amount by 1 plus the new rate and round only as the agency requires for your benefit. Compare that estimate with your official SSA notice and any Medicare premiums before adjusting a monthly spending plan. A $2,000 base and a hypothetical 3% adjustment would mean $60 more gross per month; 3% here is only an illustration, not a forecast.
How a COLA percentage changes a monthly check
The arithmetic is useful only once the official COLA is known. The examples below are hypothetical gross increases, not predictions and not net deposits.
| Monthly benefit before adjustment | Hypothetical 2% raise | Hypothetical 3% raise | Hypothetical 4% raise |
|---|---|---|---|
| $1,500 | $30 | $45 | $60 |
| $2,000 | $40 | $60 | $80 |
| $2,500 | $50 | $75 | $100 |
After the agency announces the figure, replace the illustrative columns with the actual rate. Avoid treating the BLS September release date as a promise of an identically timed SSA announcement. The agency itself controls publication of its benefit tables and notices.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Has the 2027 COLA been announced?
No official 2027 percentage was available in the SSA material checked on October 12, 2026.
When will new benefits arrive?
The COLA is effective for December benefits generally paid in January; SSI has its own payment timing.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Social Security
Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?
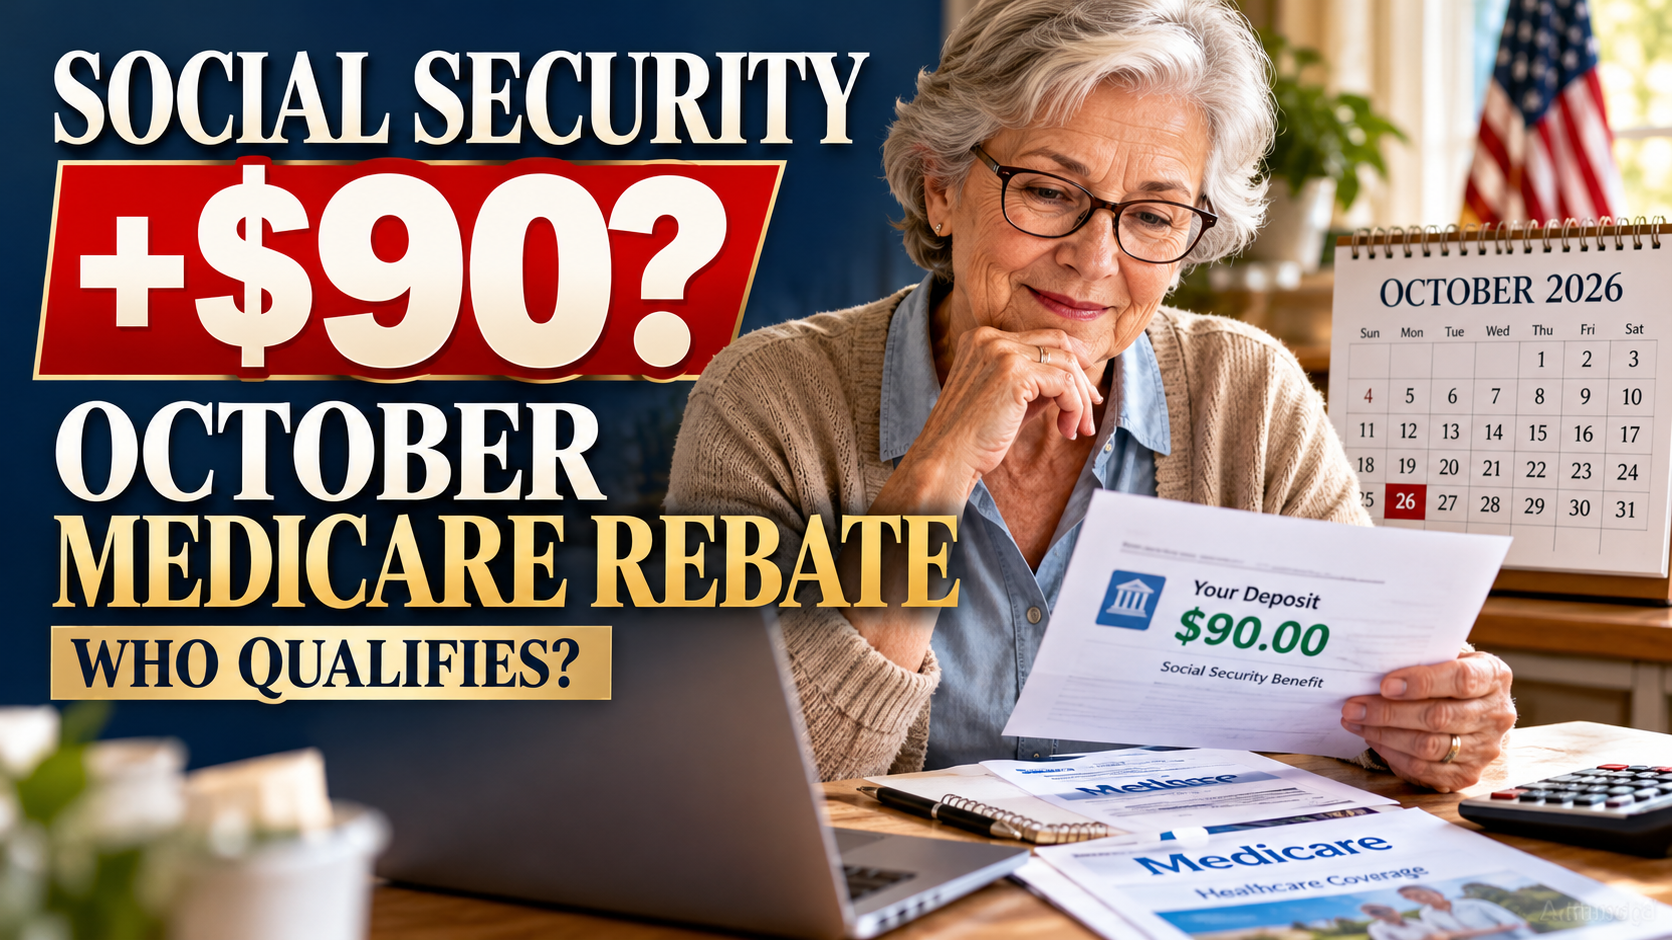
Millions of Americans are seeing, or expecting, an extra $90 payment connected to the Social Security Administration this October. The reason is a one-time Medicare Part B premium rebate from the Medicare Improvement Fund, not an across-the-board monthly increase in Social Security retirement benefits. The Centers for Medicare & Medicaid Services (CMS) says an estimated 20.8 million eligible beneficiaries will receive one $90 payment in October 2026. Most direct deposits were expected on or around October 8, with paper checks arriving later in the month.
Key takeaways:
- The $90 payment is a one-time rebate, not a new monthly Social Security benefit.
- It is limited to specific Original Medicare Part B enrollees; not everyone who receives Social Security qualifies.
- CMS identifies Medicaid premium assistance, income-related premium adjustments and Medicare Advantage enrollment as exclusions.
- Eligibility questions go to 1-800-MEDICARE; CMS directs people to contact Social Security about payment status beginning October 15, 2026.
What is the $90 Social Security deposit?
The federal government announced the $90 rebate to help eligible people offset Medicare Part B premium costs. Part B generally covers physician and other outpatient medical services. For many retirees, Part B premiums are deducted from monthly Social Security payments, which explains why the rebate may be described informally as an “extra Social Security deposit.”
That language can mislead readers. The Social Security Administration is involved in distribution, but the policy is a Medicare premium rebate funded through the Medicare Improvement Fund. It should not be confused with Supplemental Security Income (SSI), the Social Security cost-of-living adjustment (COLA) or an extra monthly pension check.
According to CMS’s October 3 fact sheet, eligible beneficiaries normally do not need to apply separately to receive the payment. The White House announced the program on October 2. The source of the funding and the timing ahead of November’s midterm elections have also generated political debate, as covered by Associated Press. Political discussion should not obscure the practical payment rules.
Who qualifies for the $90 Medicare rebate?
The CMS FAQ states that the payment is for approximately 20.8 million people enrolled in Original Medicare Part B, residing in the United States and meeting the agency’s premium-assistance and income-related adjustment conditions. CMS says beneficiaries enrolled in Medicare Advantage are not eligible. People whose Part B premiums are paid with Medicaid assistance and people paying an Income-Related Monthly Adjustment Amount (IRMAA) are also excluded under the published guidance.
Use this screening table as an explanation, not a substitute for an official eligibility determination:
| Situation | What the published CMS guidance indicates |
|---|---|
| Original Medicare Part B; U.S. resident; no listed exclusion | Potentially eligible for one $90 rebate |
| Medicare Advantage enrollee | Not eligible under CMS’s October FAQ |
| Medicaid pays Part B premium | Excluded |
| Pays IRMAA income-related Part B surcharge | Excluded |
| Receives Social Security but is not enrolled in qualifying Part B | Social Security receipt alone does not qualify |
| Lives outside the United States | Does not meet the stated U.S. residency criterion |
This table necessarily simplifies individual circumstances. People with mixed coverage, recent enrollment changes or disputed premium status should check directly with Medicare at 1-800-633-4227.
Why so many Medicare beneficiaries do not qualify
Medicare has different coverage routes. Some beneficiaries use Original Medicare with Part A and Part B; others receive benefits through Medicare Advantage plans administered by private insurers. Some low-income beneficiaries receive Medicaid assistance with their Part B premiums. Higher-income enrollees may pay IRMAA surcharges. The new rebate targets only the narrower group specified by CMS, not the entire Medicare population.
This distinction helps explain CBS News reporting about why many older Americans received the deposit while tens of millions did not. Lack of a payment does not automatically indicate a government error or missed Social Security benefit.
When will the $90 be deposited?
CMS’s schedule says most eligible beneficiaries should receive a direct deposit on or around October 8, 2026. Others should receive paper checks issued by the U.S. Treasury later in October. That wording describes a general rollout rather than an individual promise that every bank account will show money on the same day.
The federal guidance says eligible mailed-check recipients may see a description along the lines of a Medicare Improvement Fund payment offsetting the October premium. A letter or email explaining the rebate may arrive around mid-October. Notification correspondence is not itself a condition for payment.
What if October 8 passed and there is no deposit?
Do not assume you are entitled to a missing deposit until eligibility is established. First, check that you have qualifying Original Medicare Part B coverage and are not in an excluded category. Then inspect your bank history for an independently verifiable federal payment. If a mailed check is expected, allow for the stated later-in-October schedule.
For eligibility, CMS directs beneficiaries to 1-800-MEDICARE (1-800-633-4227). For payment status, CMS directs beneficiaries to the Social Security Administration at 1-800-772-1213 beginning October 15, 2026. These divisions of responsibility are unusually important: calling the right agency with the right question may prevent repeated transfers or misleading social-media advice. CMS official FAQ.
Is the $90 payment monthly or recurring?
No. CMS describes one rebate in October 2026. It is not a new recurring $90 monthly add-on. A person who receives the payment should not automatically add $90 to every future month’s household budget.
This also is not the same as the 2026 Social Security cost-of-living adjustment. The Social Security Administration says 2026 benefits received a 2.8% COLA, beginning with applicable January benefit payments. That annual adjustment follows a separate calculation and timeline. The Medicare rebate and the COLA operate under different rules, even when both affect a retiree’s bank balance.
| Feature | October $90 rebate | Social Security COLA |
|---|---|---|
| Purpose | One-time Medicare Part B premium offset | Annual benefit adjustment linked to inflation |
| Amount | $90 for an eligible person | Varies by individual benefit amount |
| Frequency | Once, per CMS announcement | Adjustment to ongoing benefits |
| Eligibility | Specific Original Medicare Part B group | Social Security/SSI entitlement rules |
| Source to verify | CMS Medicare Improvement Fund FAQ | SSA COLA page |
Is the rebate a scam?
The rebate itself is real and documented on a federal government website. That does not mean every unsolicited call, text message, social post or website about claiming it is legitimate. Be wary of anyone asking for a processing fee, bank password or verification code to unlock a $90 payment.
Because CMS describes automatic distribution, a message directing you to pay a fee or submit sensitive information through an unknown link should raise immediate concern. Instead, navigate independently to CMS.gov or SSA.gov or call the published numbers. Do not trust a phone number copied from a suspicious text.
How much difference can $90 make?
For a beneficiary facing recurring medical and living expenses, $90 can offer modest immediate relief. But its financial impact needs perspective: a one-time offset does not permanently reduce the future monthly Part B bill, cover all out-of-pocket healthcare costs or guarantee lower premiums in subsequent years.
Associated Press coverage notes that the payment is being distributed in a politically charged period. Supporters frame it as direct affordability relief. Critics question whether a one-off payment meaningfully changes long-term healthcare costs. Both policy debates are separate from the factual question of whether an eligible beneficiary should receive $90.
Frequently asked questions
Why did Social Security send me $90?
If you qualify, it is likely the one-time Medicare Improvement Fund premium rebate. Confirm the entry with official records rather than relying solely on the bank description.
Do all retirees receive the $90?
No. CMS limits eligibility to a specific group of Original Medicare Part B enrollees and lists several exclusions.
Is the payment related to the 2026 COLA?
No. The 2026 COLA is a separate ongoing benefit adjustment; the $90 rebate is one-time.
Are Medicare Advantage members eligible?
No, according to CMS’s October 3 FAQ.
What if I receive both Medicare and Medicaid?
If Medicaid pays your Part B premium, the CMS guidance says you are excluded. Confirm individual circumstances through Medicare.
When should I call if payment is missing?
CMS directs beneficiaries to Social Security about payment status beginning October 15; call Medicare for eligibility questions.
Do married couples get $180?
If both individuals independently meet the federal eligibility rules, each could qualify for a separate $90 rebate. Marriage alone does not create an additional payment.
Bottom line
The extra $90 is real, but the phrase “Social Security bonus” is misleading. It is a single, targeted Medicare Part B rebate scheduled for October 2026. Check your coverage type, understand the exclusions and use official Medicare or SSA channels for unresolved questions. Avoid anyone charging a fee to unlock the payment.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
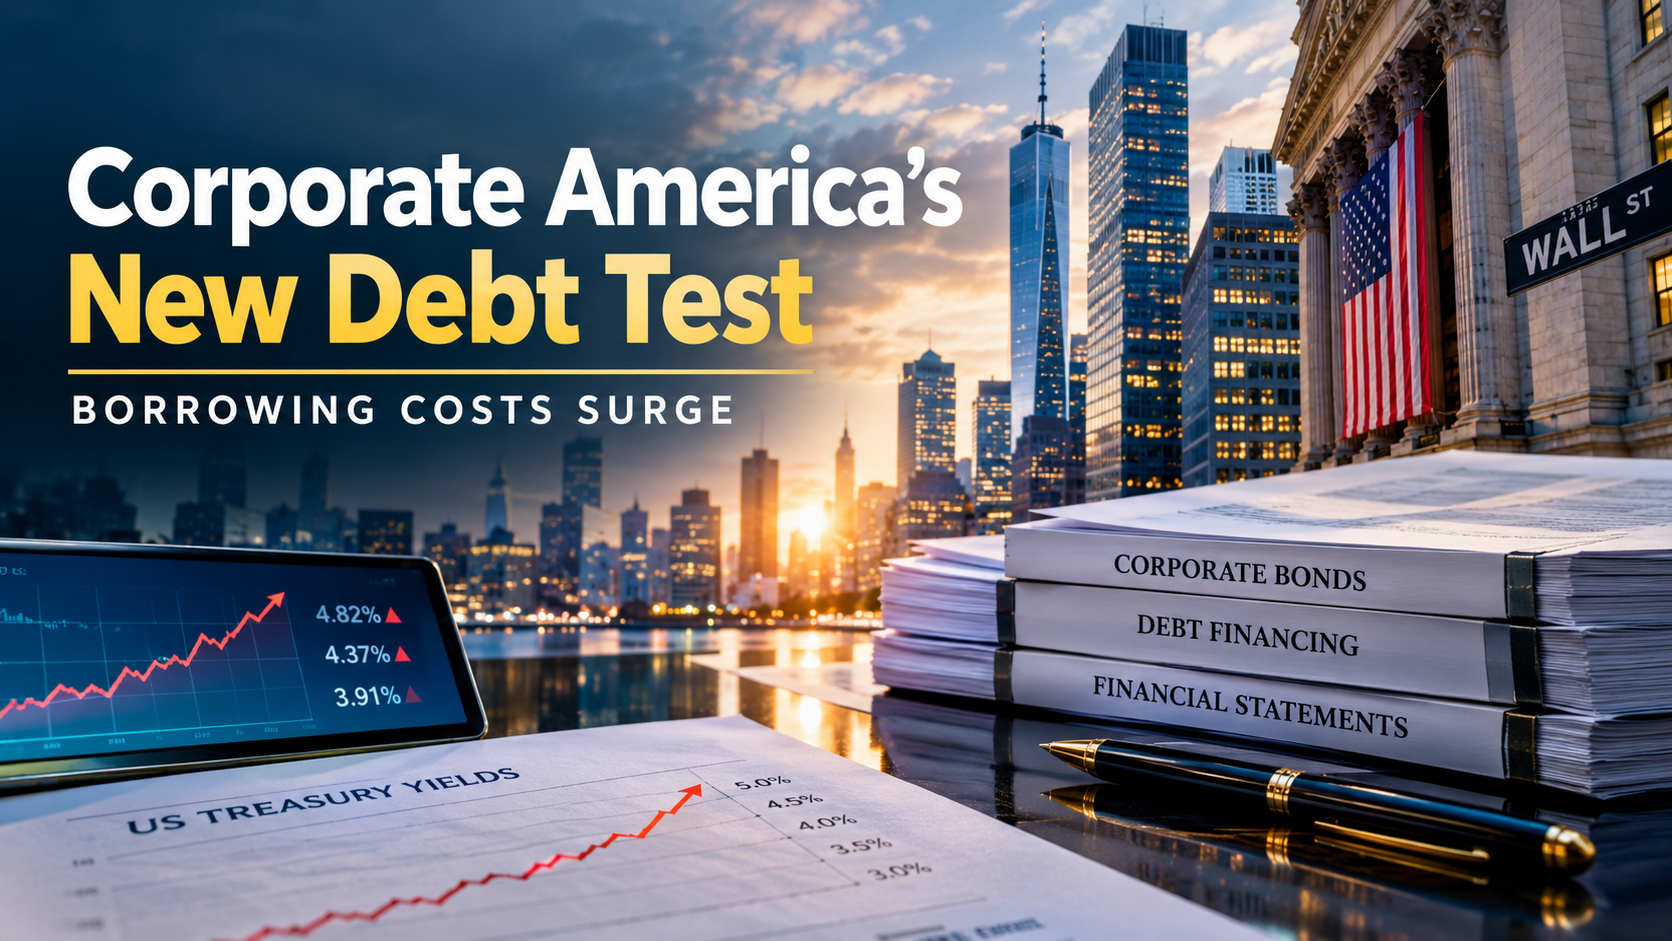
US Treasury yields have climbed to multi-year highs, pushing corporate financing costs higher and creating a growing refinancing challenge for American companies. The immediate pressure is concentrated among weaker borrowers, but a prolonged high-rate environment could eventually affect investment, mergers, buybacks and economic growth across corporate America.
The US bond market has entered a more difficult phase for corporate borrowers.
A sharp rise in Treasury yields is increasingly feeding into the cost of corporate debt, forcing companies to reconsider when and how they borrow. The impact is most severe for highly leveraged and lower-rated businesses, but even investment-grade companies are facing a more expensive capital market than they enjoyed during the ultra-low-rate era of the early 2020s.
The issue is no longer simply whether the Federal Reserve raises or cuts short-term interest rates. The bigger question for corporate America is how long long-term borrowing costs remain elevated.
That distinction matters because companies refinancing debt today are replacing old financing obtained at substantially lower rates with new debt priced in a very different market.
The Treasury market is setting a tougher price for corporate debt
The starting point is the US government bond market.
The 10-year Treasury yield has climbed to levels not seen in more than two decades, increasing the baseline rate against which much of the corporate bond market is priced. Recent market reporting has put the 10-year yield above 5%, with investors demanding greater compensation for holding long-duration government debt.
The Federal Reserve has warned that higher interest rates can increase debt-servicing costs for businesses with substantial leverage and upcoming refinancing requirements. The central bank has also noted that the corporate sector entered 2026 with relatively strong investment-grade credit quality, meaning the current environment should not automatically be interpreted as an economy-wide credit crisis.
That distinction is crucial.
The problem is increasingly concentrated in companies that have some combination of high leverage, weak cash flow, floating-rate liabilities or large amounts of debt coming due.
Federal Reserve financial-stability analysis supports the view that corporate credit vulnerabilities remain uneven rather than universal.
Why refinancing is becoming the central risk
Many companies borrowed heavily when interest rates were exceptionally low.
As those bonds mature, companies must either repay the debt from existing cash, refinance it at prevailing rates, sell assets, raise equity or reduce spending.
The refinancing arithmetic can be painful.
Suppose a company borrowed $10 billion at an average interest rate of 3%. Its annual interest bill would be approximately $300 million.
If that debt has to be refinanced at 6%, the annual interest expense rises to approximately $600 million.
The company has not borrowed another dollar, yet its annual financing burden has doubled.
That is why refinancing can become a hidden earnings shock.
Reuters estimates that approximately $4.3 trillion of US non-financial corporate bonds will mature between 2027 and 2031. Annual maturities are expected to rise from roughly $572 billion in 2027 to approximately $1.03 trillion in 2030.
This creates what investors increasingly describe as a corporate refinancing wall.
The weakest companies are feeling the pressure first
The deterioration is not evenly distributed.
Companies with investment-grade balance sheets can generally access capital markets more easily and often have diversified sources of funding.
Highly leveraged companies have fewer options.
According to the Financial Times, borrowing costs for companies rated CCC or lower have risen to approximately 17%, while their risk premium has reached about 12 percentage points.
That level of financing can fundamentally change corporate decision-making.
A project that looked profitable when money cost 5% may no longer make economic sense when financing costs move substantially higher.
This can lead companies to postpone:
- acquisitions;
- share buybacks;
- expansion projects;
- capital expenditure;
- hiring;
- new factories;
- technology investments;
- refinancing transactions.
The consequences can therefore spread beyond bond investors into the real economy.
Corporate America is not facing one uniform debt crisis
One of the most important nuances missing from many discussions about higher borrowing costs is that corporate America is highly divided.
At one end are highly profitable technology companies and other large investment-grade borrowers with enormous cash flows and strong access to capital markets.
At the other are highly leveraged companies whose earnings leave relatively little room to absorb a major increase in interest expense.
The Federal Reserve’s 2026 Financial Stability Report found that investment-grade corporate credit quality remained robust, although some riskier firms, particularly those dependent on private credit, were experiencing greater debt-servicing challenges.
That suggests the current environment is better described as a credit-selection problem than a generalized corporate solvency crisis.
The longer yields remain elevated, however, the greater the probability that today’s refinancing pressure becomes tomorrow’s default problem.
The corporate bond market is already sending signals
Market pricing provides an important window into this transition.
FRED data show Moody’s seasoned Baa corporate bond yield at approximately 6.73% on October 1, 2026. The Baa spread over the 10-year Treasury was about 1.49 percentage points at the beginning of October.
This distinction is important.
Corporate borrowing costs consist broadly of two components:
Treasury yield + corporate credit spread = corporate borrowing yield
The Treasury component compensates investors for the time value of money and government interest-rate risk.
The credit spread compensates investors for taking corporate credit risk.
When both rise simultaneously, companies experience a much more powerful increase in financing costs.
So far, much of the pressure has come from the Treasury side, although credit spreads for weaker borrowers have also widened substantially.
Paramount’s enormous financing illustrates the new reality
The Paramount Skydance transaction provides a particularly useful case study.
Paramount disclosed plans for tens of billions of dollars of debt financing connected with its acquisition of Warner Bros. Discovery. Its SEC filings show that the transaction involved substantial debt commitments, including a large bridge financing facility that was expected to be replaced or reduced through permanent financing.
The transaction demonstrates a broader challenge facing corporate finance teams.
When financing costs are uncertain, companies increasingly have to think about:
How much should we borrow?
For how long?
At what fixed rate?
How much floating-rate exposure should we accept?
Should we refinance now or wait?
Can the acquisition generate enough additional cash flow to justify the higher financing expense?
Those questions become especially important for highly leveraged mergers and acquisitions.
Why companies are shortening maturities
One logical response to high long-term interest rates is to avoid locking in today’s expensive financing for decades.
Companies may therefore prefer shorter maturities.
The strategy has an obvious advantage: if rates fall later, the company can refinance at a lower cost.
But it also creates another risk.
Shorter maturities mean more refinancing requirements in the future.
If interest rates remain high, companies could find themselves repeatedly refinancing debt at elevated rates.
That creates a difficult trade-off between paying more today for long-term certainty and accepting refinancing risk in exchange for shorter-term flexibility.
AI is creating an important exception
One of the most interesting features of the current credit market is the enormous borrowing associated with artificial intelligence infrastructure.
Technology companies are spending unprecedented amounts on data centres, chips, networking infrastructure and electricity capacity.
The Financial Times has reported estimates that hyperscalers could borrow around $1 trillion through 2030 to support AI infrastructure expansion.
For these companies, the calculation is different.
If management believes that failing to invest in AI infrastructure would result in losing a strategic position, higher financing costs may be treated as the price of maintaining competitive advantage.
This creates a strange two-speed corporate credit market.
AI-related investment can remain aggressive while other companies cut capital spending.
That divergence could become one of the defining characteristics of the next phase of the US corporate bond market.
The refinancing wall could become an earnings problem
The most important transmission mechanism is straightforward:
Higher Treasury yields → higher corporate borrowing costs → higher interest expense → lower free cash flow → reduced investment or weaker credit quality.
For companies with strong margins, the increase may be manageable.
For companies operating with thin margins, it can be decisive.
Consider a company generating $1 billion in annual operating cash flow and paying $300 million in interest.
If refinancing raises annual interest expense to $500 million, the company’s interest burden consumes a much larger share of its cash flow.
Management then has fewer resources available for investment, acquisitions, dividends and buybacks.
If revenues simultaneously weaken, the problem becomes more serious.
Could this trigger a wave of corporate defaults?
Not necessarily.
The Federal Reserve’s earlier 2026 assessment showed that corporate bond issuance remained strong and investment-grade credit quality was generally solid.
That provides an important cushion.
Large corporations have also had years to prepare for higher rates by extending maturities and locking in fixed-rate financing.
But the risk is asymmetric.
A stable economy can allow heavily indebted companies to refinance successfully.
A combination of high interest rates, slowing economic growth and falling corporate profits would be much more dangerous.
That is when refinancing pressure can turn into covenant breaches, distressed exchanges, restructurings and defaults.
The Federal Reserve has explicitly warned that higher rates can amplify vulnerabilities associated with leverage and upcoming refinancing needs.
What investors should watch next
Investors should focus on five indicators rather than Treasury yields alone.
1. The 10-year Treasury yield
A sustained move above current levels would increase the baseline cost of corporate financing.
2. High-yield credit spreads
A sharp widening would indicate that investors are demanding substantially greater compensation for corporate credit risk.
3. Corporate refinancing volumes
If companies begin delaying bond issuance, it could signal that borrowers consider market pricing too expensive.
4. Interest coverage ratios
Companies with declining earnings and rising interest expense are particularly vulnerable.
5. Default and distressed-debt indicators
A sustained increase in defaults would suggest that the refinancing problem is becoming a solvency problem.
The bigger issue is the cost of capital
The most important consequence of the bond sell-off may not be a sudden wave of bankruptcies.
It may be a gradual repricing of corporate decision-making.
For more than a decade, exceptionally low interest rates encouraged companies to borrow cheaply, refinance frequently, acquire competitors and return capital to shareholders.
That model becomes less attractive when the cost of capital rises substantially.
The result could be a more disciplined corporate environment in which companies demand higher returns from acquisitions and capital projects.
That may ultimately be healthy.
But the transition could be painful for companies that built their business models around cheap debt.
A new test for corporate America
The US economy has already demonstrated considerable resilience in the face of higher rates.
The question now is whether that resilience extends to a corporate sector facing a large refinancing cycle.
The numbers suggest that the pressure will build gradually rather than arrive as a single shock.
The immediate danger is concentrated among highly leveraged and lower-rated companies. Investment-grade borrowers remain considerably better positioned.
But the refinancing calendar means the issue cannot simply be dismissed.
With roughly $4.3 trillion of non-financial corporate bonds coming due between 2027 and 2031, the cost of money over the next several years will matter enormously.
If Treasury yields eventually decline, many companies could refinance more comfortably.
If yields remain elevated while earnings weaken, the pressure could move steadily up the credit spectrum.
That makes the current bond-market sell-off more than a story about government debt.
It is becoming a test of how much corporate America can adapt to a world in which capital is no longer cheap.
Bottom line
The US corporate sector is not yet facing a systemic debt crisis. The stronger borrowers retain substantial market access, while investment-grade credit quality remains relatively resilient.
But the refinancing cycle is creating a growing divide between companies that can absorb higher interest costs and those that cannot.
The crucial variable is therefore not simply whether the Federal Reserve raises or lowers its policy rate.
It is whether long-term borrowing costs remain high long enough for the refinancing wall to become an earnings and solvency problem.
For investors, the next phase of the credit cycle will be about separating companies that can grow their cash flows faster than their financing costs from those whose balance sheets were built for the era of cheap money.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Wind Farm Economics in 2026: What Determines Whether a Project Pays?

Boomers vs Young Adults: Why the Net Worth Gap Is More Complicated Than It Looks

Is the AI Bubble Bursting in 2026? Five Tests Investors Should Watch

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Treasury Yields and Inflation 2026: What Bond Moves Mean for Borrowers

Social Security COLA 2027 Is 3.6%: Payments, Examples and Dates

Ukraine’s Oil Strike Strategy: Can It Break Russia’s War Economy?

Power Grid Emergency Across 13 States? What the October 2026 PJM Order Actually Says

Oil Prices October 2026: Iran Conflict, Shipping and Inflation Risks

TSMC Stock in October 2026: AI Chip Demand, Earnings and Valuation Risks

Stock Market Crash 2026: What the Inflation and AI Selloff Means

Student Loans and the 2026 Midterms: SAVE Plan Deadlines and Borrower Choices

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

World’s Largest Economies: Ranking the Top Global Powers

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Asian Stock Markets 2026: Japan, China, Pakistan & More

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

SpaceX IPO 2026: History’s Biggest Stock Debut?

Oil Prices 2026: Inside the Hormuz Crisis That Won’t End

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

IMF Reports 2026: What the Latest Data Means for the Global Economy

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Business Insurance: What Coverage You Actually Need and What It Costs in 2026
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025