
Governance
Pakistan Tax Net: Why Agriculture, Retail and Property Are So Hard to Tax

Why does Pakistan struggle to tax retail, property and agriculture? Explore evidence, fiscal trade-offs and fairer reform choices for FY2026–27.
Key Takeaways
- The FY2026–27 budget sets an FBR federal tax-revenue target of Rs15.264 trillion, an estimate rather than an actual collection.
- Agricultural income taxation is substantially a provincial matter, while federal income and sales taxes involve other jurisdictions and rules.
- An effective reform must distinguish workers who cannot avoid withholding from economic activity that is poorly documented; the tax burden is not identical across sectors.
- The World Bank’s 2025 tax-reform announcement reported 1.5 million new taxpayers supported through revenue-system reform, a programme result requiring ongoing scrutiny.
A schoolteacher’s salary is visible every month. Many transactions in farming, wholesale trade or property, by contrast, can be harder for authorities to observe and value accurately. That difference lies at the heart of the Pakistan tax net problem. The federal government budgeted Rs15.264 trillion in FBR revenue for FY2026–27, according to the official budget book. Yet debates about higher taxes often focus on people whose incomes are already documented.
The issue is not that every farmer or shopkeeper pays nothing. They can face sales taxes, input taxes, withholding taxes, provincial levies and indirect price burdens. The real policy question is whether profitable income and economic activity are taxed consistently and fairly, without turning registration into an administrative punishment for small businesses.
How narrow is the Pakistan tax net, and what does narrow mean?
A narrow tax base means too much revenue comes from a limited range of identifiable people, transactions or imports while other income is harder to measure and collect from. The 2026–27 federal budget expects Rs15.264 trillion in FBR taxes, with gross federal taxes and other receipts also supporting provincial transfers. The target describes planned collections, not proof the base has broadened.
| Area | Typical enforcement difficulty | Sensible reform direction |
|---|---|---|
| Salaries | Regular payroll records | Accurate withholding and fair rates |
| Retail trade | Cash receipts and fragmented records | Simple digital invoicing |
| Agricultural income | Provincial rules; farm income variability | Comparable records and provincial enforcement |
| Property | Valuation and transaction transparency | Credible valuations and verified records |
| Professional services | Mixed cash and account receipts | Third-party matching with due process |
The World Bank’s June 2025 tax-project update described data and administration improvements that had helped add 1.5 million taxpayers. The number should not be mistaken for 1.5 million consistently paying high taxes every year. Registration, active filing and actual liabilities are different steps.
A fair scorecard would report tax collected per sector after refunds, number of active returns, audit adjustments upheld on appeal and compliance costs paid by honest firms.
Why is agricultural income tax such a difficult issue?
Under Pakistan’s constitutional distribution of tax powers, provincial governments hold the main responsibility for taxing agricultural income. That makes coordination essential: a federal speech cannot itself ensure consistent agricultural-income enforcement in Punjab, Sindh, Khyber Pakhtunkhwa and Balochistan.
Agriculture is not one homogeneous business. A small tenant farmer exposed to crop failure is very different from a large, highly profitable farming enterprise with irrigation assets and multiple income streams. Rules should protect small producers while making substantial taxable profits harder to conceal.
The Pakistan Economic Survey 2025–26 reported agriculture at 23.44% of GDP in FY26. That economic significance is one reason the sector receives attention in reform discussions, but GDP share does not equal the share of people liable for agricultural income tax. Production value contains wages, inputs and costs; it is not identical to taxable net income.
A credible system requires usable land and crop records, transparent treatment of losses, protection against arbitrary assessment and data-sharing between federal and provincial agencies.
Why is Pakistan’s tax net considered narrow?
Large parts of economic activity are difficult to document or enforce against consistently, while payroll and formal transactions are easier to tax. A narrow base can make governments rely heavily on withholding and indirect taxes. It does not mean every farmer, shopkeeper or property owner pays zero taxes.
Why do cash-heavy retail markets remain hard to measure?
A retailer’s taxable profit is not equal to the cash that passes through the till. Shopkeepers pay rent, salaries, electricity and suppliers. Yet transactions without receipts can make it difficult to verify sales, input credits or profit. Complex filing rules can also discourage small shops from formalising.
Take a shop that records Rs1 million in monthly sales with Rs850,000 in legitimate goods and operating costs. Its gross-to-net calculation depends on inventory, returns and allowable expenses. Taxing total sales at an inappropriate profit rate would penalise thin-margin businesses; ignoring sales entirely would reward noncompliance. Accurate documentation allows both better assessment and fairer treatment.
The October 2026 IMF statement urges risk-based audits, digital invoicing and greater use of third-party data. Such systems can catch evasion while reducing arbitrary inspections, but only if data quality, appeal rights and taxpayer support are taken seriously.
Small retailers should receive genuinely simple registration and a chance to correct mistakes. Without that, digital tools become a new administrative barrier rather than a way to build trust.
What makes property tax and transaction tax so confusing?
Property sits at the intersection of federal taxes on specified income or transactions and provincial or local charges on ownership, transfer and registration. A headline that one federal provision has been abolished does not tell a buyer the complete cost of a transfer. Valuation differences between market prices and official records create obvious opportunities for understatement or disputes.
The Finance Act 2026 source should be consulted for federal provisions, while relevant provincial departments determine many transfer and property charges. A transaction may also face different rules according to purchase date, seller status and the type of property.
A reform with credibility would align valuations with observable evidence, keep an audit trail of major transfers and publish straightforward fee calculators. More transparency can improve revenue and reduce the bargaining power of unofficial intermediaries.
Tax policy should not be designed exclusively around reducing transaction costs for investors. It should also ask whether land and property rules support affordable housing, productive construction and efficient urban development.
Worked example: broadening the base without lifting payroll rates
Suppose a government needs Rs100 billion in additional annual revenue. One approach is to add that entire amount to an already compliant payroll base. Another is to collect Rs20 billion each from five previously under-documented groups through verified liabilities and lawful compliance. The total is the same, but the incidence is different. This is an illustrative allocation, not an estimate of evasion or the yield available in Pakistan.
To assess a real proposal, subtract the cost of collection and the compliance burden. If a scheme raises Rs100 billion but imposes Rs30 billion of administrative cost on firms, its economic payoff differs sharply from one raising the same tax with simple records and fewer disputes.
Fairness requires enforcement and appeal
A powerful institution can easily produce impressive audit notices. The harder task is to issue correct assessments, give taxpayers a reasonable response period and resolve appeals promptly. Digital enforcement should be measurable by collections sustained after appeal, not notices dispatched.
Which reforms should come first?
First, align federal and provincial definitions where legally possible, while respecting constitutional powers. Second, simplify filing for microbusinesses and identify fraudulent registrations through proportionate checks. Third, publish clear property valuation methods and reduce unofficial discretion. Fourth, link tax collection to visible public services and publish an independent assessment of whether exemptions produce jobs or investment.
The World Bank revenue project targets better data systems, transparent reporting and a broader base. The IMF reform recommendations of October 2026 also emphasise a simpler, fairer tax system. The policy challenge is to prevent digitalisation from becoming merely more aggressive surveillance of people already visible in databases.
Trust matters. Citizens are more likely to comply when powerful businesses and politically connected incomes face the same law, refunds arrive, and public money is accounted for. Durable revenue reform is as much an institutional project as a tax-rate decision.
What This Means for You
Salaried worker: Compare effective taxes, not only headline rates. Understand what payroll withholding covers and why broadening the base could reduce pressure for repeated rate increases in the future.
Shopkeeper: Keep separate business accounts, save invoices and learn the current rules for your category and jurisdiction. Good records can protect you from both underpayment penalties and arbitrary overassessment.
Farmer: Agricultural-income rules differ by province. Document yields, sales, rent and genuine expenses, and seek province-specific guidance before assuming federal salaried tax tables apply.
Property buyer: Obtain itemised federal and provincial tax estimates with a date and valuation basis; do not rely on an online claim that a property transaction is ‘tax-free’.
What to Watch Next
- 26 October 2026: The State Bank monetary-policy decision and any revision to its inflation assessment; verify any schedule change with the SBP.
- Early November 2026, exact release date to be confirmed: Pakistan Bureau of Statistics October inflation and merchandise-trade releases.
- Late October–November 2026, date not yet confirmed: Any IMF Executive Board announcement on the October staff-level agreement; staff agreement is not Board approval.
- Throughout FY2026–27: Updated SBP monthly balance-of-payments and remittance statistics; compare cumulative results rather than one month alone.
Frequently Asked Questions
Why is Pakistan’s tax net considered narrow?
Large parts of economic activity are difficult to document or enforce against consistently, while payroll and formal transactions are easier to tax. A narrow base can make governments rely heavily on withholding and indirect taxes. It does not mean every farmer, shopkeeper or property owner pays zero taxes.
Is agricultural income tax federal or provincial in Pakistan?
Agricultural income taxation largely falls under provincial jurisdiction, so rules and implementation differ across provinces. Federal income-tax provisions do not automatically substitute for provincial agricultural-income legislation. Farmers should verify applicable provincial rules and exemptions rather than rely on a national generalisation.
Does being registered with FBR mean a person paid income tax?
No. Registration, filing a return, declaring taxable income and paying an assessed amount are different steps. A person may file lawfully with no final income-tax liability. Evaluating tax reform requires more than counting newly registered taxpayers.
How can digital invoicing improve tax collection?
Digital records can make sales and input claims more verifiable, helping authorities target fraud and reducing manual disputes. But systems need simple onboarding, affordable equipment, safe data handling and a fair appeal process. Otherwise small compliant businesses may face disproportionate costs.
What is the federal FBR tax target for FY2026–27?
The official federal Budget in Brief provides an FBR tax-revenue budget estimate of Rs15.264 trillion for FY2026–27. This is a target set in the budget, not the amount ultimately collected. Actual fiscal reports should be checked as the year progresses.
Pakistan cannot permanently finance a modern state by repeatedly demanding more from the easiest pay packets to identify. Broadening the base must mean lawful, predictable taxation of real economic capacity, paired with stronger public accountability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


California voters will encounter Proposition 40 on the November 3, 2026 ballot. It proposes a one-time wealth tax on certain billionaires, making it a major test of competing ideas about tax fairness, state revenue and the effects of taxing mobile high-net-worth households. The legal details matter more than the campaign slogans.
According to the California Secretary of State’s official voter guide, Proposition 40 would impose a one-time tax equal to 5% of the wealth of certain taxpayers with assets exceeding $1 billion, with revenue primarily directed toward health care. The guide also outlines the measure’s budgetary provisions and potential fiscal effects.
What a YES vote would do
A YES vote supports enacting the measure, subject to the rules governing conflicting ballot propositions and subsequent legal interpretation. The core feature is a one-time tax based on qualifying wealth rather than simply an increase in the annual income tax rate. That distinction is central because wealth includes the value of assets, potentially beyond cash income available in a given year.
The official fiscal analysis estimates a temporary revenue increase spread across multiple years, while noting possible longer-term effects on certain tax revenues. As with any estimate, those projections are conditional on behavior, implementation and legal outcomes.
What a NO vote would do
A NO vote opposes Proposition 40. It would not by itself approve an alternative funding system for health care or settle every dispute about California’s existing tax structure. Readers should not assume that voting against one proposition automatically enacts a substitute policy.
Ballot labels can be deceptively simple. The actual consequences depend on the complete measure, current law and whether another approved initiative contains conflicting language.
Why Propositions 41 and 42 matter
The San Francisco Chronicle’s analysis explains that measures numbered 41 and 42 could conflict with Proposition 40. One addresses constraints surrounding tax measures; another addresses wealth and retroactive taxation. Under California’s rules for conflicting initiatives, vote totals and legal interpretation can affect which provisions take effect when more than one is approved.
That makes simplistic voting advice misleading. A voter evaluating Prop 40 should read the official texts and analyses of the related propositions, not only advertisements for one measure in isolation.
The argument for a wealth tax
Supporters contend that a small group of households controls substantial assets and that a wealth levy could provide revenue for public services without broadly increasing taxes on ordinary incomes. Their case rests on distributional fairness and the value of financing health-related needs. They also argue that exceptional wealth growth can be taxed separately from annual earnings.
Those claims invite legitimate scrutiny: How accurately can illiquid private assets be valued? What processes resolve disputes? How much would administration cost? How quickly could the expected money be spent on the stated purposes?
The argument against the measure
Opponents question the economic, legal and administrative consequences. A wealth tax may prompt asset relocation, restructuring, costly valuations or litigation. Such effects could reduce collections and alter future investment and income-tax receipts. Critics also question whether revenue estimates and spending promises sufficiently reflect behavioral responses.
Neither side should be permitted to transform an uncertain forecast into an assured outcome. Independent fiscal estimates, legal analysis and the actual text matter more than maximalist claims.
What voters should check
Read the official ballot summary and fiscal analysis, then consult Propositions 41 and 42 for interactions. Note the definition of a covered taxpayer, valuation dates, exemptions and revenue allocation. If the measures pass in conflicting combinations, follow certified results and any subsequent court proceedings before treating the outcome as final.
This article is an explanation, not an endorsement. The decision involves real trade-offs among fairness, fiscal certainty, administration and economic behavior.
What is difficult about valuing billionaire wealth?
A tax on net worth requires a defensible value for private businesses, partnership interests, real estate and other assets that may not trade every day. Appraisals and legal disputes can become material costs for both taxpayers and the state. Proponents may argue that valuation challenges are manageable with clear rules; opponents may argue they encourage litigation and economic relocation. The impact on state revenue depends on how many taxpayers are covered, how assets are measured and how behavior responds. The strongest voter guide should present those assumptions from the official fiscal analysis and refrain from claiming that the full headline estimate will inevitably arrive in cash.
Frequently asked questions
Is Prop 40 about income tax or wealth tax?
The main proposal is a one-time 5% tax on certain taxpayers with more than $1 billion in assets.
When is the vote?
The California general election is scheduled for November 3, 2026.
Could Prop 40 pass and still face uncertainty?
Yes. Conflicting propositions and potential legal disputes could affect implementation.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Governance
Conservative Party Conference 2026: What Badenoch’s Tax and Deregulation Pitch Means for the UK Economy
Key Takeaways
- The conference is opposition theatre with real market-adjacent consequences. The Conservatives can’t change a single tax rate this week, but their pitch shapes how investors, developers and businesses read the next election.
- The headline is deregulation. Shadow chancellor Andrew Griffith promised “the most ambitious deregulation project in a generation”, including scrapping the Future Homes Standard, replacing Section 106 and the Community Infrastructure Levy with one charge, and abolishing Natural England and the Environment Agency.
- The tax pledges are specific but uncosted. Griffith said the party would scrap Labour’s levy on high-value homes and its packaging tax, and he committed to tax simplification as a mission for every Treasury minister.
- The backdrop is unforgiving. The UK 10-year gilt yield was about 5.4% at the end of September and the 30-year briefly approached 6%, according to market data, with the Budget due on October 28.
- Credibility is the currency. After 2022, any unfunded tax promise is judged first by bond markets and only second by voters.
Political conferences have a strange job. They are partly pep rally, partly job interview and partly policy laboratory. For the Conservative Party gathering in Birmingham this week, the interview is with two audiences at once: voters who rejected the party in 2024, and bond investors who still remember how the 2022 mini-budget ended.
That second audience is the one that moves prices. So what did the Conservatives actually announce, what might it do to the economy if it ever became law, and what should businesses, homeowners and investors watch for between now and the Budget?
Here is the practical read, with the caveat that everything below remains a proposal from the opposition benches.
What Happened in Birmingham
Kemi Badenoch opened the conference on Sunday, October 4, by publishing an almost 100-page document called The Right Way. In it she warned that living standards have stalled and that regulation has accumulated faster than anyone can remove it, per Press Association reporting. The document also acknowledges failures in earlier Conservative approaches to net zero, immigration and the way Brexit was delivered, as RTÉ reported.
On Monday, October 5, Griffith followed with the economic detail. According to the text of his speech, he framed the country as having a debt problem, a tax problem and a growth problem, and promised to scrap the Family Farm and Family Business inheritance tax, Labour’s packaging tax and its levy on high-value homes.
The Proposals at a Glance
| Proposal | Who it affects | Likely economic channel | Biggest open question |
|---|---|---|---|
| Scrap the Future Homes Standard | Housebuilders, buyers, energy bills | Cheaper construction, higher running costs | Does lower build cost reach buyers? |
| Replace Section 106 and CIL with a single charge | Developers, local councils | Faster approvals, simpler levies | Who funds local infrastructure? |
| Abolish stamp duty (existing policy) | Home movers, property market | More transactions, upward price pressure | Cost to the Exchequer |
| Abolish Natural England and the Environment Agency | Farmers, builders, regulators | Fewer permitting delays | Environmental enforcement capacity |
| Scrap extended producer responsibility for packaging | Manufacturers, retailers | A claimed £1.5 billion cost relief | Who pays for waste collection? |
| Scrap the high-value homes levy | Owners of expensive property | Tax relief for a narrow group | Revenue replacement |
| Back a third Heathrow runway | Aviation, logistics, construction | Long-run capacity and investment | Planning, cost and climate |
| Review Making Tax Digital and IR35 | Small firms, freelancers | Lower compliance burden | Details are still missing |
The Housing Trade-Off Nobody Mentions on Stage
The most concrete number in the package comes from a 2023 Birmingham City Council document the party’s researchers pointed to. It found that heat pumps, better efficiency and solar panels could add £30,789 to the cost of building a detached home. The same document estimated those technologies could cut £2,715 a year from energy bills, effectively paying for themselves in roughly 11 years.
Read that carefully. Scrapping the standard can lower the sticker price of a new home, but it may raise the lifetime cost of living in it. Whether buyers come out ahead depends on mortgage rates, energy prices and how long they stay put.
That is the pattern across the package. Almost every proposal moves a cost from one column to another, rather than deleting it.
The Market Backdrop: Why Bond Investors Are Watching
Here is the context that makes this more than a debate about red tape.
- The UK 10-year gilt yield rose to about 5.39% on October 5, according to Trading Economics, after a global bond sell-off pushed it to the highest levels since 2007.
- The 30-year yield touched roughly 6%, the first time since 1998.
- The Bank of England held Bank Rate at 3.75% in September, as noted by IFA Magazine, while markets price some tightening ahead.
- Chancellor John Healey, appointed by Prime Minister Andy Burnham on July 20, has said fiscal discipline will anchor the October 28 Budget.
A rule of thumb quoted in market commentary is that every quarter-point rise in gilt yields can erase billions of pounds of the Chancellor’s headroom. Higher yields make every tax-cutting promise harder to fund.
The Ghost in the Room: 2022
You cannot discuss Tory tax cuts without mentioning the mini-budget. In 2022 the government announced what Fortune described as the biggest set of unfunded tax cuts in half a century, and gilt markets reacted violently.
Griffith is plainly aware of the comparison. He framed himself as a chancellor who wants to cut taxes only when the country can afford it, and his package leans on deregulation and simplification rather than headline rate cuts. Voters and investors will test whether the arithmetic really works.
What Rivals Said
The reactions map the political terrain.
- Labour’s chair, Bridget Phillipson, said the Conservatives wanted to take the country back to a politics that let people down, and pointed to 14 years of government.
- The Liberal Democrats’ Daisy Cooper called the pledges “fantasy-land” financial promises.
- Reform UK’s Robert Jenrick said the Tories were copying his party’s policies, and contrasted them with Reform’s pledge to raise the income-tax personal allowance from £12,570 to £15,000.
The crowded right flank matters. A party that looks too cautious loses voters to Reform, and a party that looks reckless loses the bond market.
What This Means for Businesses, Homeowners and Investors
Nothing here changes your tax bill today. But the direction of travel is worth tracking.
If you run a business
Watch the Budget for signals on compliance costs. Proposals to review Making Tax Digital and IR35 and to scrap the packaging levy would matter, but only if they survive contact with Treasury costings.
If you own or plan to buy property
The stamp duty and new-build changes, if enacted, would affect transaction volumes and construction costs. Mortgage pricing, however, is driven by gilt yields, so the bond market will shape your costs more than any conference speech.
If you invest in UK assets
Treat the conference as a read on political risk. The relevant questions are how credible the fiscal framework looks, whether pledges are costed, and how the gilt market reacts on and after Budget day. This isn’t investment advice.
A Three-Question Test for Any Opposition Economic Plan
Conference season produces dozens of announcements, and most won’t survive contact with a Treasury spreadsheet. Here’s a quick filter you can apply to this package, or to any other.
1. Is it costed?
A pledge with a price tag can be argued with. A pledge without one can only be believed or doubted. With gilt yields already high, the market’s default setting is doubt. Watch whether the party publishes figures, and whether independent forecasters accept them.
2. Who ends up paying?
Abolishing a levy rarely abolishes the cost it was funding. Replacing Section 106 and CIL with a single charge, for example, still has to pay for roads, schools and drainage somewhere. The same goes for packaging waste, where scrapping the producer-responsibility scheme would lift a claimed £1.5 billion burden from businesses but leave the question of who funds collection and recycling.
3. Can it be delivered quickly?
Deregulation sounds fast and often isn’t. Abolishing two regulators and folding their work into a government department means legislation, transition and staff decisions. The party says it will set out plans “line by line,” which is the right instinct, because detail is what turns a conference slogan into a credible first-hundred-days timetable.
Apply the test and the package splits into two groups. Simplification and review proposals, such as Making Tax Digital and IR35, are cheap to promise and quick to reform. Structural changes to housing standards and environmental regulators carry larger consequences and bigger uncertainty. Markets will price the second group more cautiously, and rightly so.
Asked & Answered
Did the Conservatives announce any tax cuts at the 2026 conference?
They announced pledges to scrap several taxes and levies, including Labour’s high-value homes levy and its packaging tax, and confirmed existing policies such as abolishing stamp duty. None can take effect unless the party wins power.
What is the Conservatives’ deregulation plan?
Shadow chancellor Andrew Griffith called it the most ambitious in a generation. It includes scrapping the Future Homes Standard, replacing Section 106 and CIL with a single charge, abolishing Natural England and the Environment Agency, and removing packaging responsibility rules.
Would these policies lower house prices?
The party argues they would reduce building costs and boost supply. Economists would want to see how much of the saving reaches buyers, and how stamp duty abolition affects demand. The outcome is uncertain.
How do gilt yields affect the Conservatives’ plans?
Higher yields raise the government’s borrowing costs and shrink fiscal headroom, which makes unfunded tax cuts harder to defend. That is why bond-market credibility is central to the Conservative pitch.
When is the next major economic event for the UK?
The Autumn Budget is scheduled for October 28, 2026, and the Bank of England’s next decisions will also shape borrowing costs.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Markets & Finance
Analytical Review of The Economist’s “What is the Right Tax System for the 21st Century?”
Core Premise & Scope
The Economist correctly diagnoses the structural breakdown of 20th-century tax systems across advanced economies. As sovereign debt loads surge, long-term bond yields remain elevated, demographic aging inflates entitlements, and defense and climate commitments expand, standard fiscal architectures are failing. The article argues that current systems rely too heavily on distortive income and labor taxes while ignoring immobile wealth, land, and environmental negative externalities.
Critical Analytical Gaps
While The Economist identifies key symptoms, its analysis exhibits four primary operational gaps:
- Failure to Address the AI Labor Tax Erosion: High-income nations derive over 40–60% of total tax revenues from Personal Income Tax (PIT) and Social Security Contributions (SSCs). As artificial intelligence and autonomous workflows displace high-wage cognitive labor, standard income tax bases will erode. The Economist treats labor taxation as static rather than declining.
- Abstract Land & Wealth Taxation Without Transition Economics: Advocating for Land Value Taxes (LVT) and property tax overhauls is theoretically sound but politically non-viable without explicit transitional mechanisms (such as tax credits against capital gains or phased revenue-neutral shifts).
- Over-reliance on OECD Consensus Enforcement: The piece assumes smooth global coordination via the OECD Inclusive Framework. In reality, jurisdictional profit-shifting and implementation friction between market nations and headquarters hubs create major enforcement leaks.
- Omission of Cash-Flow Expenditure Architectures: The analysis fails to evaluate Destination-Based Cash-Flow Taxation (DBCFT), which removes incentives for corporate inversion while exempting marginal investment from capital distortion.
Designing the Optimal Tax System for the 21st Century
Tax codes across the developed world are relics of a 1950s industrial economy. Built on the assumption of immobile domestic corporations, fixed physical factories, and stable wage labor, 20th-century tax models create massive deadweight losses, disincentivize capital formation, and fuel wealth inequality.
A modern tax architecture must maximize economic efficiency and neutrality while maintaining progressive distribution and fiscal solvency. Achieving this requires shifting the tax base away from productive inputs (labor and investment) toward unearned economic rents, immobile assets, and negative externalities.
       TRADITIONAL TAX BASE                   21ST-CENTURY TAX ARCHITECTURE
┌─────────────────────────────────┐       ┌─────────────────────────────────┐
│ • High Marginal Income Taxes   │       │ • Land Value Taxation (LVT)     │
│ • Corporate Income Tax (CIT)   │  ───► │ • Progressive Expenditure Tax   │
│ • Payroll & SSC Distortions    │       │ • Pigouvian Carbon Pricing      │
│ • Capital Gains Penalties       │       │ • Destination Cash-Flow Model   │
└─────────────────────────────────┘       └─────────────────────────────────┘
Structural Failures of Current Fiscal Architectures
Modern sovereign states face a structural triad of fiscal pressures:
- Demographic Entitlement Creep: Aging populations reduce the working-age tax base while accelerating expenditures on public pensions and healthcare.
- Labor Income Erosion: Technological displacement and the growth of independent digital work dismantle traditional payroll tax collection mechanisms.
- Capital Mobility & Base Erosion: Intangible assets (IP, algorithms, digital platforms) allow multinational entities to shift taxable profits across borders, undermining standard corporate income taxes.
According to data from the Urban-Brookings Tax Policy Center, high marginal tax rates on capital and labor depress long-run economic growth by creating deadweight loss wedges between pre-tax returns and post-tax rewards.
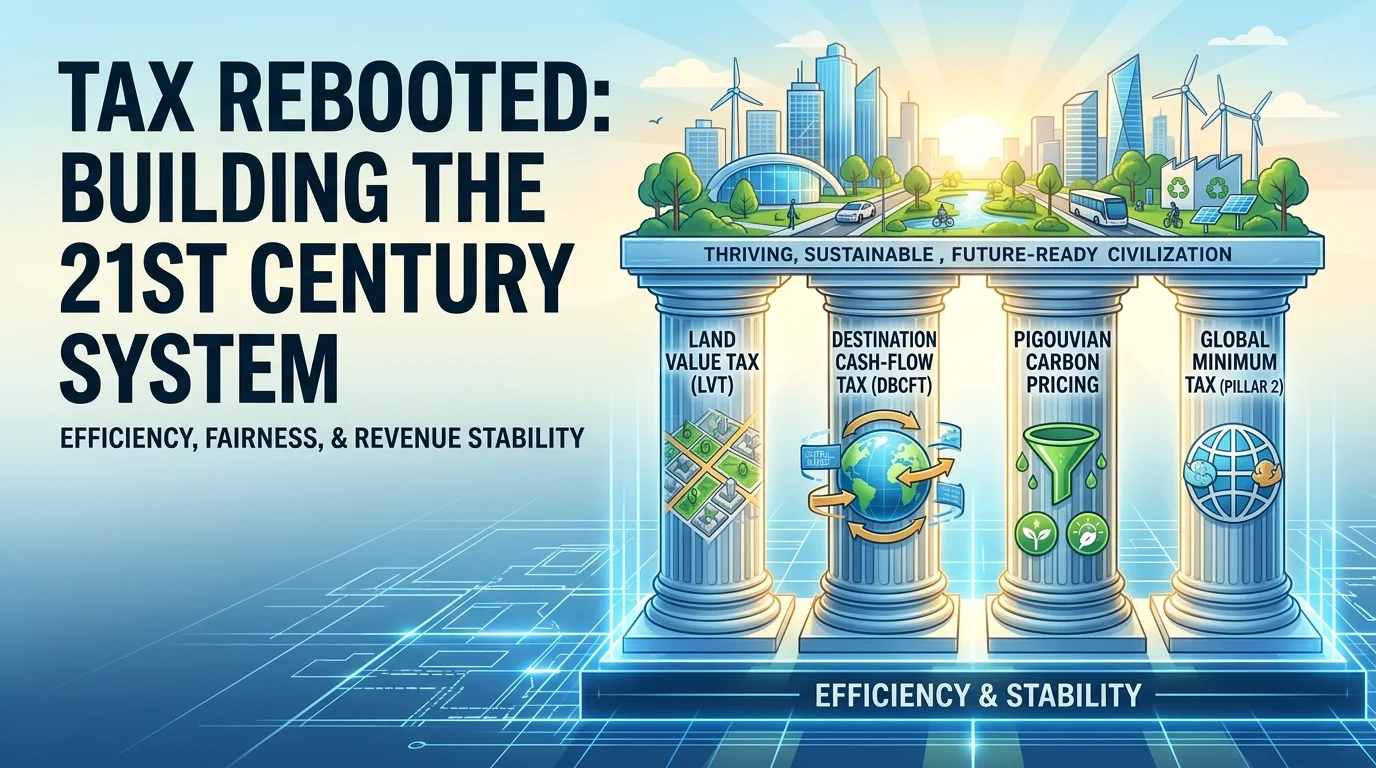
The Four Pillars of the Modern Tax System
                  ┌─────────────────────────────────────────┐
                  │    21st Century Tax Architecture        │
                  └────────────────────┬────────────────────┘
                                       │
        ┌──────────────────┬───────────┴───────────┬──────────────────┐
        ▼                  ▼                       ▼                  ▼
┌───────────────┐  ┌───────────────┐       ┌───────────────┐  ┌───────────────┐
│  Land Value   │  │  Destination  │       │   Pigouvian   │  │  Global Min   │
│ Tax (LVT)     │  │  Cash-Flow    │       │ Carbon Pricing│  │  Pillar 1/2   │
└───────────────┘  └───────────────┘       └───────────────┘  └───────────────┘
1. Land Value Taxation (LVT)
Land is inelastic in supply. Taxing the unimproved value of land creates zero economic deadweight loss because land cannot relocate or shrink in response to taxation.
- Abolish Standard Property Taxes on Improvements: Traditional property taxes penalize building construction and urban development. Taxing only the underlying land value incentivizes efficient land use and infill development.
- Recapture Unearned Location Value: Urban land values appreciate primarily due to public infrastructure (transit, utilities, public safety) and community growth. An LVT captures these economic rents for public revenue without taxing private capital improvements.
2. Progressive Destination-Based Consumption Tax
Replacing corporate income taxes and high personal income brackets with a progressive cash-flow consumption tax removes the double-taxation penalty on savings and investment.
- Destination-Based Cash-Flow Tax (DBCFT): Tax is levied where goods or services are consumed, rendering corporate tax avoidance via offshore profit-shifting obsolete.
- Full Expensing of Capital Investments: Businesses immediately deduct all capital expenditures, removing investment distortions and accelerating productivity growth.
- Individual Progressive Consumption Tax: Individuals report total income minus net savings. The remaining spending is taxed at progressive rates, shielding low-income households via prebates or personal allowances.
3. Pigouvian Externality Pricing
Taxes should actively discourage activities that impose unpriced costs on society. Pigouvian levies convert social harms into direct fiscal revenue.
- Upstream Carbon Taxation: Implementing a border-adjusted carbon tax prices environmental damage directly into energy and goods production. As outlined in the IMF Fiscal Policy Frameworks, pricing carbon provides market signals for green technology transitions while generating revenue to offset lower income taxes.
- Resource and Congestion Levies: Variable tolling on urban roadways and extraction fees on finite natural resources internalize spatial and environmental costs.
4. Coordinated Multilateral Corporate Minimum Taxes
To address profit-shifting by digital multinationals, international tax law must transition from physical presence rules to destination-based profit allocation.
- Implementation of OECD Pillar 1 & Pillar 2: Adopting a global minimum corporate tax rate of 15% eliminates race-to-the-bottom tax competition, as detailed in the OECD Global Tax Framework.
- Formula Apportionment for Digital Services: Allocating multinational taxable income based on sales destination and active user bases ensures fair revenue distribution without requiring physical offices.
Comparative Analysis of Tax Regimes
| Tax Model | Economic Efficiency | Distributional Equity | Evasion Resilience | Administrative Complexity |
| Traditional Income & Corporate Tax | Low (High deadweight loss, double taxation of savings) | Moderate (Progressive on paper, vulnerable to deductions) | Low (Prone to offshore shifting and tax shelters) | High (Requires extensive compliance and auditing) |
| Wealth & Inheritance Taxation | Low-Moderate (Risks capital flight and valuation disputes) | High (Targets accumulated asset concentration) | Low (Capital moves to non-reporting jurisdictions) | Very High (Requires complex annual asset valuations) |
| Land Value Taxation (LVT) | Maximum (Zero supply distortion on unimproved land) | High (Progressive; land ownership is heavily concentrated) | Maximum (Immobile physical asset) | Low (Requires transparent cadastral land valuation) |
| Destination Cash-Flow Consumption Tax | High (Promotes investment, eliminates capital penalties) | High (Progressive spending tiers + prebates) | High (Border adjustments eliminate transfer pricing) | Moderate (Relies on border adjustments and financial transaction data) |
Mitigating AI-Driven Disruption to Public Finance
As AI tools and automation displace labor income, tax systems relying on payroll fees face declining receipts. Attempting to tax AI directly through “robot taxes” slows innovation and distorts technical adoption.
┌────────────────────────────────────────────────────────────────────────┐
│                        AI DISRUPTION & TAX BASE                        │
├──────────────────────────────────┬─────────────────────────────────────┤
│  Flawed Approach: Robot Taxes    │  Optimal Approach: Cash-Flow Tax    │
├──────────────────────────────────┼─────────────────────────────────────┤
│ • Penalizes technology adoption  │ • Taxes economic output at spending │
│ • Arbitrary definition of "robot" │ • Captures AI super-normal rents    │
│ • Slows productivity growth      │ • Neutral to technology choice      │
└──────────────────────────────────┴─────────────────────────────────────┘
The solution is to decouple public revenues from labor payrolls altogether:
- Shift Base to Corporate Cash-Flow and Land: As capital yields an increasing share of national income relative to wages, taxation must target corporate economic rents and land values rather than wage receipts.
- Eliminate Payroll Tax Caps: Remove income thresholds on social insurance contributions to maintain equity during structural shifts in high-earner distributions.
- Expand Universal Citizen Dividends: Fund social safety nets using revenues generated from Pigouvian carbon taxes and land value capture rather than taxing wage transactions.
Political Execution & Transition Roadmap
Reforming a tax code requires managing transition shocks to prevent capital flight or political paralysis.
Phase 1: Stabilization (Years 1-2)
├── Introduce upstream Carbon Tax with dividend returns
└── Enact OECD Pillar 2 15% global minimum tax

Phase 2: Base Shift (Years 3-5)
├── Replace local property taxes with Land Value Tax (LVT)
└── Allow 100% immediate expensing for business investments

Phase 3: Structural Realignment (Years 6-10)
├── Consolidate Personal Income Tax into Progressive Consumption Tax
└── Phase down distortionary corporate income tax rates
- Revenue-Neutral Phase-In: Pair new Land Value Taxes and carbon levies with immediate rate reductions on wage income and full capital expensing for businesses.
- Granular Tax Prebates: Mitigate regressivity in consumption taxes by distributing monthly advance rebates to low-and-middle-income households.
- International Harmonization: Secure treaty compliance through the IMF International Tax Reform Guidelines, ensuring uniform adoption of destination-based rules across major trading blocs.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

Agri-Tech Pakistan 2026: Where Farming Innovation Could Actually Pay

Pakistan Tax Net: Why Agriculture, Retail and Property Are So Hard to Tax

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Pakistan IT Exports 2026: What Would It Take to Reach $10 Billion?

Pakistan AI Policy 2025: Can It Raise Productivity and Create Jobs?

Pakistan Remittances 2026: How Overseas Workers Support the Economy

Can Pakistan Reach $34 Billion in Exports? The Real Barriers and Fastest Fixes

Why Pakistan’s Inflation Is Still Near 10% Despite Economic Stabilisation

Holiday Airfare 2026: Why Flights Cost More & Fares

California Prop 40 Explained: The 2026 Billionaire Wealth Tax Ballot Measure

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

AIIB in 2026: Can Green Infrastructure Deliver Measurable Growth?

IMF and World Bank Outlook 2026: Growth, Debt and the Missing Investment

World’s Largest Economies: Ranking the Top Global Powers

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Asian Stock Markets 2026: Japan, China, Pakistan & More

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Oil Prices 2026: Inside the Hormuz Crisis That Won’t End

SpaceX IPO 2026: History’s Biggest Stock Debut?

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

IMF Reports 2026: What the Latest Data Means for the Global Economy

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Is AI a Stock Bubble in 2026? What the Data Shows
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025