
Analysis
How to Invest in PSX in 2026 for Maximum Profits

The KSE-100 hit 191,032 points in January 2026 — a record. By late May it’s trading around 163,000, bruised by an unexpected rate hike, Middle East oil shocks, and a brief India-Pakistan military standoff that rattled institutional nerves across South Asia. To the undisciplined eye, this looks like a market in retreat. To the structural investor, it looks like an entry point.
The Macro Backdrop: Stability With a Sting in the Tail
Pakistan’s economy entered 2026 in a state of cautious repair. The country had narrowly avoided sovereign default in mid-2023, survived three years of IMF-supervised austerity, and emerged by the second half of FY25 with an equity market that delivered some of the world’s strongest returns — a 57% USD-based return in FY25, according to Arif Habib Limited. Pakistan’s benchmark reached the kind of numbers that make frontier market fund managers sit up and call their brokers in Karachi.
That tailwind ran into several headwinds in rapid succession. The State Bank of Pakistan (SBP), which had cut rates from a peak of 22% to 10.5% through a year-long easing cycle, surprised markets in late April 2026 by hiking the policy rate back to 11.5% as oil price pressures and imported inflation demanded attention. Headline inflation climbed to 7.3% in March 2026. The IMF’s April 2026 World Economic Outlook raised its inflation forecast for Pakistan’s next fiscal year to 8.4%, well above the 7% projected just months earlier.
Yet the foundations underneath remain more solid than the volatility suggests. Real GDP grew at 3.8% in the first half of FY26 — nearly double the 1.9% recorded in the same period a year prior. A staff-level agreement with the IMF was reached on 27 March 2026, unlocking the path to further disbursements from the $7 billion Extended Fund Facility. Pakistan’s SBP FX reserves stood at approximately $15.8 billion as of 24 April 2026, supported by a successful Eurobond issuance — the country’s first re-entry into international capital markets in over four years. The current account posted a small surplus during the July-to-March FY26 period.
These are not the macroeconomic readings of a market to flee. They’re the readings of a market to analyse with discipline.
How to Invest in PSX 2026: Reading the Market’s True Valuation Signal
The single most important number for any investor assessing the Pakistan Stock Exchange right now is not the index level. It’s the price-to-earnings ratio.
With the KSE-100 trading at a price-to-earnings ratio of approximately 7x, the market is pricing in substantial pessimism relative to underlying corporate profitability. For context, the MSCI Frontier Markets average P/E sits materially higher. The PSX’s price-to-book ratio of 1.1x similarly suggests that investors are, in aggregate, paying roughly par for assets that — in a normalising rate environment — ought to command a premium. Topline Securities CEO Mohammed Sohail described the valuation picture plainly following the March 2026 selloff: at these levels, the market offers compelling entry points for medium- and long-term investors.
Fifteen major brokerage houses covering 78 PSX-listed stocks have set a consensus KSE-100 year-end 2026 target of approximately 210,000 points — representing around 40% upside from current levels. AKD Research’s more aggressive estimate sits at 263,800. The variance between these targets matters: it reflects genuine disagreement about the pace of rate normalisation, the durability of the IMF programme, and the trajectory of global oil prices following the US-Iran tensions that rattled energy markets through the spring of 2026.
“Pakistan’s KSE-100 has been among the world’s best-performing markets over the past 12 months. With GDP growth projected at 4–5% in 2026, the rally may only be in its second inning.” — Arif Habib Limited, Strategy FY26
What is the best time to invest in PSX in 2026?
The historically optimal entry windows on the KSE-100 tend to follow periods of macro clarity — specifically, confirmed IMF disbursements, stable SBP rate guidance, and easing of political uncertainty. With the March 2026 IMF staff-level agreement now in place and the India-Pakistan ceasefire brokered in May, the second half of calendar 2026 — particularly Q3 — historically presents more favourable risk-adjusted conditions than the Q1 volatility period. Systematic, staged entry across several weeks reduces timing risk materially.
Sector Strategy: Where the Structural Money Is Moving
For investors asking how to invest in PSX for maximum profits in 2026, the sector question is more consequential than the timing question. Not all of the KSE-100’s 40% consensus upside is distributed equally across industries.
Commercial Banking remains the index’s dominant weight and the most institutionally liquid play on Pakistan’s macro recovery. Banks such as MCB, UBL, and Meezan Bank have benefited simultaneously from high nominal interest rate spreads and growing retail deposit bases. UBL’s share price delivered a 181% one-year return into 2025, supported by revenue growth of 32.8%. Meezan Bank, Pakistan’s largest Islamic lender with a market capitalisation of approximately $2.1 billion, rose 50% in the same period. That said, the April 2026 rate hike introduces a complex dynamic: higher rates sustain near-term spreads but pressure credit growth and loan book quality if held for too long.
Fertilizer is the sector most directly wired to Pakistan’s agricultural economy — and that economy is not optional. Fauji Fertiliser Company (FFC) reported revenue growth of 126% and profit growth of 81% at its last major disclosure, with the stock rallying 140% in a single year. FFC holds a market capitalisation of $1.96 billion and benefits structurally from government subsidy visibility and rural credit expansion. Engro Fertilizers (EFERT) offers a comparable exposure at a somewhat different balance sheet profile. The risk worth monitoring: any policy reversal on fertiliser subsidies or urea pricing could compress margins abruptly.
Technology deserves a separate conversation. Systems Limited (SYS) stands apart as the PSX’s most differentiated growth story — a software exporter earning a significant share of its revenues in US dollars from North American and European clients. That structural dollar revenue provides a natural hedge against rupee weakness that no bank or commodity company can replicate. In a market dominated by cyclicals, SYS represents the rare combination of earnings quality and currency resilience. Its re-rating potential as the global IT outsourcing market expands into Pakistan’s competitive labour market is genuinely underappreciated by domestic institutional consensus.
Energy and E&P present the most complex risk-return profile in 2026. Pakistan Petroleum Limited (PPL), with a market cap of $1.63 billion, and Oil & Gas Development Company (OGDC) both offer compelling dividend yields against a backdrop of elevated global crude prices. Yet the same oil price surge that boosts their revenue lines also feeds Pakistan’s import bill, pressures the current account, and increases the probability of policy rate responses — the very dynamic that triggered April’s rate hike. Energy is a hedge play rather than a pure growth play in this environment.
The Structural Case: Why the Longer Arc Points Up
Pull back from the Q1 2026 noise and a different picture emerges.
Pakistan’s market capitalisation reached a peak of PKR 20.83 trillion in January 2026 — an all-time high. The KSE-100 is approximately 65% higher than it was 12 months ago, even after the spring 2026 correction. The index remains one of the most liquid within the MSCI Frontier Markets universe, with an average daily trading volume of $102 million recorded in FY25.
Retail participation is transforming the market’s composition. Over 500,000 active investor accounts now exist on PSX — a number that was a fraction of this as recently as 2021. Digital brokerage platforms, the Roshan Digital Account ecosystem serving overseas Pakistanis, and Urdu-language financial literacy campaigns are structurally expanding the domestic capital base. This is not a speculative phenomenon. It’s demographic and technological, and it’s not reversing.
Pakistan’s re-entry into the Eurobond market in early 2026 signals something important to international capital allocators: the country can access external financing at market rates again. That re-rating of sovereign credibility takes time to fully translate into equity valuations — but the direction of travel is clear. The IMF projects Pakistan’s GDP growth at 3.6% for FY26, with World Bank forecasts broadly aligned. These are not blockbuster numbers, but they represent genuine recovery momentum from the fiscal trough of 2022-23.
The picture is more complicated, however, when one examines where this growth is sourced. Agriculture and services are doing the heavy lifting; large-scale manufacturing remains sluggish. Infrastructure spend tied to CPEC has faced implementation delays. And Pakistan’s export base — critically important for sustaining foreign exchange inflows — faces headwinds from global trade friction and intensifying competition in textiles and garments from Bangladesh and Vietnam. A structurally narrow export basket is the PSX’s longest-running unresolved vulnerability.
The Case Against: Risks That Deserve Steel-Manning
The bearish thesis on PSX 2026 is not thin. It deserves honest treatment.
First, the crowded consensus risk. Every major brokerage in Pakistan is bullish. When 15 out of 15 research desks point in the same direction, the contrarian question is not whether they’re wrong about the direction — it’s whether the upside is already priced into the positioning of those who entered at 191,032 in January. Academic research on Pakistani retail investors confirms that anchoring, overconfidence, and herding are statistically significant drivers of PSX investment decisions. The investor who arrives at Stage 4 of a consensus cycle — when “everyone knows” the bull story — historically buys near the top.
Second, rate path uncertainty. The April 2026 rate hike to 11.5% was unexpected. It signals that the SBP’s easing cycle — which was the primary fuel for the 2024-25 bull run — may not be as complete as markets assumed. If inflation continues to climb toward the IMF’s projected 8.4% for FY27, the rate environment that powered banking sector margins begins to strain corporate borrowers and consumer sentiment simultaneously.
Third, geopolitical concentration risk. The India-Pakistan military confrontation of May 2025 — sparked by the Pahalgam terror attack — wiped PKR 820 billion in equity value from PSX in three trading days before a US-brokered ceasefire triggered the index’s sharpest single-day rally in 26 years. Brokerage Arif Habib Limited noted the ceasefire as the most significant catalyst for the 9.45% single-day surge. Geopolitics, in other words, can move the PSX 10% in either direction inside a week. That’s a risk profile that demands genuine position sizing discipline — not a reason to stay out, but a compelling reason not to go all in.
Fourth, the current account trajectory. The IMF has more than doubled its current account deficit projection for Pakistan’s FY27 to 0.9% of GDP, up from 0.4% for the current year. A widening external deficit, if combined with softer remittance inflows or delayed official financing, could repressure the rupee — and a weaker rupee erodes the USD-equivalent returns that drove foreign portfolio interest in FY25.
These risks are real. None of them, individually or collectively, constitutes a thesis for avoiding Pakistan’s equity market entirely. But they do constitute a compelling argument for entering with a diversified, staged, and sector-specific approach rather than a concentrated single-tranche bet on the index.
A Practical Framework for the 2026 PSX Investor
The investors who will do best on PSX through the remainder of 2026 are likely those who treat the current corrective phase not as a warning but as a price discovery mechanism doing exactly what it should — stripping out the January euphoria and revealing which companies and sectors hold up on fundamentals alone.
For investors opening positions through a SECP-registered broker, the core allocation logic is straightforward: anchor to large-cap, high-liquidity blue chips within the KSE-100 — banking, fertilizer, and selective E&P — that combine earnings visibility with dividend income as a return floor. Layer in a technology allocation through Systems Limited for currency-resilient, non-cyclical growth. Keep position sizes modest enough to add on dips rather than panic-sell through them.
The PSX in 2026 is not a market for the impatient. It never has been. But for those who understand that a P/E of 7x in a normalising macro environment is not a danger sign — it’s an invitation — the second half of this year may look, in retrospect, like the window that was obvious in hindsight and uncomfortable to act in at the time.
It usually is.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
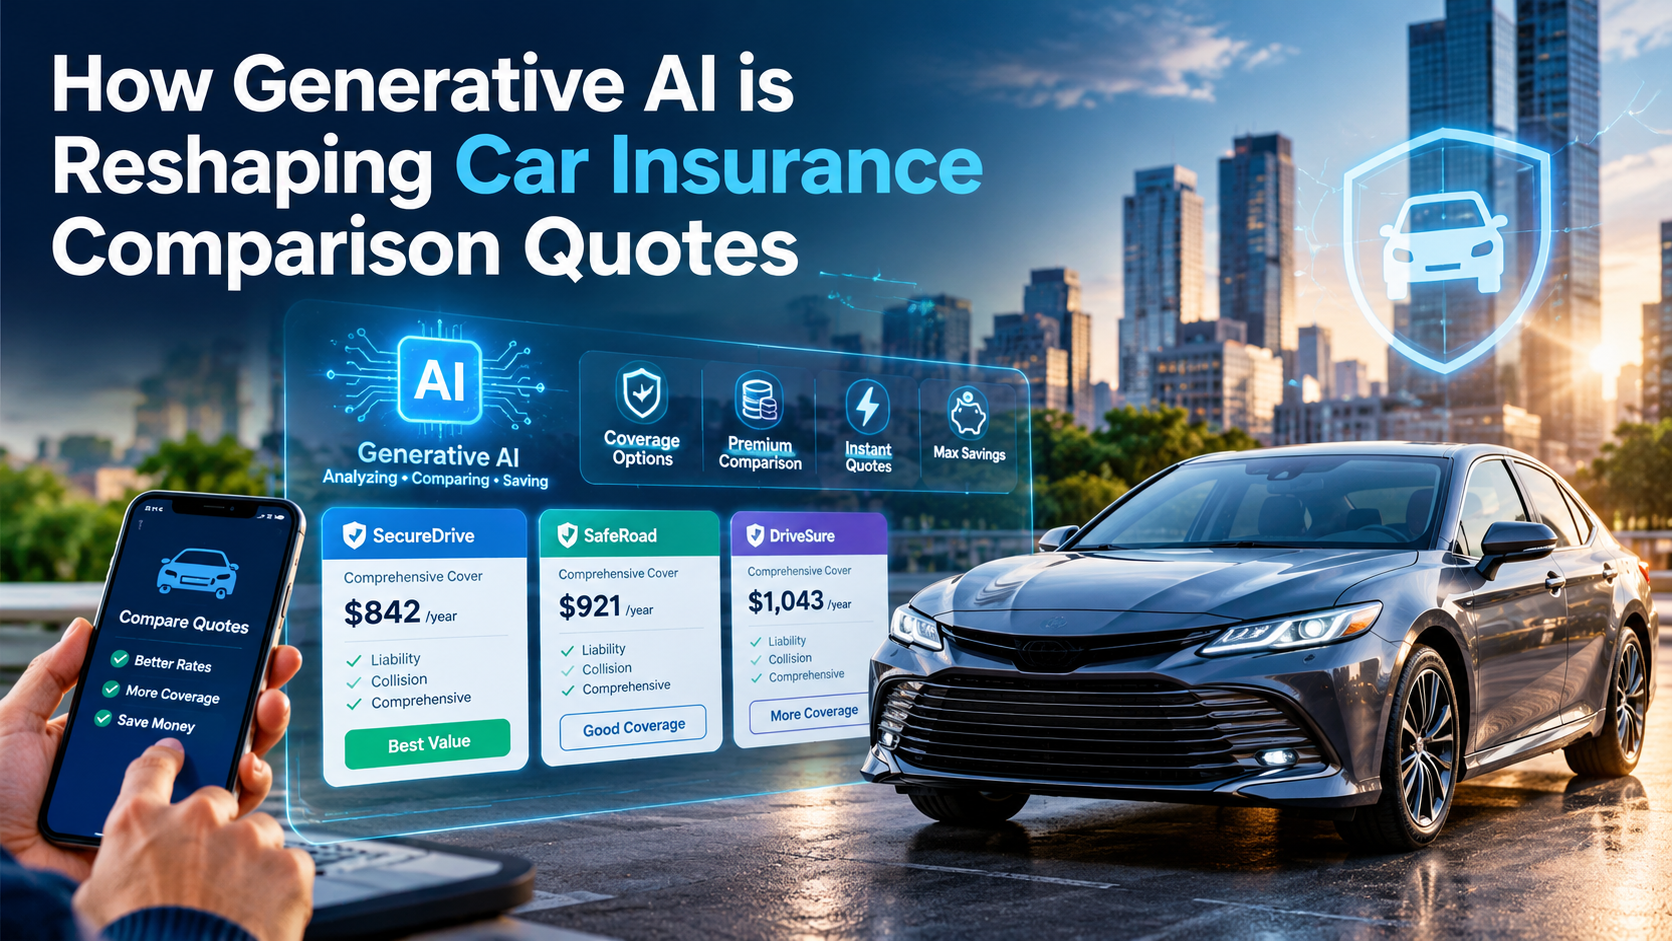
The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Jeff Bezos Three-Day Workweek View: What He Really Said

Celeste Frozen Pizza Discontinued: What Conagra Confirmed

US–China Critical Minerals Competition: Why a Trade Deal Cannot Fix Every Supply Risk

Oil Price Outlook 2026: How Supply Risks Reach Fuel Bills, Inflation and Business Costs

AI in Business 2026: Why Faster Employees Do Not Automatically Mean Higher Profits

Mortgage Rates in 2026: Why They Remain High and How to Compare the True Cost

Gold Price Outlook 2026: The Forces Behind the Forecasts—and What Could Reverse Them

Global Economic Outlook 2026: Growth, Inflation and Risks

Trump–Putin Diesel Deal: Why Zelensky Is Angry and What It Means for Fuel Prices

Anthropic Draws the Line: Why Claude’s New Usage Policy Explicitly Bans ‘Cruel Behavior’ Toward AI

Ynon Kreiz & Mattel’s Digital Transformation: Franchise Strategy and Financial Growth

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Middle East War Economics 2026: Oil Prices & Energy Markets

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Enterprise AI Platforms Disrupting B2B SaaS in 2026: Full Analysis

World’s Largest Economies: Ranking the Top Global Powers

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

Stock Market Today: Dow Climbs 500 Points as Markets Shake Off Inflation Jitters
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025