
Minerals
US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?


Critical minerals competition is about more than locating deposits. Mining, chemical processing, refining, component manufacturing and recycling are distinct steps. Reuters reported that the European Commission chose 46 additional strategic raw-material projects in October 2026, underscoring how U.S.–China tensions also shape the decisions of European governments and manufacturers. Sources: Reuters critical-minerals report and WTO World Trade Report.
The important context competitors can overlook
Rare earths, lithium, nickel and copper serve different industrial markets and cannot be treated as substitutes. Policies that improve domestic extraction may not immediately solve processing gaps or financing constraints. Permitting and environmental standards influence project timing, while export restrictions can shift costs to downstream industries. Supply-chain diversification often means higher initial expense in exchange for resilience. For primary-source checks and current reporting, see Reuters critical-minerals report and Reuters export-controls coverage. The key distinction is replace binary “winner” stories with mining-processing-chain analysis.
A practical way to use this information
For an accurate country comparison, build a matrix by mineral and processing stage, supported by official data. Ask who mines the ore, who refines it, where magnets or batteries are made, and how long new capacity takes to reach commercial output. Do not infer that a newly designated mine is producing at scale. Distinguish strategic announcements from realized tonnage.
Critical minerals security depends on refining, production quality and qualified supply chains—not simply the location of ore deposits. Research cutoff: October 12, 2026; confirm developing facts before publication.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Why are critical minerals geopolitically sensitive?
Production and processing are concentrated in different countries, creating trade and security vulnerabilities.
Does approving a mine fix supply immediately?
No. Permits, investment, construction and refining can take years.
A mineral deposit is only the start of a supply chain
A country can hold a large mineral resource without controlling the global market for usable industrial inputs. Extraction produces ore or concentrate; chemical processing and refining transform material into suitable compounds; component manufacturing turns those inputs into products such as magnets or batteries. Each stage requires different engineering, environmental approvals, energy, transportation and financing. Control over processing can be more strategically important than raw geological abundance when manufacturers need certified, consistent material delivered at scale.
“Critical mineral” is not a universal fixed list. Governments may prioritize resources according to industrial use, supply concentration and vulnerability to disruption. Rare earth elements, graphite, lithium, nickel, cobalt and other inputs have different markets and technical requirements. An article should specify the mineral and its role rather than treat the whole category as interchangeable. A shortage of battery-grade graphite and a shortage of high-performance magnet material are not the same operational problem.
Why refining and qualification take time
Building a refinery or processing facility can take years because projects need land, power, water, technical expertise, environmental assessments and commercial financing. Even when a plant is completed, customers often require qualification tests to ensure reliability and consistency. A carmaker or defense manufacturer may not immediately switch to a new supplier merely because that supplier announces capacity. Quality standards and intellectual property can limit substitutability. This creates a difference between planned capacity, commissioned output and material accepted by customers.
The same distinction applies to recycling. Scrap recovery can help diversify supply and reduce waste, but recovered materials still require processing and must meet product specifications. Recycling rates depend on collection systems, economics and the amount of recoverable material available. Treating recycling as a near-term replacement for all primary extraction is too simplistic. It is a complementary part of a resilient system.
Why the United States, China and Europe all matter
U.S.–China competition draws attention because Chinese firms hold important roles in the processing and manufacturing of several strategic material chains, while the United States seeks greater domestic and allied capacity. Europe also pursues strategic projects to reduce vulnerability. Governments may use grants, loans, procurement commitments or trade policy to encourage investment. But announcing dozens of projects does not prove that every facility is financed, permitted, built or commercially viable. Progress must be measured at the project level.
Companies sometimes diversify sourcing through partner countries rather than moving production fully home. This can reduce reliance on one jurisdiction while preserving economies of scale. Trade restrictions can also redirect material flows, raise prices or prompt stockpiling. Their ultimate effects depend on product categories and enforcement details. A nuanced article examines incentives as well as unintended consequences rather than describing the supply chain as a simple two-country contest.
A manufacturer’s practical resilience strategy
A producer dependent on one mineral can map the full chain from ore origin to finished input. Identify whether apparently separate suppliers rely on the same refiner or shipping route. Evaluate inventory buffers, dual sourcing, recycling options and alternative designs where technically feasible. Each solution costs money: holding inventory ties up working capital, new suppliers may charge more and product redesign requires qualification. The goal is not perfect independence but manageable exposure to predictable disruptions.
Investors evaluating a mining or refining project should study ore quality, processing yield, environmental permits, energy cost, financing and customer contracts. A headline saying a company discovered a valuable deposit can overstate immediate commercial value. Mining development and chemical refining are operational businesses, not merely map coordinates.
Track five stages, not just the headlines
A useful project dashboard separates exploration and resource estimates, feasibility and permits, construction and financing, commissioning, and actual qualified sales. Record the expected products and named off-take customers only when confirmed. Cross-check corporate presentations with regulatory disclosures and government releases. A supply-chain article built this way gives readers a way to assess claims of progress without treating every government announcement as finished production.
For a broad trade context, consult the World Trade Organization and official national geological or industrial agencies. The strategic contest is fundamentally about dependable industrial inputs at acceptable cost, not simply who can point to the largest mine.
Critical-minerals questions in context
Does discovering a mineral deposit make a country self-sufficient?
No. The project still needs extraction, processing, qualified production, transport and downstream manufacturing. Technical and commercial requirements can create reliance on foreign stages even when raw materials are domestic. The more useful question is how much material reaches a final manufacturer at the required purity and cost.
Can recycling solve shortages quickly?
Recycling can become a meaningful source of material, but collection volumes, chemical recovery rates and product-quality requirements impose limits. Some newer technologies have not yet produced enough end-of-life material to sustain large recovery programs. The economics can also shift with commodity prices. Recycling complements, rather than automatically replaces, responsible primary production.
Why do governments support expensive projects?
Public officials may value resilience, strategic capacity or reduced exposure to geopolitical disruption in addition to short-term profit. Critics can question subsidy cost, environmental impact or effectiveness. A responsible article evaluates project milestones and public commitments without assuming that a strategic label guarantees commercial success.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Critical minerals have become a foreign-policy issue because a small missing input can interrupt production far beyond the mining industry. The strategic question is not simply who owns deposits. It is who can process material to the required standard and deliver the components manufacturers need.
A September 2026 Council on Foreign Relations report describes Chinese export controls covering materials such as gallium and rare earths, alongside related components. The International Energy Agency’s 2026 critical minerals outlook examines supply security, diversification and the policy frameworks needed to support more resilient chains.
These developments help explain why tariff negotiations alone cannot resolve every vulnerability. Lower duties can make trade cheaper, but they do not automatically create processing plants, qualified alternative suppliers or a dependable supply of specialised equipment and skills.
Critical minerals and rare earths are not interchangeable terms
“Critical minerals” is a policy category generally concerned with economic importance and supply risk. Different governments maintain different lists because their industries and vulnerabilities differ. Rare earths are a particular group of elements within the wider materials discussion.
Using the terms interchangeably obscures important differences. Copper, lithium, graphite and individual rare earth elements have different applications, production processes and market structures. A policy that helps one material may do little for another.
The first question in any supply-risk assessment should therefore be specific: which material, in what processed form, for which use? A broad statement that a country has abundant minerals does not show that it can supply the exact input a manufacturer requires at a competitive price and dependable scale.
The chain continues long after extraction
A deposit must be explored, financed, permitted and developed before becoming a mine. Extracted material may then require concentration, chemical processing, refining and fabrication before it becomes useful in a component.
Each stage has its own constraints. A country can possess ore while lacking the facilities to process it. Another can dominate a processing step despite having fewer domestic deposits. Manufacturing capability can be concentrated separately again.
This explains why announcing a new mine does not immediately remove dependence. The project must connect with the rest of the chain. Transport, water, electricity, specialist knowledge and customer qualification all influence whether the output becomes commercially useful. Security depends on functioning industrial systems rather than a list of geological assets.
Export controls differ from tariffs
A tariff changes the cost of importing a covered product. An export control can instead affect whether a shipment is permitted, which buyer receives it or what documentation is required. The business consequences can therefore differ substantially.
Even where trade remains legally possible, licensing uncertainty may complicate production schedules. A manufacturer needs to know not only the expected price but whether a required input will arrive before existing stocks are exhausted.
The September reporting on US–China tariff adjustments illustrates why broader trade relief and unresolved mineral questions can coexist. Specific tariff or licensing obligations should be checked against current official measures; a diplomatic headline is not a substitute for a product-level compliance determination.
Why replacing a supplier takes time
Industrial components must meet performance specifications. A new source may need testing, certification and changes to production processes before it can be used reliably. Material with the same general name is not always an interchangeable input.
Buyers also need evidence of consistent quality across repeated deliveries. A successful sample is different from reliable production at scale. Depending on the application, failure can create expensive recalls, equipment damage or interruptions elsewhere in the chain.
This creates a timing problem for policy. Governments may want rapid diversification, while factories cannot responsibly switch overnight. The useful measure is qualified, commercially available alternative supply—not merely announcements, memoranda or theoretical capacity. Progress should be judged by what customers can actually buy and use.
Low prices can make diversification harder
Cheap materials help current consumers but can weaken the investment case for new suppliers. A proposed project must cover construction, financing and operating costs over a long period. If prices fall sharply, lenders and buyers may become reluctant to commit.
The resulting dilemma is strategic. Governments may want additional suppliers for resilience while private firms prefer the lowest available cost. Without a durable commercial arrangement, a diversification project can struggle even when policymakers describe it as essential.
Possible responses include long-term purchase agreements, financing support or other policy mechanisms. Each has trade-offs. Support can improve investment certainty but may transfer risk to taxpayers or customers. A credible programme should explain the vulnerability being addressed and how success will be measured beyond the initial funding announcement.
What mineral-producing countries want
Countries with deposits often want more than royalties from extraction. They may seek local processing, jobs, infrastructure and technical expertise. Their bargaining power depends on the quality of resources, investment conditions and the availability of competing suppliers.
Building downstream industry can add value, but it requires more than restricting raw exports. Reliable energy, skilled workers, environmental management and access to customers influence whether domestic processing becomes competitive.
For countries balancing relationships with Washington and Beijing, diversification can be a diplomatic strategy as well as an industrial one. However, signing agreements with several partners does not automatically eliminate dependence. Financing, equipment and final customers may still connect a project closely to one external market.
Recycling and substitution help, with limits
Recycling can return useful material to the supply chain and reduce demand for newly mined inputs. Its contribution depends on collection systems, recovery technology and the availability of products reaching the end of their lives.
A rapidly expanding technology sector may not yet generate enough retired equipment to meet all its material needs through recycling. Different products also vary in how easily their materials can be separated and recovered economically.
Substitution offers another route. Engineers may redesign products to use less of a constrained input or replace it with another material. That can reduce one vulnerability while changing performance, cost or dependence elsewhere. The practical question is whether the substitute works in the specific application, not whether an alternative exists in principle.
A business checklist that goes beyond supplier nationality
A company should map the origin of critical inputs beyond its immediate vendor. A supplier located in one country may rely on processing or components from another. Several apparently independent vendors can share the same upstream bottleneck.
The next step is to identify which inputs have few qualified alternatives and how long replacement would take. Inventory decisions can then reflect actual exposure rather than broad geopolitical anxiety. Holding more stock of every material may consume cash without solving the most serious problem.
Contracts, customer obligations and technical requirements should be considered together. A procurement team may find an alternative source that engineering cannot approve in time. Coordinating those functions early creates a more realistic picture of resilience and the cost of improving it.
Supplier concentration should also be revisited after mergers, ownership changes or new subcontracting arrangements. A company may believe it has diversified because it buys through several distributors, while those distributors purchase from the same processor. Resilience depends on independent capacity upstream, not simply the number of names in a purchasing database.
What a durable agreement would need to accomplish
A useful diplomatic agreement would improve predictability as well as market access. Businesses benefit from clear procedures, transparent licensing and dependable implementation. The text of an announcement matters less if operational delays remain unresolved.
Longer-term resilience requires additional work: commercially viable capacity, qualified suppliers, infrastructure and technical skills. Those investments usually outlast the news cycle and may span changes of government. Their durability depends on credible economics as well as political commitment.
The US–China critical minerals contest is therefore a test of industrial capability as much as negotiating power. A trade deal can reduce immediate pressure and create room for investment. Lasting security comes from a supply chain that continues to function when one route, supplier or diplomatic relationship becomes less reliable.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Mining
Southeast Asia’s Critical Minerals Power Play: Can ASEAN Avoid Choosing Between China and the US?
Southeast Asia is becoming one of the most important battlegrounds in the global critical-minerals economy. But the region’s biggest opportunity may not be choosing between Washington and Beijing—it may be using competition between the two to build more valuable industries at home.
The global race for critical minerals is entering a new phase.
Rare earth elements, nickel, graphite, cobalt, copper and other strategic materials are no longer simply commodities extracted from the ground. They are essential inputs for electric vehicles, batteries, semiconductors, renewable-energy systems, advanced electronics, artificial intelligence infrastructure, aerospace and defence.
That transformation has made mineral supply chains a central issue in economic and national security policy.
China remains deeply embedded in global processing and manufacturing networks, while the United States and its partners are investing heavily in alternative supply chains. For Southeast Asia, this competition creates both geopolitical pressure and an unusual economic opportunity.
Rather than viewing the US-China contest as a forced choice, ASEAN economies can potentially use it to attract capital, technology, processing expertise and manufacturing investment from multiple partners.
The critical question is no longer simply who controls Southeast Asia’s minerals?
It is increasingly:
Who helps Southeast Asia capture the greatest share of the value created from those minerals?
Why Critical Minerals Matter More Than Ever
The strategic importance of critical minerals is being driven by several simultaneous technological trends.
Electric vehicles require large quantities of battery materials and other minerals. Renewable-energy systems depend on metals used in grids, generators, batteries and permanent magnets. Semiconductor and advanced-electronics manufacturing requires materials including gallium, germanium, silicon, indium and rare earth elements.
The International Energy Agency’s Global Critical Minerals Outlook 2026 says demand for several important minerals is expected to continue expanding strongly toward 2040. Demand for nickel, graphite and rare earths is projected to grow substantially, while copper is expected to experience particularly large absolute demand growth because of its role in electricity networks.
The IEA also warns that the concentration problem has not disappeared.
In 2025, the average share of the largest refining country across key energy minerals reached approximately 70%, up from 68% in 2020. Indonesia has become dominant in nickel refining, while China remains the leading refiner for many other critical materials.
That concentration gives Southeast Asia an increasingly important role because the region contains both mineral resources and growing manufacturing capabilities.
Southeast Asia Is Not a Single-Mineral Story
One of the weaknesses of simplistic critical-minerals discussions is treating Southeast Asia as if it were dependent on one commodity.
It is not.
Different countries occupy different positions across the mineral value chain.
Indonesia: The Nickel Giant
Indonesia is the region’s most consequential critical-minerals player because of its enormous nickel industry.
According to the IEA’s Southeast Asia Energy Outlook 2026, Indonesia accounted for approximately 63% of global mined nickel production.
Nickel is particularly important for stainless steel and certain lithium-ion battery chemistries.
But Indonesia’s strategy goes beyond simply exporting ore.
The country has pursued downstream industrialisation policies designed to encourage domestic processing and attract investment in smelting, refining and battery-related manufacturing.
This changes the economics dramatically.
Exporting raw ore captures one layer of the value chain.
Mining, processing, refining, producing battery materials and eventually manufacturing components or finished products can capture substantially more.
Indonesia therefore represents an important test case for whether mineral-rich developing economies can convert geological advantages into industrial capabilities.
Malaysia: A Rare-Earth Processing Hub
Malaysia occupies a different position.
Its importance comes particularly from rare-earth processing.
The IEA’s 2026 critical-minerals assessment identifies Malaysia as one of the countries contributing to diversification in rare-earth refining.
The agency notes that increases in Malaysian production, together with new projects in the United States, helped reduce rare-earth refining concentration between 2023 and 2025.
This is strategically important because diversification is not simply about discovering another mine.
The bigger bottleneck is often what happens after mining.
Ore must be separated, refined and converted into materials suitable for industrial applications.
The difference between a mining economy and an advanced mineral-processing economy can therefore be enormous.
Malaysia’s experience demonstrates why Southeast Asian countries can potentially become important not only as resource suppliers but also as processing locations.
Myanmar and the Rare-Earth Supply Chain
Myanmar also occupies an important position in the regional rare-earth ecosystem.
The IEA’s Southeast Asia Energy Outlook 2026 estimates that Myanmar accounted for just under 20% of global mined rare-earth supply and more than 40% of heavy rare-earth elements.
That makes the country strategically significant despite the region’s broader diversification ambitions.
The supply chain, however, is complex.
A mineral can be mined in one country, transported to another for processing and ultimately incorporated into components manufactured somewhere else.
This interconnected structure means that no single country necessarily controls the entire value chain.
That is precisely where Southeast Asia’s leverage can emerge.
The Philippines and the Nickel Opportunity
The Philippines is another major player in regional nickel supply.
The country already occupies an important position in the global nickel market, while its geographic location places it close to major Asian manufacturing economies.
The strategic challenge is determining how much value remains inside the country.
If a resource-rich country exports primarily unprocessed material, much of the economic value is generated elsewhere.
If it develops refining, precursor materials, battery components and manufacturing capabilities, more of the economic activity can potentially remain domestically.
That is the broader lesson emerging across Southeast Asia.
China Still Has Enormous Supply-Chain Advantages
Any analysis of Southeast Asia’s options must acknowledge the scale of China’s existing position.
According to the U.S. Geological Survey’s 2026 China minerals profile, China accounted for approximately 71% of global mined rare-earth production in 2024.
The USGS also reports that China accounted for around 87% of rare-earth processing.
Those figures illustrate why replacing China’s role cannot happen simply by opening new mines.
Processing technology, equipment, technical expertise, logistics, financing and downstream manufacturing all matter.
The IEA’s Global Critical Minerals Outlook 2026 makes this distinction particularly important: announced mining projects outside dominant producers are growing, but refining and downstream manufacturing capacity remains much more constrained.
In other words:
The world may be able to diversify mines faster than it can diversify processing.
That creates an opportunity for Southeast Asia.
The US Is Trying to Build Alternative Supply Chains
Washington’s interest in Southeast Asia is not limited to obtaining raw materials.
The broader objective is supply-chain resilience.
The United States and its partners have been attempting to develop alternative sources for rare earths, battery materials and other strategic minerals.
The CSIS analysis of rare-earth export restrictions describes the substantial disruption created by China’s 2025 rare-earth restrictions and the subsequent US effort to develop alternative supply chains.
This competition gives Southeast Asian governments more bargaining space.
If Washington wants diversified mineral supplies while Beijing wants continued access to regional resources and manufacturing networks, Southeast Asian governments have an incentive to negotiate around investment, technology transfer, infrastructure and local value creation.
The strategic opportunity therefore extends beyond mining rights.
ASEAN’s Bigger Opportunity: Move Up the Value Chain
ASEAN itself has recognised the importance of developing mineral industries beyond extraction.
The ASEAN Minerals Cooperation Action Plan 2026–2030 explicitly identifies sustainable development of extractive industries and expanded upstream-to-downstream minerals and metals cooperation as regional priorities.
That is significant.
The next stage of Southeast Asia’s mineral strategy could involve building connected regional capabilities:
Mining → Processing → Refining → Components → Manufacturing → Recycling
Instead of every country attempting to build an entire supply chain independently, ASEAN economies could specialise in different stages.
Indonesia, for example, has enormous nickel capabilities.
Malaysia has experience in rare-earth processing and advanced manufacturing.
The Philippines has substantial nickel resources.
Vietnam possesses important rare-earth resources and manufacturing capabilities.
Singapore contributes finance, logistics, services and regional headquarters capabilities.
Thailand has developed automotive manufacturing infrastructure.
This creates the possibility of a regional ecosystem rather than isolated national projects.
The Real US-China Competition Is About Industrial Capacity
The US-China contest is often presented as a geopolitical struggle over who gets access to minerals.
But the deeper competition is about industrial capacity.
A mine alone does not produce an electric vehicle.
A rare-earth deposit alone does not produce a permanent magnet.
Nickel ore alone does not produce a battery.
The value is created through a chain of technological and industrial processes.
That is why the IEA warns that mining projects outside dominant suppliers are advancing faster than refining and downstream manufacturing.
For Southeast Asia, this is perhaps the most important strategic lesson.
Owning the resource is only the beginning.
Owning the processing technology, engineering expertise, manufacturing infrastructure and intellectual property can be considerably more important.
Why Southeast Asia Should Avoid Excessive Dependence on Any Single Partner
Diversification is not necessarily about replacing Chinese investment with American investment.
Nor is it about rejecting Chinese participation.
A more resilient model could involve multiple investment and technology partners.
China can contribute substantial manufacturing capabilities, supply-chain expertise and capital.
The United States can provide technology, financing, market access and strategic partnerships.
Japan and South Korea are already deeply integrated into Asian manufacturing networks.
Australia is a major resource supplier and has growing interest in regional critical-minerals cooperation.
Europe also has an interest in diversifying mineral supply chains.
For Southeast Asian governments, the economic objective can therefore be to encourage competition among potential partners rather than lock the region into a single dependency.
The Environmental Problem Cannot Be Ignored
There is, however, another side to the critical-minerals boom.
Mining and refining can create substantial environmental pressures.
Nickel processing, rare-earth separation and other mineral-intensive industries can require large amounts of energy and water while generating waste and emissions.
The long-term competitiveness of Southeast Asian mineral projects will therefore depend partly on environmental standards.
This is particularly important because major buyers increasingly care about the carbon footprint and traceability of industrial materials.
A country that can provide responsibly produced minerals with reliable environmental certification may eventually have an advantage over a low-cost producer with weak standards.
The region’s industrial strategy therefore has to balance three objectives:
Resource security.
Economic value creation.
Environmental sustainability.
Recycling Could Become Southeast Asia’s Next Strategic Advantage
Mining is not the only route to supply security.
Recycling could eventually reduce dependence on newly extracted minerals.
The IEA estimates that secondary supply could make an increasingly important contribution to mineral markets through 2040.
Battery recycling, magnet recycling and recovery of strategic metals from industrial waste could become increasingly important as the installed base of electric vehicles, batteries, electronics and renewable-energy equipment grows.
Southeast Asia’s expanding manufacturing base could give the region an opportunity to develop recycling industries alongside new mineral-processing projects.
That would create a more circular industrial model.
Instead of:
Mine → export → import finished product
the model could become:
Mine → process → manufacture → use → recycle → reuse
Such a system would potentially strengthen regional supply security while reducing pressure on new extraction.
What Could Southeast Asia Gain?
If Southeast Asian countries successfully move up the critical-minerals value chain, the economic impact could extend far beyond mining revenues.
Potential gains include:
- Higher-value manufacturing
- Skilled industrial employment
- Technology transfer
- Battery and EV production
- Semiconductor-related manufacturing
- Export diversification
- Greater foreign direct investment
- New logistics and infrastructure demand
- Growth in engineering and technical services
- Development of recycling industries
- Greater bargaining power with major economies
The objective should therefore not be to maximise mineral exports.
It should be to maximise the economic value generated per tonne of mineral resource.
The Biggest Risk: Becoming a New Raw-Material Dependency
There is an important paradox.
Southeast Asia could reduce dependence on China’s mineral supply chains while simultaneously becoming overly dependent on foreign companies for extracting its own resources.
That would solve one supply-chain problem while creating another.
A sustainable strategy requires local capabilities.
Governments therefore have an incentive to negotiate investment agreements that encourage:
- Local processing
- Workforce development
- Technology transfer
- Domestic supplier networks
- Research and development
- Environmental monitoring
- Transparent contracts
- Infrastructure investment
- Local manufacturing
The objective is not to prevent foreign participation.
It is to ensure that foreign capital helps create domestic industrial capacity.
Can ASEAN Turn Geopolitical Competition Into Economic Leverage?
The answer depends heavily on execution.
A 2026 analysis from the National University of Singapore’s Lee Kuan Yew School of Public Policy highlights Southeast Asia’s growing importance in critical minerals while examining the challenge of maintaining strategic autonomy amid intensifying US-China competition.
That strategic autonomy does not necessarily mean neutrality in every dispute.
Instead, it can mean preserving the ability to make economic decisions based on national and regional interests.
For ASEAN, that could translate into welcoming investment from multiple countries while avoiding excessive concentration in any single supply chain.
The Next Battle Will Be Over Processing, Not Just Mining
The global critical-minerals race is entering a new stage.
The first phase was about finding and extracting resources.
The second phase is about processing.
The third will increasingly involve advanced materials, components, manufacturing and recycling.
This distinction is crucial for Southeast Asia.
The region already possesses many of the raw ingredients required for a major role in the global mineral economy.
Indonesia has extraordinary nickel production.
Malaysia is strengthening its rare-earth processing position.
The Philippines remains an important nickel supplier.
Myanmar occupies a significant position in heavy rare earths.
Vietnam has substantial rare-earth potential.
Meanwhile, ASEAN’s manufacturing infrastructure connects the region to some of the world’s most important electronics, automotive and technology supply chains.
The question is whether those advantages can be integrated into a higher-value regional industrial strategy.
Southeast Asia’s Strategic Choice Is Bigger Than US vs China
The US-China critical-minerals competition is unlikely to disappear.
If anything, critical minerals are becoming more closely linked to technology policy, national security, industrial policy and the energy transition.
But Southeast Asian economies do not necessarily need to treat the competition as a binary choice.
Their greater opportunity may lie in diversification.
China’s enormous processing and manufacturing capabilities are difficult to replace quickly.
The United States and its partners are investing in alternative supply chains.
Japan, South Korea, Australia and Europe also have strong incentives to secure reliable mineral supplies.
That creates multiple potential sources of capital, technology and market access.
The strategic opportunity for ASEAN is therefore to ask a different question:
What can each partner contribute to Southeast Asia’s transition from mineral supplier to advanced industrial producer?
The answer could determine whether the region merely participates in the next critical-minerals boom—or becomes one of its major beneficiaries.
Bottom Line
Southeast Asia’s critical-minerals advantage is not simply the amount of nickel, rare earths or other resources beneath its soil.
Its real advantage is the combination of resources, manufacturing, logistics, growing energy demand, strategic geography and access to multiple global investment partners.
China’s dominance of processing gives Beijing significant influence, while US-led diversification creates additional demand for alternative supply chains.
For ASEAN economies, the opportunity is to use that competition to build processing capacity, attract technology, develop skilled workforces and establish downstream manufacturing.
The ultimate prize is not becoming the world’s cheapest source of minerals.
It is becoming a region that captures a much larger share of the value created from them.
In the emerging global critical-minerals economy, the countries that control the highest-value stages of the supply chain—not necessarily those that simply extract the most ore—are likely to have the greatest economic leverage.
Sources and Further Reading
- International Energy Agency — Global Critical Minerals Outlook 2026
- International Energy Agency — Global Critical Minerals Outlook 2026: Market Overview
- International Energy Agency — Southeast Asia Energy Outlook 2026
- International Energy Agency — Rare Earth Elements
- U.S. Geological Survey — China Mineral Industry Profile
- ASEAN — Minerals Cooperation Action Plan 2026–2030
- CSIS — Rare Earth Export Restrictions One Year Later
- National University of Singapore — Southeast Asia and Critical Minerals
- FULCRUM — Southeast Asia’s Room for Manoeuvre in Critical Minerals
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
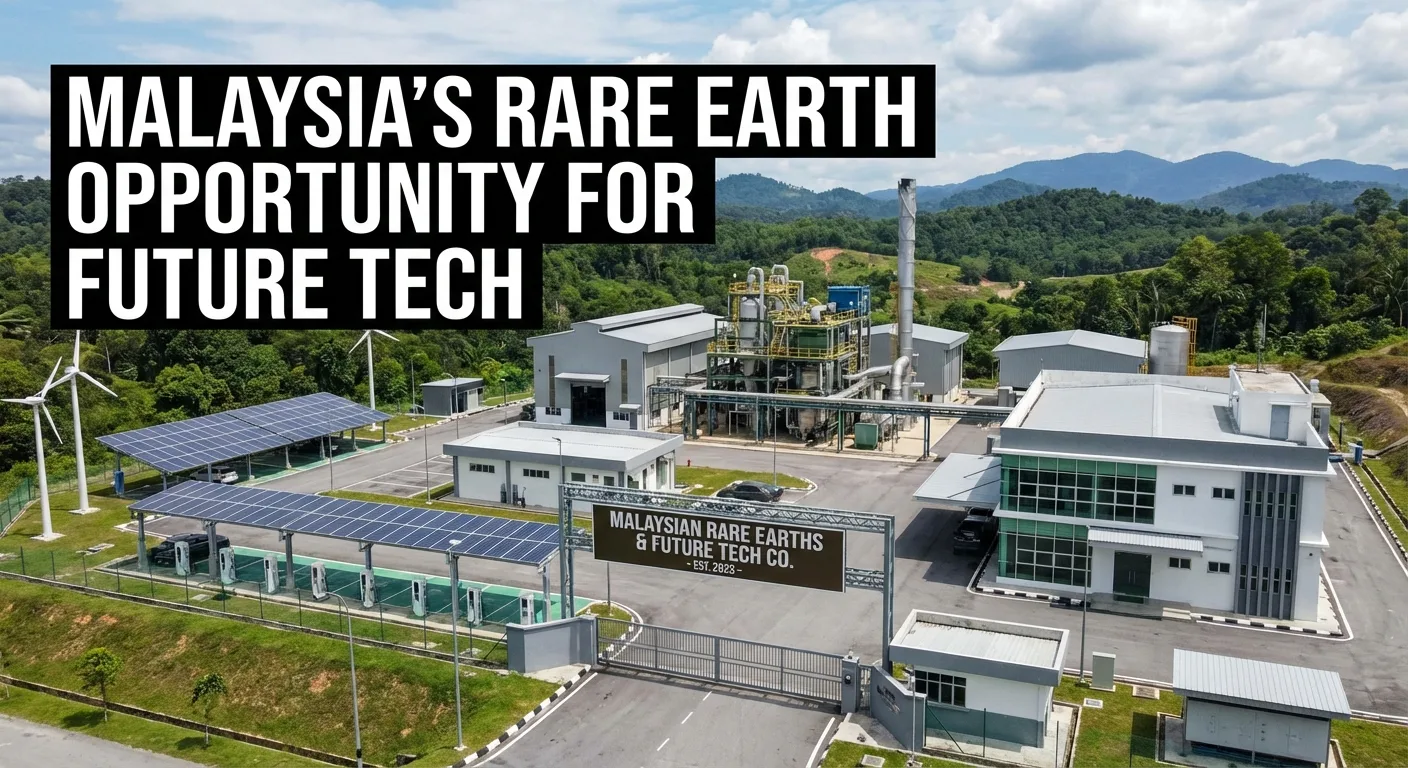
Malaysia is quietly running one of the more consequential balancing acts in global industrial policy: negotiating rare earth technology, investment and offtake terms with Washington, Tokyo, Seoul, Canberra, Paris and Beijing at the same time, according to Rare Earth Exchanges. The country is betting that its combination of geology, existing separation capacity and a firm export-ban policy can convert it from a mining afterthought into the leading non-Chinese node in the rare earth supply chain — without becoming exclusively dependent on any single partner.
The Asset at the Center of It
The Lynas Advanced Materials Plant (LAMP) in Kuantan, Pahang, is the largest rare earth separation facility outside China, and in early 2026 it became strategically load-bearing: the US Department of Defense signed a preliminary $96 million supply agreement with Lynas, according to industry tracker Rare-Earth-Mining.com. Malaysia’s broader reserve base is estimated at 16.1 to 18.2 million tonnes of non-radioactive rare earth elements, and Kuala Lumpur is targeting $3 billion in direct rare earth revenue by 2030 under its National Industry Plan — a target expected to draw roughly MYR 100 billion (about $25 billion) in new investment, per analysis from Lundgreen’s Investor Insights.
Lynas itself is expanding aggressively: expansion costs at its Malaysia operations have risen to roughly A$294 million as of 2026, reflecting the underlying difficulty of the chemistry involved — rare earth separation requires hundreds of sequential solvent-extraction stages, each demanding precise control, according to Discovery Alert’s capital-markets coverage. The company is also partnering with South Korea’s JS Link on a MYR 600 million magnet manufacturing facility in Pahang, per Lundgreen’s reporting — a move toward the downstream metals-and-magnets capability that separation alone doesn’t provide.
The Policy Lever: No Raw Exports
Malaysia’s core negotiating leverage is a standing ban on exporting unprocessed rare earth elements. Investment, Trade and Industry Minister Tengku Zafrul Abdul Aziz has reaffirmed the policy even amid a new minerals cooperation framework with the US, insisting the goal is local value creation rather than serving as a raw-material feeder to outside industries, according to Quest Metals. That stance forces every foreign partner — including Washington — to invest in Malaysian processing capacity if they want access to Malaysian rare earth output at all.
It’s a policy with real friction attached, however. A separation plant without downstream metals, alloys and magnet capability remains, in the framing used by Rare Earth Exchanges, only a partial victory — true technological sovereignty requires domestic engineers able to operate, modify and replicate the processes independently, not merely receive transferred technology.
The Timeline Problem
Malaysia’s own mining moratorium complicates the picture. According to The Edge Malaysia, a phased environmental and socio-economic study covering pre-mining (2024–25), mining (2026–27) and post-mining (2028–29) periods means no new mining will occur in permanent forest reserves until at least 2029 — even as midstream processing facilities are expected to reach full operation only around 2027–2030. That leaves a multi-year window in which Malaysia’s upstream supply and downstream capacity are both still ramping, even as geopolitical demand for a non-Chinese alternative is immediate.
A comprehensive sourcing guide from Malaysia4u frames the licensing history as instructive: Lynas’s operating permit has been threatened, extended, renegotiated and finally extended again for ten more years as of 2026 — evidence, the guide argues, that rare earth licenses in Malaysia function as politically negotiated assets rather than fixed regulatory clearances. Any investor or policymaker treating Kuantan as a settled, low-risk supply node is missing that history.
Why This Is a Six-Country Story, Not a US-China One
Most coverage frames rare earths as a binary US-versus-China contest. Malaysia’s actual position is multipolar: it holds observer status in the US-led Minerals Security Partnership, supplies Japan’s JOGMEC programs (Japan is Lynas Kuantan’s largest single customer), and has been recognized by the EU’s Critical Raw Materials Act as a strategic third-country partner — while continuing quiet engagement with Beijing, which still dominates roughly 70% of global rare earth production. That simultaneous multi-power courtship, more than any single supply deal, is what makes Kuantan the most contested industrial site in Southeast Asia in 2026.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

IREN Stock in 2026: AI Cloud Growth, Bitcoin Transition and the Risks Investors Miss

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Peso Mexicano vs Dólar Estadounidense: A Practical USD/MXN Guide for October 2026

Is the Stock Market Open on Columbus Day 2026? NYSE, Nasdaq and Bonds Explained

Concert Ticket Prices in 2026: Dynamic Pricing, Fees and How to Buy Safely

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025