
Opinion
Ukraine’s Oil Strike Strategy: Can It Break Russia’s War Economy?

Ukraine’s expanding campaign against Russian oil infrastructure is revealing vulnerabilities in Vladimir Putin’s war economy. Yet damaging refineries is only the beginning. The real challenge is converting industrial disruption into sustained economic and diplomatic leverage.
A New Front in the War of Attrition
Wars are often decided not simply by what armies capture, but by what governments can continue to afford. Ukraine appears increasingly determined to test that proposition against Russia’s oil industry.
On October 15, Ukrainian drones struck a refinery in Russia’s Ryazan region, roughly 300 kilometres southeast of Moscow. The attack followed a short-lived pause in strikes on energy infrastructure, which Kyiv said it had observed despite continued Russian attacks. The Associated Press reported that Russian authorities acknowledged the strike, while Reuters documented its growing diplomatic significance.
The episode illustrates an uncomfortable reality for Moscow: Russia’s enormous geographical depth no longer guarantees the security of its industrial heartland.
But it also reveals Ukraine’s dilemma. The more effectively Kyiv disrupts Russian refining, the more it risks upsetting international petroleum markets and frustrating governments anxious about fuel prices.
The distinction matters. Ukraine is not physically destroying Russia’s vast underground oil reserves. Its campaign primarily targets the infrastructure that transforms crude into usable fuels, stores petroleum products and moves energy supplies.
Ukraine’s strategic achievement will therefore not be measured by the number of refineries hit, but by whether their disruption changes Russia’s capacity and willingness to continue the war.
That is a much more demanding test.
Why Oil Remains Central to Russia’s War Economy
Russia’s dependence on hydrocarbons is one of the enduring contradictions of its geopolitical position.
Energy exports provide Moscow with international revenues, fiscal resources and relationships with countries that have declined to join Western sanctions. At the same time, the concentration of valuable industrial facilities creates vulnerabilities that military spending alone cannot eliminate.
The scale of the industry is considerable. According to a September 2026 International Energy Agency assessment, Russia operates 32 major refineries with approximately 6.5 million barrels per day of installed processing capacity.
Yet the country’s oil wealth is not interchangeable with its refining capacity.
A barrel of crude underground is a geological resource. A barrel extracted is a marketable commodity. A barrel refined into diesel, aviation fuel or gasoline serves a different economic purpose.
Disrupting one stage does not automatically eliminate the others.
That distinction becomes especially important when considering the Russian treasury.
On October 15, Reuters calculated that Russian federal oil and gas tax receipts were expected to reach approximately one trillion roubles in October, an increase of 10 percent from a year earlier.
The projected rise largely reflected scheduled tax payments, while elevated global petroleum prices provided further support.
Yet Reuters also estimated that cumulative oil and gas revenue from January through October would be 14 percent lower than in the corresponding period of 2025.
The apparently contradictory figures point to a central challenge in evaluating Ukraine’s campaign: Russia can suffer industrial losses while still collecting substantial revenues.
A financially strained war economy is not necessarily a financially defeated one.
Ukraine’s Drone Campaign Is Changing the Industrial Battlefield
The expansion of Ukraine’s long-range drone operations represents one of the war’s most consequential technological developments.
For a country facing an adversary with substantially greater territory, industrial resources and conventional military power, relatively inexpensive unmanned aircraft offer a means of imposing costs far beyond the immediate battlefield.
The consequences are increasingly measurable.
The IEA’s September analysis found that Russian refinery throughput fell to approximately 3.8 million barrels per day in June 2026, roughly 30 percent below its level a year earlier and the lowest in more than two decades.
Reported gasoline output had declined by about 20 percent compared with 2025 levels, while estimated diesel production was down nearly 30 percent.
The agency also reported that a Russian refinery was struck, on average, once every three days during the first eight months of 2026.
These findings from the IEA’s detailed refinery assessment are important because they describe an increasingly persistent problem rather than a collection of isolated attacks.
There is a difference between damaging an installation and repeatedly preventing it from operating normally.
When refineries are forced into recurring cycles of shutdown, repair and restart, the economic burden extends beyond lost fuel production. Maintenance schedules become unreliable, replacement equipment becomes more valuable, and operators must devote greater resources to protection.
The IEA reports that damage to complex secondary processing units can require six to eight months to repair, compared with considerably shorter periods for some less complicated refinery equipment.
The effects of such damage are not necessarily limited to the individual facility. Even if Russia can continue extracting and exporting crude, its ability to supply refined petroleum products domestically and internationally may deteriorate.
This helps explain why Moscow has repeatedly restricted fuel exports in an effort to preserve domestic supplies.
The tactical appeal to Ukraine is evident: sustained disruption can force Russia to defend industrial assets hundreds or even thousands of kilometres from the front.
As the Center for Strategic and International Studies has argued, the conflict increasingly involves competing strategies of long-range attrition, with Ukraine seeking to expose Russian economic vulnerabilities while Moscow continues to attack Ukraine’s infrastructure.
Neither side can assume that success against infrastructure automatically produces success in negotiations.
The Problem With Trying to Bankrupt an Oil Power
The economic logic of Ukraine’s strategy is powerful, but its limitations are frequently underestimated.
It is tempting to assume that every damaged Russian refinery represents a proportional reduction in Moscow’s ability to finance its military operations.
Oil markets do not operate so conveniently.
Consider three separate effects.
First, reduced refining capacity can diminish Russia’s production of diesel, gasoline and aviation fuel, creating domestic shortages and reducing the availability of exportable petroleum products.
Second, Moscow may attempt to redirect some crude that can no longer be processed domestically toward international buyers, provided extraction, storage, transport and export capacity allow it.
Third, disruptions to global petroleum supplies may increase prices, helping Russia earn more on barrels it continues to sell.
The third possibility is particularly uncomfortable for those hoping that infrastructure attacks will rapidly exhaust Russia’s finances.
If world prices rise sufficiently, a producer can sometimes earn more from fewer exported barrels. The outcome depends on discounts, freight costs, sanctions, taxes, volumes and buyers’ willingness to continue trading.
Russia’s ability to take advantage of that mechanism is constrained, however.
On October 13, Reuters reported that shipping costs for Russian Urals crude from western ports to India had reached record levels. Some one-way voyages from the Black Sea were costing between $27 million and $30 million, compared with about $19 million in September.
Those costs illustrate another source of pressure on Moscow: high oil prices do not necessarily translate into equally high net export earnings.
Still, the distinction between damage to refining assets and losses to government finances must remain at the center of the argument.
The decisive economic question is not how much refining capacity Ukraine can temporarily disable, but how much sustained revenue, productive capacity and strategic flexibility Russia ultimately loses.
An effective assessment would track refinery throughput, petroleum-product exports, repair durations, crude export volumes, domestic fuel availability, tax receipts and transport costs over several months.
Judged against those measures, the campaign has already imposed meaningful disruption. It has not yet demonstrated that energy strikes alone can force an end to Russia’s military campaign.
The Global Energy Dilemma: When Pressure on Russia Hurts Everyone
Ukraine’s oil strategy now operates within a global energy market already destabilized by conflict in the Middle East.
The IEA’s October 2026 Oil Market Report described severe pressure on diesel markets as disruptions in Russian and Middle Eastern supplies compounded one another.
The agency reported that global diesel exports in September were approximately 700,000 barrels per day lower than a year earlier.
That decline cannot be attributed entirely to Ukraine’s strikes. Middle Eastern disruptions, shipping constraints and refinery problems elsewhere have played major roles.
Indeed, this distinction is essential to understanding the diplomatic controversy.
Some political leaders may find it expedient to blame expensive fuel on Ukrainian attacks. But the market evidence points to multiple interacting causes rather than a single campaign.
The wider economic consequences are substantial.
Diesel powers freight transport, agricultural equipment, construction machinery and important industrial activities. When it becomes scarce or expensive, the effects spread into food prices, business costs and household budgets.
Oil-importing economies are particularly vulnerable. Countries with limited fiscal capacity may struggle to protect consumers from sustained increases in fuel prices.
The geopolitical consequences also reach India and China, major destinations for Russian crude exports.
For New Delhi, access to Russian petroleum must be balanced against international sanctions exposure, shipping costs and domestic energy security. Beijing similarly has commercial incentives to maintain supply diversity while avoiding excessive dependence on any single geopolitical relationship.
These countries are not merely observers of Ukraine’s campaign. Their purchasing decisions influence how effectively economic pressure on Russia can be sustained.
Europe faces its own dilemma: maintaining support for Ukraine while controlling energy costs that can weaken industrial competitiveness and political confidence.
For Kyiv, the danger is that the success of its operations may become an argument used by others to restrain them.
A strategy designed to increase Russia’s economic pain could also create political pressure on Ukraine if its perceived contribution to global fuel scarcity becomes substantial.
That does not automatically make the strategy misguided. It means its economic effects must be judged globally, not only within Russia.
Washington’s Changing Position Complicates Kyiv’s Calculations
The most immediate strategic risk may not lie in Russian retaliation, but in the uncertain position of the United States.
The October 2026 controversy over refinery strikes has exposed the extent to which energy policy and diplomacy are becoming intertwined.
President Donald Trump has criticized Ukraine’s renewed attacks on Russian refineries and sought arrangements to increase Russian diesel supplies.
The Financial Times reported Zelenskyy’s rejection of pressure to abandon the campaign, while Reuters on October 17 detailed the broader deterioration in relations between Washington and Kyiv.
The dispute extends beyond rhetoric.
Ukraine remains dependent on external military equipment, intelligence cooperation and technological systems. Diplomatic confrontation with a major security partner therefore carries practical risks.
On October 18, Reuters reported that U.S. Secretary of State Marco Rubio had outlined a period of up to 60 days for reviewing the economic implications of Russia-related sanctions and tariffs temporarily waived by Washington.
The same report discussed a separate arrangement intended to increase Russian diesel supplies to international markets.
For Ukraine, these developments create a paradox.
Kyiv is trying to raise the economic cost of Russia’s invasion at a moment when Washington is seeking additional Russian fuel supplies to relieve market pressure.
Europe’s willingness to maintain sanctions, financial assistance and military support consequently becomes even more important.
Yet Ukraine should not confuse political frustration with strategic independence.
An effective campaign must consider not only what can be damaged inside Russia, but also what diplomatic support could be endangered outside it.
The objective should be to preserve the greatest possible pressure on Moscow while maintaining the international coalition necessary to sustain Ukraine’s defense.
That requires political judgment as well as military capability.
The Question of Legality and Civilian Harm
Any serious examination of energy warfare must confront a question that strategic calculations often neglect: when does an industrial facility become a lawful military target?
The answer is not that every installation contributing economically to an enemy state may automatically be attacked.
Under international humanitarian law, civilian objects are protected unless they qualify as military objectives under the applicable rules.
The International Committee of the Red Cross explains that a facility’s contribution to an adversary’s general economic strength is not, by itself, sufficient to establish that it is a lawful military target.
A specific facility must make an effective contribution to military action, and its destruction, capture or neutralization must offer a definite military advantage in the circumstances.
Even when infrastructure qualifies as a military objective, the rules governing distinction, proportionality and precautions remain applicable.
Refineries and fuel depots may have both civilian and military functions. Their legal status cannot therefore be determined simply by describing them as components of the Russian economy.
The foreseeable effects on workers, nearby communities and essential civilian services must also be considered.
Oil facilities carry environmental hazards that can extend beyond the immediate site of an attack. Fires, spills and contamination may create consequences lasting much longer than the military operation itself.
The ICRC’s guidance on the environment and warfare emphasizes that environmental harm is relevant to the legal assessment of military operations.
These principles must apply consistently.
Russia’s long-running attacks on Ukraine’s electricity and heating infrastructure have exposed civilians to severe humanitarian risks. Kyiv’s own operations must nevertheless be assessed under the same applicable humanitarian protections.
On October 18, Zelenskyy alleged that Russian forces had attacked Ukraine’s energy and oil-and-gas sectors 76 times in the preceding week, according to Reuters. The figure was presented as the Ukrainian president’s account, not as an independently established count.
Russia’s responsibility for launching the full-scale invasion in 2022 remains a fundamental part of the conflict’s context. But that responsibility does not eliminate the legal obligations governing individual attacks by either belligerent.
Ukraine’s international standing is strengthened, not weakened, when its military strategy is accompanied by a credible commitment to civilian protection.
Why Even Successful Strikes May Not Produce a Strategic Breakthrough
Ukraine’s approach contains an understandable assumption: economic pressure can alter the incentives of a government engaged in a prolonged war.
History suggests that such pressure can matter. It does not establish that disruption will necessarily bring concessions.
Authoritarian governments may shift economic burdens onto households, ration scarce supplies, redirect resources from civilian consumption and suppress political opposition.
Russia also retains considerable adaptation capacity.
The IEA reports that Russian refiners have responded to repeated damage through accelerated repairs, postponed maintenance and the reactivation of idle processing equipment.
Sanctions may complicate the replacement of specialized machinery, but they do not make all repairs impossible.
Nor does public inconvenience necessarily translate into political opposition capable of changing Kremlin decisions.
There is another complication: Ukraine itself is acutely vulnerable to energy disruption.
According to Reuters reporting on October 12, the country relies almost entirely on imported fuel because its own refineries have been destroyed or seriously damaged during the war.
Logistical difficulties, rising prices and interruptions to transport routes have consequently created additional risks for Ukraine’s domestic diesel supplies.
The result is a conflict in which both countries are attempting to impose costs on the other’s energy system while remaining vulnerable to the same international markets.
An energy truce could, in principle, reduce those mutual losses. But it would require credible commitments, verification and enforcement mechanisms.
As a recent CSIS assessment examines, the effectiveness of reciprocal restraint depends on the broader military and bargaining environment.
A ceasefire that removes Ukraine’s leverage while leaving Russian attacks or other coercive capabilities intact would be strategically unbalanced.
Equally, an unlimited campaign of mutual infrastructure destruction could deepen civilian suffering without bringing either side closer to a negotiated settlement.
A sustainable strategy must therefore be capable of both imposing costs and supporting diplomacy.
The Real Test: Converting Disruption Into Leverage
Ukraine’s attacks on Russian oil facilities have demonstrated an important reality: even a major energy power cannot assume that its industrial infrastructure is insulated from a technologically adaptable opponent.
Russia’s refineries are under pressure. Domestic fuel supplies have been disrupted. Repair and protection costs are rising. Moscow is being forced to devote attention and resources to threats far from the conventional front.
Ukraine does not need to exhaust Russia’s oil reserves to expose the vulnerabilities of its war economy. But it does need to turn temporary disruption into durable strategic advantage.
These are genuine strategic gains.
But Ukraine should resist the illusion that economic warfare offers a rapid substitute for military endurance, effective sanctions, dependable alliances or a credible diplomatic settlement.
The most effective approach would combine pressure on militarily relevant energy infrastructure with international economic restrictions, careful monitoring of Russia’s fiscal condition and sustained diplomatic coordination.
Success should be measured against a clear standard: whether the campaign reduces Moscow’s ability to sustain aggression and improves Ukraine’s prospects for a secure peace.
If disruption merely rearranges Russian export flows while high oil prices protect Kremlin revenues, the strategic gains may prove smaller than the physical damage suggests.
If, however, sustained attacks increase repair costs, constrain critical fuel supplies, reduce Russia’s net energy earnings and reinforce international diplomatic pressure, the cumulative effect could become significant.
The danger is mistaking the visibility of an explosion for the permanence of an economic loss.
That is the difference between attacking an industry and changing the course of a war.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Crude prices and diesel prices follow related but different supply chains. Refinery capacity, transport and product inventories help explain the gap. Original research October 12; updated October 15, 2026. Verify newer developments before publication.
Reuters reported on October 15 that ongoing conflict and maritime disruptions continue to influence oil and energy prices. Avoid equating a crude price change with an identical movement in retail diesel prices. Source. Historical material further below is contextual and must not be mistaken for a live quotation or price.
What changed since the original research cutoff
Reuters reported on October 15 that ongoing conflict and maritime disruptions continue to influence oil and energy prices. Avoid equating a crude price change with an identical movement in retail diesel prices. The publication date and observation time are crucial: market prices, competition results and government announcements cannot be extrapolated from an earlier snapshot. A more useful reader question is what remains current today and what requires verification at the moment of a financial or travel decision. The new development should be checked against the primary or contemporary reference rather than assumed from an older headline.
What is happening and why readers are searching
Energy prices are back near the center of the inflation debate in October 2026. Associated Press reporting on October 12 described elevated crude prices and market reactions to proposed Russian diesel purchases against the backdrop of international tensions. The existence of political announcements does not establish that contracted volumes have already arrived or reduced retail pump prices. Sources: Associated Press energy coverage and International Monetary Fund.
The important context competitors can overlook
Crude oil and diesel are related but different markets. Refineries need the right feedstock, sufficient capacity, suitable shipping routes and compliance with regulations. A region can have adequate crude yet experience tight middle-distillate supply because of refinery disruptions, inventory shortages or freight bottlenecks. Trucking, agriculture and industrial logistics transmit fuel costs into goods prices with different time lags. For primary-source checks and current reporting, see Associated Press energy coverage and World Trade Organization. The key distinction is separate crude headlines from finished fuel supply.
A practical way to use this information
Follow refinery output, diesel inventories, freight costs and wholesale spreads alongside Brent and WTI. For consumers, compare a weekly average fuel price with the prior month rather than inferring national inflation from one service station. For businesses, test whether fuel surcharges are formula-based or discretionary. The honest answer to “will diesel get cheaper?” depends on both delivered product supply and demand.
Why lower crude does not always mean cheaper diesel
| Link in the chain | Potential bottleneck | What to watch |
|---|---|---|
| Crude extraction | Disruption or policy limits | Delivered crude availability |
| Transportation | Tanker capacity and insurance | Freight and route costs |
| Refining | Unit outages and product mix | Diesel output and margins |
| Distribution | Storage, taxes and local supply | Wholesale-to-retail lag |
A political agreement may improve expectations before physical shipments change inventories. This is why fuel inflation coverage should distinguish a possible future supply release from barrels or diesel cargoes actually received.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Is diesel price the same as oil price? No. Refining capacity, product inventories, shipping and local taxes create substantial differences.
Do policy announcements lower pump prices immediately? Not necessarily; delivery timing and wholesale markets determine pass-through.
Crude oil and diesel are connected—but not the same commodity
Crude oil is a refinery input, while diesel is one of several refined fuels that emerge from processing it. A change in the crude benchmark affects refiners’ input costs, but the price of diesel also depends on local refinery capacity, maintenance, fuel specifications, product inventories and transport availability. A refinery can have access to crude and still be unable to produce enough diesel for its market. Conversely, a region with healthy diesel inventories may see pump prices respond more slowly to an international crude rally. This is why headlines about a political agreement to increase crude supply should not automatically promise immediate relief to truck drivers.
The difference between the selling price of a refined product and its crude input cost is often discussed through a refining margin or crack spread. These spreads fluctuate as product demand and refinery utilization change. They can rise sharply when product supply is constrained even if crude prices soften. For readers, a graph of Brent oil alone cannot explain every regional diesel price move. Look for product-level benchmarks and inventory data alongside the crude quotation.
How a fuel shock enters broader inflation
Fuel costs affect more than motorists. Trucks carry food, building materials and consumer goods; farm machinery uses diesel; ships and industrial users depend on related refined energy products. Higher transport costs can flow into freight contracts and eventually shelf prices, but the timing depends on contract terms, profit margins and competition. Airlines typically face jet-fuel costs rather than road-diesel costs, so a service article should not present every transport sector as using the same product. Households also respond differently depending on commuting needs and heating arrangements.
An energy shock can affect headline inflation quickly through direct fuel prices, while broader price pressure may take longer. Central banks often distinguish volatile energy components from measures intended to capture underlying inflation, but persistent energy increases can influence expectations and wage negotiations. Reporting should describe the channels without claiming a specific change in CPI before the statistics agency releases its measured result.
Four scenarios for October’s energy market
First, an announced supply deal may be implemented and deliver usable fuel after shipping, payment and compliance arrangements are complete. Second, the deal may be delayed or revised, leaving near-term product shortages unresolved. Third, refinery disruptions or shipping bottlenecks may offset additional crude availability. Fourth, weakening economic demand could reduce consumption even while geopolitical risks remain elevated. In each case, the direction of the crude price, diesel price and pump price may differ. A scenario is a tool for reasoning, not an assertion that an event has occurred.
The distinction is especially important when headlines mention a government statement or preliminary agreement. A political declaration is not physical delivery; a cargo nomination is not necessarily a completed arrival; and the arrival of crude is not itself the production of road-ready diesel. For verification, identify the party making the statement, the product and volume involved, the destination, the delivery window and any relevant sanctions or trade restrictions.
What businesses can do about fuel exposure
A delivery company can examine route optimization, fleet efficiency and whether fuel surcharges fairly reflect current costs. A manufacturer can review freight contracts, supplier concentration and inventory policies. A small retailer should calculate how much of total expense is actually fuel-sensitive before raising prices across the board. Households may compare total travel costs, not just the pump-price sign. All these responses have tradeoffs: extra inventory ties up cash, and hedging instruments can create their own financial risks.
For investors, energy producers, refiners and transport companies can react very differently to the same headline. An oil producer may benefit from higher crude prices while an airline faces higher fuel costs. A refiner’s profitability can depend more on product margins than on crude’s absolute level. Sector labels should never substitute for analyzing actual business exposure.
A practical fuel-price monitoring dashboard
Compare Brent and WTI crude with regional diesel benchmarks, refinery utilization, relevant inventories, transport constraints and local tax structures. Date each observation and note whether figures are daily prices, weekly averages or monthly reports. The U.S. Energy Information Administration is a useful primary source for U.S. energy data. Official inflation releases help distinguish the impact on consumer prices from speculative claims about a future inflation wave.
A good oil-and-diesel article protects readers from two oversimplifications: that every supply announcement immediately changes retail prices, and that every increase in crude produces an identical change in diesel. The market has multiple stages, each with its own constraints and lags.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
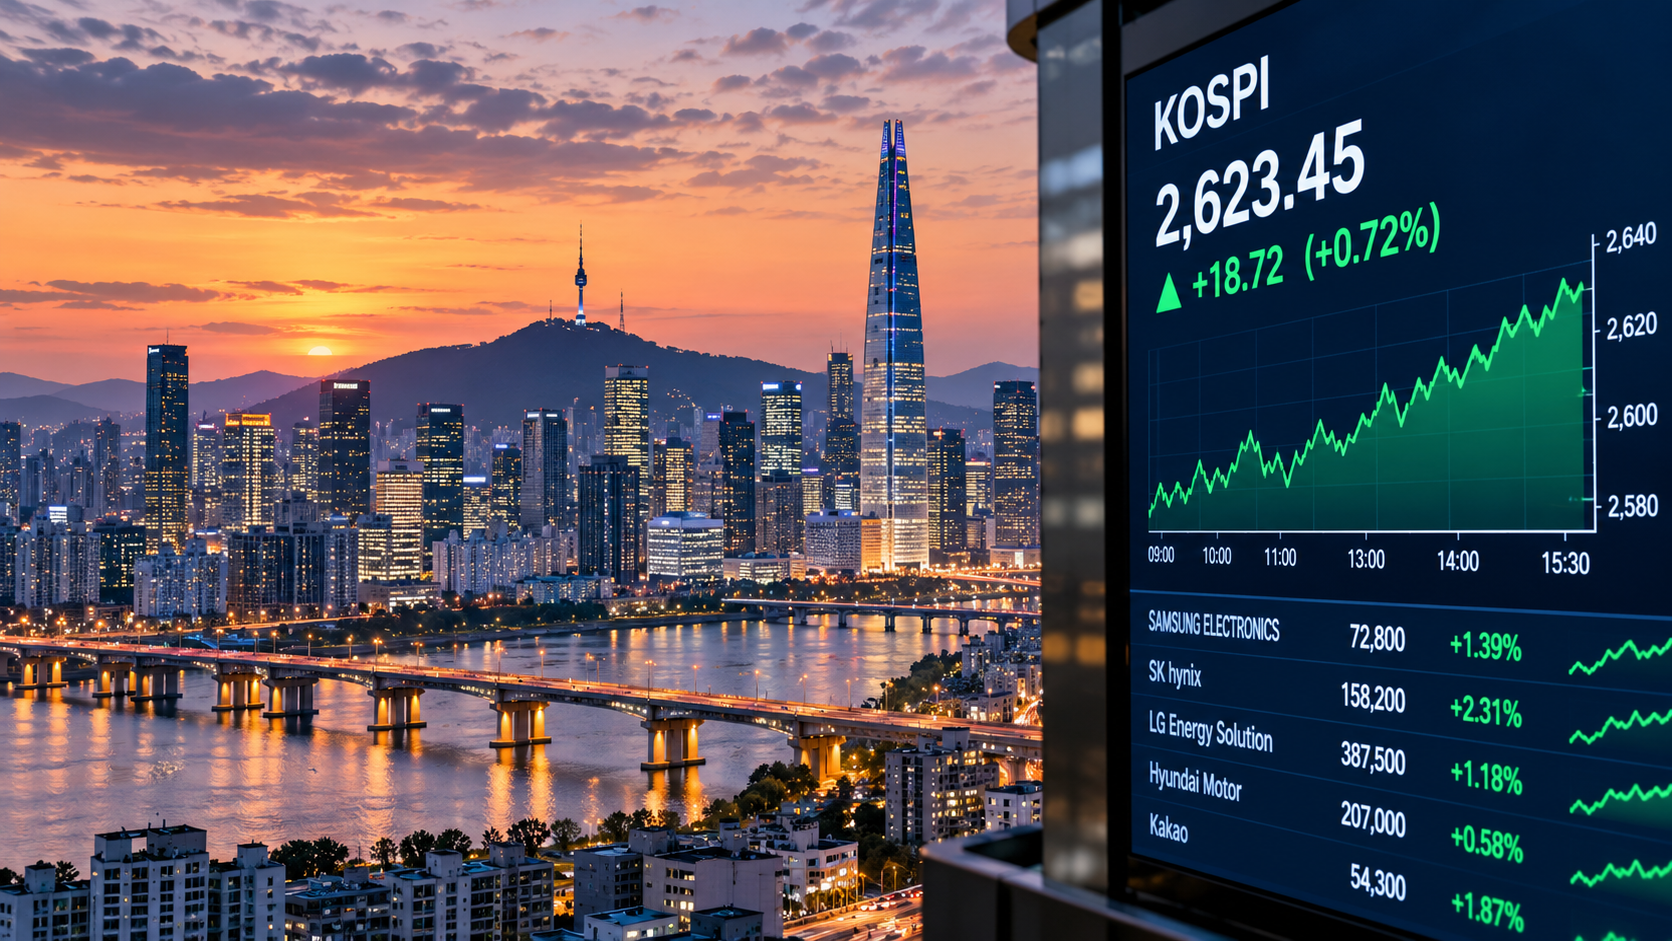
The KOSPI is sensitive to major Korean semiconductor companies but is not solely a technology index. Currency, sector weights and market timing all matter. Original research October 12; updated October 15, 2026. Verify newer developments before publication.
On October 15 the KOSPI closed 7.57% lower at 5,554.22 amid an AI-linked chip stock selloff. Reuters reported that the exchange invoked its circuit breaker during the session. This verified update supersedes earlier articles dated October 12. Source. Historical material further below is contextual and must not be mistaken for a live quotation or price.
What changed since the original research cutoff
On October 15 the KOSPI closed 7.57% lower at 5,554.22 amid an AI-linked chip stock selloff. Reuters reported that the exchange invoked its circuit breaker during the session. This verified update supersedes earlier articles dated October 12. The publication date and observation time are crucial: market prices, competition results and government announcements cannot be extrapolated from an earlier snapshot. A more useful reader question is what remains current today and what requires verification at the moment of a financial or travel decision. The new development should be checked against the primary or contemporary reference rather than assumed from an older headline.
What is happening and why readers are searching
South Korea’s KOSPI has become a vivid measure of the rewards and risks of the AI hardware trade. October 12 coverage described a sharp retracement following an exceptionally strong first-half rally, with Samsung Electronics and SK Hynix central to market moves. Such reporting should be read in context: a dramatic fall after a large rise can coexist with a positive year-to-date performance. Sources: Business Insider KOSPI analysis and Barron’s chip market coverage.
The important context competitors can overlook
KOSPI is a stock-market index, not an ETF or an individual security. Investors considering exposure must distinguish the benchmark from specific Korea funds, currency hedges and concentrated semiconductor holdings. Global demand for high-bandwidth memory matters, but so do chip pricing, inventory cycles, capital spending and the Korean won. A profitable technology cycle can still produce volatile stock returns when valuations already anticipate perfection. For primary-source checks and current reporting, see Business Insider KOSPI analysis and Reuters chip demand report. The key distinction is explain memory-chip concentration and cross-market exposures.
A practical way to use this information
When comparing KOSPI with Taiwan’s Taiex or the Nasdaq, choose the same observation window and clearly state whether figures are measured in local currency or dollars. Look at index sector weights and market breadth, not simply at a sensational one-day percentage. For an American investor, foreign-market trading hours and fund tracking error also complicate any quick “buy the dip” narrative.
Three comparisons KOSPI commentary should not mix
First, a single-session decline measures the change from yesterday’s close, not the loss from a peak. Second, a drawdown from the year’s high measures market turbulence even if the year-to-date return stays positive. Third, an unhedged foreign investor’s return includes the Korean won against the investor’s home currency. The three numbers can point in different directions without contradiction.
The October 12 Barron’s chip coverage highlights why semiconductor movements deserve separate treatment. Do not infer exact index performance from the percentage declines of two chipmakers.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Why does KOSPI move when AI chips move? Large South Korean technology and memory-chip companies have a significant influence on the index.
Can an index decline while remaining up for the year? Yes; the result depends on the starting point and the comparison period.
Why the KOSPI is not simply a technology index
The Korea Composite Stock Price Index tracks a broad share market, but its largest constituents can make semiconductor news disproportionately important. Changes in expectations for memory-chip prices, AI servers and electronics demand can therefore move the benchmark even when many other domestic businesses are relatively stable. Investors should distinguish an index-weighting effect from evidence that every Korean company is experiencing the same change. A semiconductor downturn may hurt export earnings while benefiting downstream buyers from lower component costs.
South Korea also has globally connected manufacturing companies in automobiles, batteries, chemicals, shipbuilding and industrial equipment. Domestic policy, currency trends and global trade conditions can influence those industries differently. An accurate KOSPI explainer identifies which sector is moving the index on a particular day and whether the move is broad or concentrated. It does not describe a drop in two heavyweight stocks as proof that the entire economy has entered a recession.
The role of memory chips and AI infrastructure
High-bandwidth memory, often discussed as HBM, supports demanding AI workloads by providing fast data movement near computing accelerators. Demand for HBM can benefit qualified suppliers, but profitability depends on manufacturing yields, product mix, competition and customer pricing. Traditional DRAM and NAND markets have different end uses and inventory cycles. Consequently, a headline saying “AI chip prices are rising” may be too broad to explain a specific company’s quarter. Investors should read product-level commentary rather than infer that every semiconductor shipment is equally profitable.
Semiconductor investment is cyclical. Producers commit to costly factories and equipment well before their output reaches the market. Strong prices may encourage capacity expansion; later, oversupply can compress margins. Conversely, constrained manufacturing capacity can support pricing for some products while limiting volume growth. Supply contracts and technical qualifications can smooth these fluctuations, but they do not eliminate them. A balanced market note includes both demand and the possibility of supply catching up.
Currency and foreign-investor flows
A U.S. investor buying a Korean equity fund has at least two kinds of exposure: share-price changes and the won-dollar exchange rate, unless the investment vehicle hedges currency. Imagine Korean shares rise 8% in local currency while the won weakens against the dollar. The dollar return can be lower than 8%; if the currency move is sufficiently large, the investor could lose money in dollars despite positive local share performance. Conversely, won appreciation can amplify a local gain. Actual fund returns also reflect fees and tracking differences.
Foreign investors may shift exposure because of global interest rates, geopolitical developments or a change in the perceived risk of Asian hardware companies. Those flows can intensify short-term price moves. They are not evidence of a permanent change in Korea’s long-run technological position. Readers should use closing data in the correct time zone and avoid comparing Seoul’s closing prices with a U.S. market snapshot several hours later as if the observations were simultaneous.
A five-indicator KOSPI dashboard
Track the index’s performance both year to date and from its recent peak; those windows answer different questions. Review market breadth to see whether small and medium-sized companies are sharing the move. Compare major semiconductor companies’ operating outlooks, particularly memory product mix and capacity plans. Note the won-dollar rate and the direction of foreign-investor flows. Finally, monitor relevant global AI capital-spending announcements—but distinguish an announced customer budget from actual Korean supplier orders.
For long-term investors, the right comparison may be a diversified Asian equity portfolio rather than an individual semiconductor name. Country, sector and currency concentration can compound one another. A fund that appears to provide “international diversification” may still be heavily exposed to the global technology investment cycle. Review the fund’s holdings and benchmark methodology rather than relying on the label alone.
What the index cannot tell you
A sharp daily selloff is a price signal, not a direct measurement of factory production, employment or household welfare. Nor does a strong rally guarantee that companies will meet aggressive earnings expectations. The meaningful question is whether the latest market price embeds assumptions about AI demand, semiconductor margins and currency conditions that remain plausible. Different investors will answer that question differently depending on horizon and tolerance for losses.
For a useful daily update, record the exact KOSPI close, its point and percentage change, the date in Korea, and the principal named contributors. Without that basic timestamp discipline, even an otherwise informed global-market article can unintentionally misstate what happened.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Energy prices are back near the center of the inflation debate in October 2026. Associated Press reporting on October 12 described elevated crude prices and market reactions to proposed Russian diesel purchases against the backdrop of international tensions. The existence of political announcements does not establish that contracted volumes have already arrived or reduced retail pump prices. Sources: Associated Press energy coverage and International Monetary Fund.
The important context competitors can overlook
Crude oil and diesel are related but different markets. Refineries need the right feedstock, sufficient capacity, suitable shipping routes and compliance with regulations. A region can have adequate crude yet experience tight middle-distillate supply because of refinery disruptions, inventory shortages or freight bottlenecks. Trucking, agriculture and industrial logistics transmit fuel costs into goods prices with different time lags. For primary-source checks and current reporting, see Associated Press energy coverage and World Trade Organization. The key distinction is separate crude headlines from finished fuel supply.
Crude prices and diesel prices follow related but different supply chains. Refinery capacity, transport and product inventories help explain the gap. Research cutoff: October 12, 2026; confirm developing facts before publication.
A practical way to use this information
Follow refinery output, diesel inventories, freight costs and wholesale spreads alongside Brent and WTI. For consumers, compare a weekly average fuel price with the prior month rather than inferring national inflation from one service station. For businesses, test whether fuel surcharges are formula-based or discretionary. The honest answer to “will diesel get cheaper?” depends on both delivered product supply and demand.
Why lower crude does not always mean cheaper diesel
| Link in the chain | Potential bottleneck | What to watch |
|---|---|---|
| Crude extraction | Disruption or policy limits | Delivered crude availability |
| Transportation | Tanker capacity and insurance | Freight and route costs |
| Refining | Unit outages and product mix | Diesel output and margins |
| Distribution | Storage, taxes and local supply | Wholesale-to-retail lag |
A political agreement may improve expectations before physical shipments change inventories. This is why fuel inflation coverage should distinguish a possible future supply release from barrels or diesel cargoes actually received.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Is diesel price the same as oil price? No. Refining capacity, product inventories, shipping and local taxes create substantial differences.
Do policy announcements lower pump prices immediately? Not necessarily; delivery timing and wholesale markets determine pass-through.
Crude oil and diesel are connected—but not the same commodity
Crude oil is a refinery input, while diesel is one of several refined fuels that emerge from processing it. A change in the crude benchmark affects refiners’ input costs, but the price of diesel also depends on local refinery capacity, maintenance, fuel specifications, product inventories and transport availability. A refinery can have access to crude and still be unable to produce enough diesel for its market. Conversely, a region with healthy diesel inventories may see pump prices respond more slowly to an international crude rally. This is why headlines about a political agreement to increase crude supply should not automatically promise immediate relief to truck drivers.
The difference between the selling price of a refined product and its crude input cost is often discussed through a refining margin or crack spread. These spreads fluctuate as product demand and refinery utilization change. They can rise sharply when product supply is constrained even if crude prices soften. For readers, a graph of Brent oil alone cannot explain every regional diesel price move. Look for product-level benchmarks and inventory data alongside the crude quotation.
How a fuel shock enters broader inflation
Fuel costs affect more than motorists. Trucks carry food, building materials and consumer goods; farm machinery uses diesel; ships and industrial users depend on related refined energy products. Higher transport costs can flow into freight contracts and eventually shelf prices, but the timing depends on contract terms, profit margins and competition. Airlines typically face jet-fuel costs rather than road-diesel costs, so a service article should not present every transport sector as using the same product. Households also respond differently depending on commuting needs and heating arrangements.
An energy shock can affect headline inflation quickly through direct fuel prices, while broader price pressure may take longer. Central banks often distinguish volatile energy components from measures intended to capture underlying inflation, but persistent energy increases can influence expectations and wage negotiations. Reporting should describe the channels without claiming a specific change in CPI before the statistics agency releases its measured result.
Four scenarios for October’s energy market
First, an announced supply deal may be implemented and deliver usable fuel after shipping, payment and compliance arrangements are complete. Second, the deal may be delayed or revised, leaving near-term product shortages unresolved. Third, refinery disruptions or shipping bottlenecks may offset additional crude availability. Fourth, weakening economic demand could reduce consumption even while geopolitical risks remain elevated. In each case, the direction of the crude price, diesel price and pump price may differ. A scenario is a tool for reasoning, not an assertion that an event has occurred.
The distinction is especially important when headlines mention a government statement or preliminary agreement. A political declaration is not physical delivery; a cargo nomination is not necessarily a completed arrival; and the arrival of crude is not itself the production of road-ready diesel. For verification, identify the party making the statement, the product and volume involved, the destination, the delivery window and any relevant sanctions or trade restrictions.
What businesses can do about fuel exposure
A delivery company can examine route optimization, fleet efficiency and whether fuel surcharges fairly reflect current costs. A manufacturer can review freight contracts, supplier concentration and inventory policies. A small retailer should calculate how much of total expense is actually fuel-sensitive before raising prices across the board. Households may compare total travel costs, not just the pump-price sign. All these responses have tradeoffs: extra inventory ties up cash, and hedging instruments can create their own financial risks.
For investors, energy producers, refiners and transport companies can react very differently to the same headline. An oil producer may benefit from higher crude prices while an airline faces higher fuel costs. A refiner’s profitability can depend more on product margins than on crude’s absolute level. Sector labels should never substitute for analyzing actual business exposure.
A practical fuel-price monitoring dashboard
Compare Brent and WTI crude with regional diesel benchmarks, refinery utilization, relevant inventories, transport constraints and local tax structures. Date each observation and note whether figures are daily prices, weekly averages or monthly reports. The U.S. Energy Information Administration is a useful primary source for U.S. energy data. Official inflation releases help distinguish the impact on consumer prices from speculative claims about a future inflation wave.
A good oil-and-diesel article protects readers from two oversimplifications: that every supply announcement immediately changes retail prices, and that every increase in crude produces an identical change in diesel. The market has multiple stages, each with its own constraints and lags.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Ukraine’s Oil Strike Strategy: Can It Break Russia’s War Economy?

Power Grid Emergency Across 13 States? What the October 2026 PJM Order Actually Says

Oil Prices October 2026: Iran Conflict, Shipping and Inflation Risks

TSMC Stock in October 2026: AI Chip Demand, Earnings and Valuation Risks

Stock Market Crash 2026: What the Inflation and AI Selloff Means

Student Loans and the 2026 Midterms: SAVE Plan Deadlines and Borrower Choices

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

OP-ED:The AI Race Has No Single Winner — And Pakistan Must Choose Its Own Future

VA Disability Rates Increase 2027: The Confirmed 3.6% COLA Explained

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

World’s Largest Economies: Ranking the Top Global Powers

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Asian Stock Markets 2026: Japan, China, Pakistan & More

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

SpaceX IPO 2026: History’s Biggest Stock Debut?

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Oil Prices 2026: Inside the Hormuz Crisis That Won’t End

IMF Reports 2026: What the Latest Data Means for the Global Economy

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025