
Analysis
One year of Trump tariffs: What has changed and what’s next for South-east Asia?

Nguyen Thi Lan still remembers the WhatsApp messages that flooded her factory floor in Bac Ninh on the morning of April 3, 2025. The production manager at a Foxconn supplier had stayed up watching the “Liberation Day” announcement from Washington—and by dawn, she was fielding panicked calls from buyers in Texas who wanted to know whether to rush their orders before new tariffs hit. Within seventy-two hours, her factory was running double shifts. Twelve months later, that same plant exported more electronics than ever before. Her story, repeated across thousands of workshops from Hanoi to Ho Chi Minh City, encapsulates the central paradox of one year of Trump tariffs on South-east Asia: a region initially earmarked for punishment has, in many respects, survived—and in some corners, even thrived.
But survival is not the same as security. Twelve months on from Liberation Day, the landscape for Trump tariffs in South-east Asia has been permanently altered by front-loaded shipments, bilateral deal-making, a landmark Supreme Court ruling, and now a fresh wave of legal uncertainty. The full reckoning is still unfolding—and what comes next may be more consequential than the original shock.
The Initial Shock: Liberation Day Hits ASEAN Where It Hurts
On April 2, 2025, President Donald Trump invoked the International Emergency Economic Powers Act (IEEPA) to impose a 10% baseline tariff on most US imports, layered with country-specific “reciprocal” duties tied to bilateral trade surpluses. South-east Asia bore a disproportionate share of the pain.
The headline rates were staggering:
- Cambodia: 49%
- Vietnam: 46%
- Thailand: 36%
- Indonesia: 32%
- Malaysia: 25%
- Philippines: 17%
- Singapore: 10%
For a region whose economic model is built on export-led growth and deep integration into US-bound supply chains, the numbers were existential. Vietnam’s exports to the United States had reached $136.6 billion in 2024, representing roughly 30% of its GDP. Cambodia’s garment sector, which ships nearly 40% of its textiles to American retailers, faced near-annihilation at a 49% rate. Thailand’s automotive and electronics exporters confronted the steepest competitive shock in a generation.
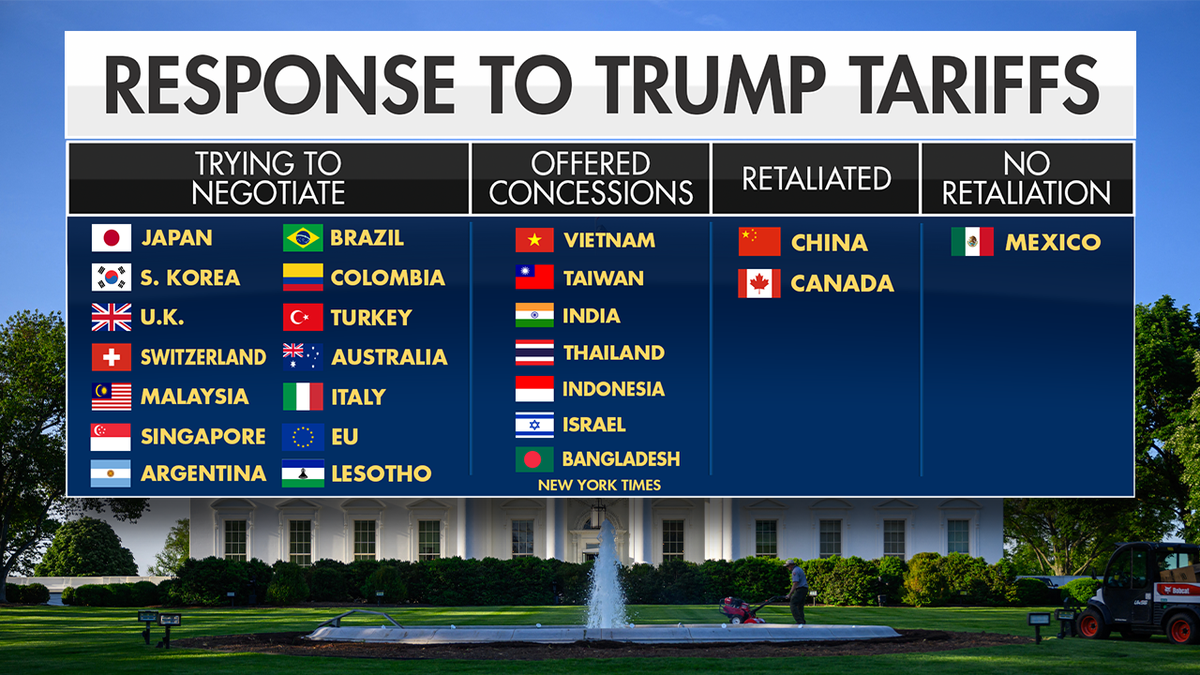
The CSIS Southeast Asia programme noted that Vietnam, Indonesia, Thailand, and Cambodia were among the first governments to reach out to Washington after the announcement, reflecting acute exposure rather than diplomatic formality. ASEAN’s collective response was muted—Malaysian Prime Minister Anwar Ibrahim urged a unified bloc response, but cohesion proved elusive when every nation was simultaneously scrambling for bilateral favours.
How South-east Asia Weathered the Storm
The region’s initial survival relied on four mechanisms that, taken together, blunted the sharpest edges of the tariff regime.
Front-loading and shipment surges were the first reflex. US importers, facing an April 9 implementation date on the reciprocal tariffs, accelerated orders en masse. Vietnam’s Hai Phong port logged record throughput in Q2 2025. According to PwC’s Vietnam economic update, total exports grew by approximately 16% in the first nine months of 2025, led by electronics, computers and components—up 46% year-on-year—with the US accounting for roughly 32% of total exports throughout. Some of this was inventory stuffing; buyers pulled forward months of orders to beat the tariff clock. It worked—temporarily.
The ninety-day pause bought critical breathing room. Within a week of Liberation Day, Trump suspended the reciprocal tariffs after claiming over 75 countries had sought negotiations. That window became the region’s dealmaking season.
Sector exemptions provided a structural lifeline, especially for technology. Under heavy lobbying from Apple, Nvidia, and other US tech giants, consumer electronics—including laptops, smartphones and components—were carved out of the reciprocal tariff regime. This was quietly transformative for Malaysia and Vietnam, where semiconductor and electronics exports constitute the bulk of trade flows. The Lowy Institute estimates that Malaysia’s effective US tariff rate in late 2025 was approximately 11%—far below its headline 19% rate—precisely because electronics, its dominant export, remained largely exempt.
Bilateral deals followed in rapid succession. By October 2025, the US had announced trade agreements with Cambodia and Malaysia and framework deals with Thailand and Vietnam at the ASEAN summit. These deals collectively covered approximately $323 billion in US-ASEAN trade—about 68% of the two-way total. The resulting tariff rates, 19% for most ASEAN exporters and 20% for Vietnam, were far higher than pre-Liberation Day levels, but dramatically lower than the initial shock rates—and, critically, lower than the 145% still applied to Chinese goods.
The deals had teeth beyond tariffs. Cambodia and Malaysia agreed to adopt US tariff schedules on third countries—a thinly veiled anti-China clause. Vietnam committed to cracking down on transshipment, accepting a punitive 40% levy on goods rerouted from China. Malaysia pledged a $70 billion capital investment fund in the US and commitments to purchase $150 billion in American semiconductors, aerospace components and data centre equipment over the life of the deal.
The Supreme Court Ruling: Game Changer or New Uncertainty?
The most dramatic chapter of this twelve-month arc arrived not in a trade negotiating room but in the marble halls of the US Supreme Court.
On February 20, 2026, the Court ruled 6-3 in Learning Resources, Inc. v. Trump that IEEPA does not authorise the President to impose tariffs. Chief Justice John Roberts, writing for the majority, held that IEEPA’s authority to “regulate importation” cannot be stretched to encompass the power to tax—a power that, under the Constitution, belongs to Congress alone. “Those words,” Roberts wrote of the two clauses invoked by the administration, “cannot bear such weight.” The ruling invalidated both the reciprocal tariffs and the fentanyl-related duties on China, Canada and Mexico—the entire IEEPA-based tariff architecture.
The Court’s decision was, technically, a victory for free trade. In practice, it was a pivot, not a retreat.
Within hours, Trump signed a proclamation invoking Section 122 of the Trade Act of 1974 to impose a replacement 10% global tariff, which he raised to the statutory maximum of 15% the following day. Section 122, rarely used before this administration, authorises a temporary import surcharge of up to 15% for up to 150 days to address balance-of-payments deficits. Treasury Secretary Scott Bessent stated publicly that combining Section 122, Section 232, and Section 301 tariffs “will result in virtually unchanged tariff revenue in 2026″—an extraordinary admission that the intent was to maintain the same aggregate tax burden through different legal wrappers. The Section 122 tariffs are set to expire on July 24, 2026, unless extended by Congress.
For South-east Asia, the ruling introduced a new problem: legal fragility. Trade deals struck under the IEEPA regime now occupy uncertain territory. If the underlying executive orders were unlawful, the bilateral concessions extracted from ASEAN governments—market access commitments, anti-transshipment pledges, investment promises—rest on a legally contested foundation. Importers who paid an estimated $160–$175 billion in IEEPA tariffs over the past year are now pursuing refunds through the Court of International Trade, though the administration has signalled it does not plan to issue refunds voluntarily.
As the Peterson Institute for International Economics warned, the central challenge for businesses in 2026 is not the level of tariffs—it is their chronic instability. “Rates changed with little notice, creating planning challenges for firms managing inventory, contracts, and payroll,” PIIE analysts noted. The US average effective tariff rate climbed to nearly 17% in 2025—the highest since the early 1930s.
What Has Changed: Supply Chain Reshaping, Winners and Losers
Vietnam: The Reluctant Champion
No country in South-east Asia embodies the tariff era’s contradictions more sharply than Vietnam. Despite facing a 46% headline rate—among the steepest globally—the country’s economy grew 8.02% in 2025, its second-best performance in fifteen years. Exports to the US leapt 28% year-on-year to $153.2 billion, and its trade surplus with Washington hit a record $134 billion—higher, not lower, than before Liberation Day.
The engine of this paradox was electronics. A Bloomberg analysis of customs data published in April 2026 found that Foxconn’s Fukang Technology factory in Bac Ninh alone exported $8.6 billion in electronics—more than double its 2024 value—with most shipments being MacBooks bound for the US. Laptop output in Bac Ninh province surged 130% in 2025; smartphone production rose 39%. Vietnam had quietly surpassed neighboring Southeast Asian competitors as one of the US’s leading chip and electronics suppliers.
The caveat is profound. The same Bloomberg analysis revealed that Fukang’s exports generated only 7.8% of their value in Vietnam—the rest was imported components, primarily from China. The China+1 story is, in many cases, a China+assembly story. As ING analysts noted, imports from China into Vietnam surged 24% year-on-year in the first half of 2025, raising the spectre of rampant transshipment. The 40% tariff on Vietnamese transshipped goods is designed to address exactly this structural problem—but enforcement is technically complex and politically fraught.
Malaysia: Tech’s Safe Harbour
Malaysia’s effective tariff arithmetic worked strongly in its favour. Its headline rate of 19% masked an effective rate of roughly 11% due to electronics exemptions—and the country’s deal with Washington, anchored by that landmark $70 billion investment pledge and semiconductor purchase agreement, secured considerable market access. FDI inflows into Malaysia’s semiconductor ecosystem, already boosted by TSMC’s and Intel’s regional expansions, accelerated through 2025. The East Asia Forum noted that Malaysia’s effective tariff advantage over China has widened substantially, reinforcing its role as a chip-packaging and testing hub.
Cambodia: The Casualty
The story of Cambodia is the story the tariff triumphalists do not tell. As a garment-dominated economy with limited capacity for deals or diversification, Phnom Penh was structurally exposed. Even after negotiations brought its rate from 49% down to 19%, Cambodian textiles—unlike Vietnamese electronics—enjoy no sector exemptions and limited productivity edge. The Lowy Institute found that Chinese consumer imports into Cambodia rose by 128% as deflected Chinese goods flooded the domestic market, squeezing local producers from both directions: losing US market access at the top while competing with surging Chinese imports at the bottom.
Indonesia and Thailand: Cautious Resilience
US goods trade data shows the deficit with Indonesia rose 11% and with Thailand 23% in 2025, with US imports actually rising even under 19-20% tariffs. Indonesia’s September 2025 effective tariff rate was 19.7%—the highest among ASEAN’s five largest trading partners—because its electronics sector, smaller than Malaysia’s or Vietnam’s, captures fewer exemptions. Thailand’s effective rate was around 10%, reflecting both sector exemptions and its July 2025 deal, but automotive and industrial exporters remain squeezed.
What’s Next: The 2026 Outlook
The 150-day Section 122 tariff clock is running. It expires on July 24, 2026—and Congress, which has passed bills disapproving of the IEEPA tariffs, is unlikely to extend them. What happens after July 24 will define South-east Asia’s trade environment for years.
The Section 301 Sword
The most alarming development for the region arrived on March 11, 2026, when the US Trade Representative launched sweeping Section 301 investigations targeting 16 economies for “structural excess manufacturing capacity”. The target list reads like an ASEAN who’s who: Vietnam, Thailand, Malaysia, Cambodia, Indonesia, Singapore. Unlike Section 122, Section 301 tariffs carry no time limit and no statutory cap. They are the administration’s mechanism of choice for permanent, targeted levies—and the March investigations are almost certainly the vehicle for reimposing tariffs equivalent to the now-unlawful IEEPA rates after July.
For governments that signed bilateral deals under the IEEPA regime, this creates a Kafkaesque dilemma: they made substantial concessions in exchange for tariff relief that the Supreme Court has since voided—and they may face equivalent tariffs again through a different legal channel, without the negotiating leverage that initial shock created.
The Diversification Imperative
The one structural positive to emerge from this tumultuous year is the acceleration of diversification. The EU has concluded FTAs with Indonesia and is exploring enhanced cooperation with Malaysia, the Philippines, and Thailand. The CPTPP has expanded its footprint; Indonesia and the Philippines have applied for membership. The China-ASEAN FTA has been upgraded. These initiatives will not replace US demand in the near term—the American market’s $1+ trillion appetite for manufactured goods remains without peer—but they create structural alternatives that previous generations of ASEAN policymakers never fully developed.
The China Tilt Risk
There is also a darker possibility that few in Washington appear to be taking seriously. Every punitive measure that the US imposes on ASEAN without commensurate market access has a mirror-image effect: it pushes the region’s economic centre of gravity toward Beijing. China is already Vietnam’s largest trading partner, Malaysia’s top import source, and the primary origin of investment capital flooding into Cambodia and Myanmar. If the Section 301 investigations result in tariff rates that undo the competitive advantages ASEAN countries have spent a decade cultivating, the incentive to deepen China linkages—on infrastructure financing, digital standards, and supply chain integration—grows commensurately.
Conclusion: The Long Game Has Only Just Begun
One year of Trump tariffs has produced a South-east Asia that is, by most headline metrics, more resilient than anyone predicted in April 2025. Vietnam grew 8%, Malaysia deepened its semiconductor edge, and even Cambodia negotiated its tariff rate down by 30 percentage points. The region demonstrated formidable diplomatic agility.
But the structural uncertainties compounding through 2026—the Section 301 sword hanging over every bilateral deal, the Section 122 expiry cliff, the unresolved refund litigation, and the administration’s demonstrated willingness to use trade as a geopolitical lever for any and all foreign policy goals—mean that celebration is premature. As the Brookings Institution noted, the challenge was never just the size of the tariffs; it was the instability surrounding them that forced businesses to make hiring, pricing and investment decisions in a fog.
For South-east Asia’s policymakers, three imperatives now dominate. First: lock in trade diversification with the EU and CPTPP partners before the next tariff wave hits, reducing the region’s structural vulnerability to a single bilateral relationship. Second: invest urgently in domestic value-add capacity—Vietnam’s 7.8% local content share in its flagship electronics exports is a long-term vulnerability that no trade deal can fix. Third: present a unified ASEAN voice in the next round of Section 301 negotiations; the fragmented, each-nation-for-itself approach of 2025 produced deals of widely varying quality and left smaller economies like Cambodia badly exposed.
The Liberation Day tariffs may have been struck down by the Supreme Court. But the forces that produced them—America’s $760 billion goods trade deficit with Asia, domestic manufacturing anxieties, bipartisan economic nationalism—remain entirely intact. What’s next for South-east Asia after Trump tariffs is, ultimately, what has always been true: the region’s best defence is not diplomatic dependence on any single patron, but structural self-sufficiency that no tariff schedule can easily undo.
Key Data at a Glance (April 2026)
| Country | Liberation Day Rate | Current Effective Rate | GDP Growth 2025 | Key Sector |
|---|---|---|---|---|
| Vietnam | 46% | ~12.7% (post-deal, 20% headline) | 8.02% | Electronics, semiconductors |
| Malaysia | 25% | ~11% (exemptions) | ~4.5% est. | Chips, manufacturing |
| Thailand | 36% | ~10% (exemptions) | ~3.2% est. | Automotive, electronics |
| Indonesia | 32% | ~19.7% | ~4.8% est. | Commodities, manufacturing |
| Cambodia | 49% | ~19% | ~5.1% est. | Textiles, garments |
| Singapore | 10% | ~2.6% (FTA buffer) | ~3.0% est. | Financial services, logistics |
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Peso Mexicano vs Dólar Estadounidense: A Practical USD/MXN Guide for October 2026

Is the Stock Market Open on Columbus Day 2026? NYSE, Nasdaq and Bonds Explained

Concert Ticket Prices in 2026: Dynamic Pricing, Fees and How to Buy Safely

High-Yield Savings Accounts in 2026: How to Compare APY Without Chasing a Headline

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Social Security 2027 COLA Announcement: Date, Formula and What Retirees Should Check

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

Q3 2026 Earnings Preview: Can Record Profit Expectations Keep Wall Street’s Rally Alive?

Russia Diesel Deal 2026: Oil Prices and Inflation Risks

Fed Rates 2026: Treasury Yields, Bonds and SGOV Explained

S&P 500 Market Breadth 2026: Weak Rally or Rotation?

The AI Capex Boom: Data Centers Reshaping Growth

Palantir Stock in 2026: Extraordinary AI Growth

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

World’s Largest Economies: Ranking the Top Global Powers

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025