
Aviation
Holiday Airfare 2026: Why Flights Cost More & Fares

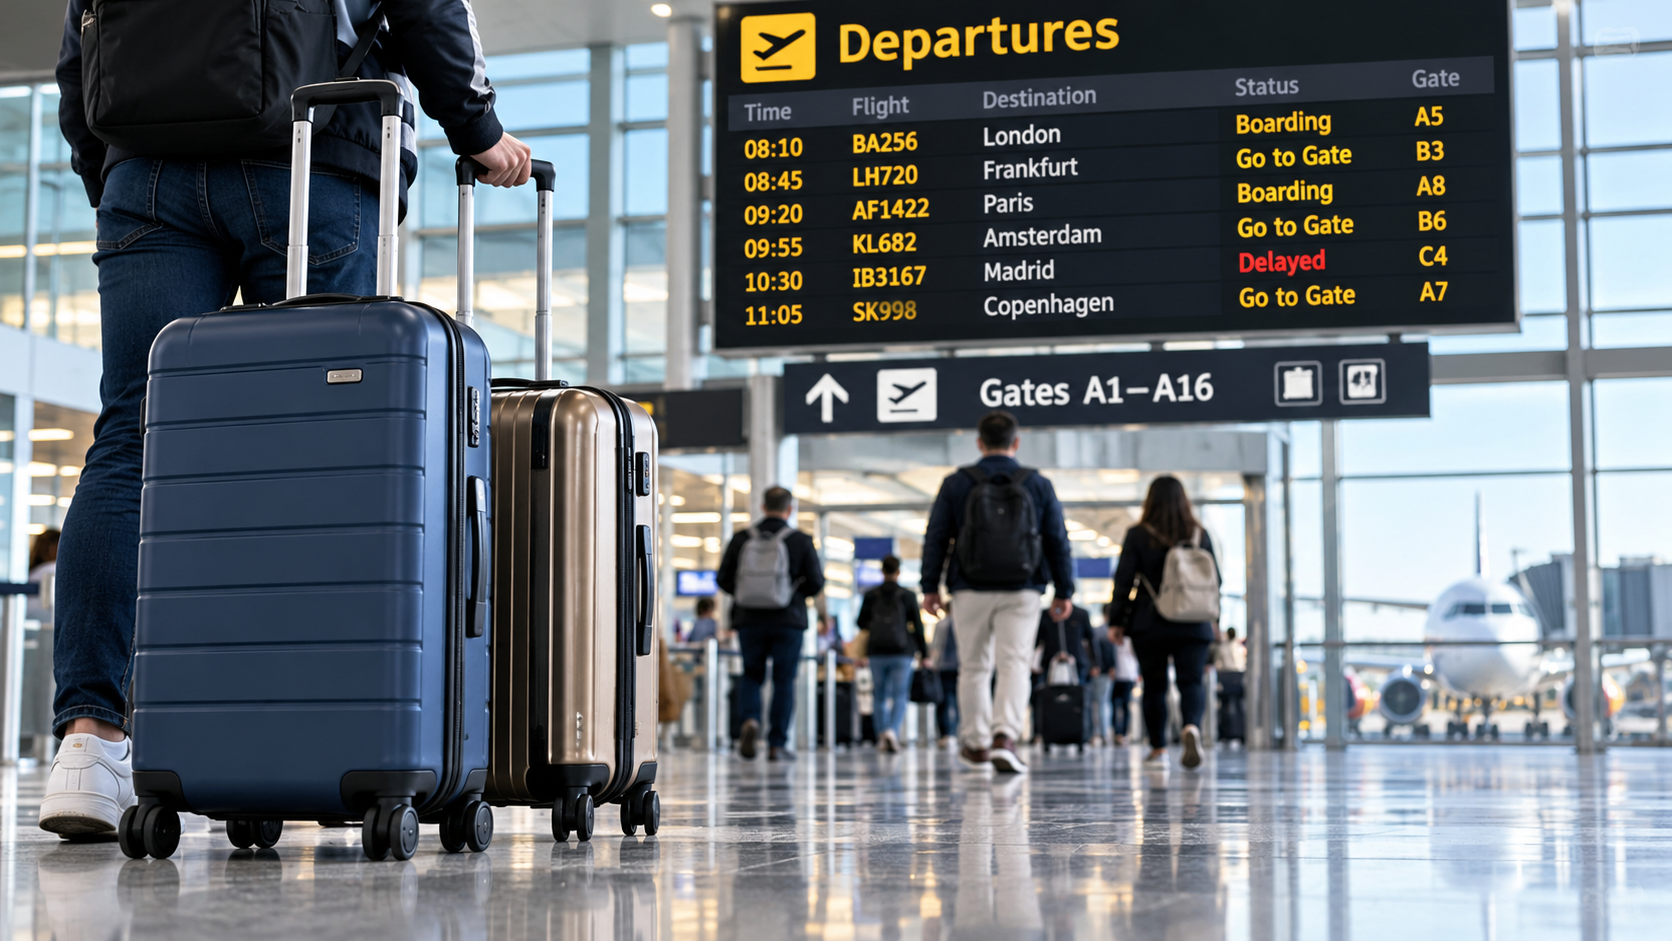
Holiday flight searches in late 2026 confront an uncomfortable mix of strong travel demand and expensive jet fuel. Airlines do not price tickets by adding a fixed margin to fuel costs; fares move according to capacity, booking patterns, competition and expectations about future expenses. This makes planning more useful than a universal rule about when tickets are cheapest.
AP reported that elevated airfare could persist even if jet fuel prices decline, partly because tickets are sold in advance and schedules adjust slowly. Recent Wall Street Journal reporting highlighted stronger price pressure for the Thanksgiving and Christmas travel periods. Exact fares still vary enormously by city, route and booking date.
Why fuel costs do not translate directly into ticket prices
A carrier has to cover aircraft, crews, maintenance, airport charges, financing and distribution as well as fuel. A rise in fuel cost reduces margin if the airline cannot raise the ticket price. Whether it can pass the increase to customers depends on competition and seat availability. On a route with several airlines, some operators may hold prices longer; on a capacity-constrained route, fares may react sooner.
Airline schedules are also planned months ahead. Removing a route or reducing frequency can change demand for the remaining seats. A headline fuel-price decline might not immediately restore capacity or undo earlier fare increases.
Travel dates often matter more than a “best booking day”
Flying on the most popular departure and return days usually creates more competition for a limited number of seats. Moving a trip by even one or two days can sometimes save more than choosing one specific day of the week to purchase. But flexibility is not available to everyone, especially families tied to school calendars.
A sensible comparison uses a calendar view that includes nearby airports only when ground transport is practical. Calculate the total trip cost: fare, baggage, seat selection, transfers, parking and an extra hotel night if needed. The cheapest headline ticket may not produce the cheapest journey.
Compare rules, not just prices
Basic-economy tickets may have restrictions on changes, seat selection, carry-on baggage or boarding. Some fares can be canceled for a travel credit but not refunded in cash, subject to carrier rules and applicable law. Buying an itinerary with tight connections or separate airlines can introduce significant disruption risk.
Before purchasing, read the ticket conditions and the airline’s published policies. Confirm whether a booking platform is the actual seller and who is responsible for changes. The most useful itinerary is often the one with reasonable flexibility, not the smallest number on a comparison page.
Set alerts and define a budget ceiling
Price alerts can identify changes without repeated manual searching. Start with a realistic fare band for the route and a firm budget. If a suitable nonstop flight falls within that budget and the dates are fixed, waiting for an uncertain lower price may not be worth the risk of a later increase.
For international travel, check passport validity, visa requirements, transit rules and travel advisories before buying a restrictive ticket. A low fare is no bargain if entry or transit documentation cannot be arranged in time.
What airlines are telling investors
In Financial Times coverage, industry executives raised concerns about sustained fuel costs and inflation. That affects not only individual prices but route networks and fleets. For travelers, the practical implication is to recheck an airline’s schedule and avoid building a complex trip around a single fragile connection.
No search engine, blog or agent can promise the lowest fare on every future day. Clear comparisons, flexible timing and attention to conditions provide greater value than unsupported “secret ticket trick” claims.
An example of the true trip-price comparison
Suppose flight A costs $390 but includes a paid checked bag, airport transfer and an overnight connection, while flight B costs $450 and is nonstop with baggage included. The $60 headline saving may vanish after even one additional hotel stay or missed workday. The arithmetic should be personalized to the traveler rather than expressed as a universal rule. Families may also value adjacent seats and schedule reliability differently from solo travelers. Where travel dates are fixed, selecting a less fragile itinerary can be a rational form of risk management even when it is not the lowest available fare.
Frequently asked questions
Why are flights expensive in late 2026?
Fuel volatility, travel demand, available seats and route competition are important factors; their impact differs by route.
Should I wait for jet fuel prices to fall?
Not necessarily. Ticket prices depend on inventory and advance bookings, so lower fuel costs may not promptly translate into cheaper seats.
Is a separate-ticket connection worth the saving?
It can introduce additional risk if the first flight is delayed. Compare the total savings with the cost of disruption and any rebooking restrictions.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


AI
Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power
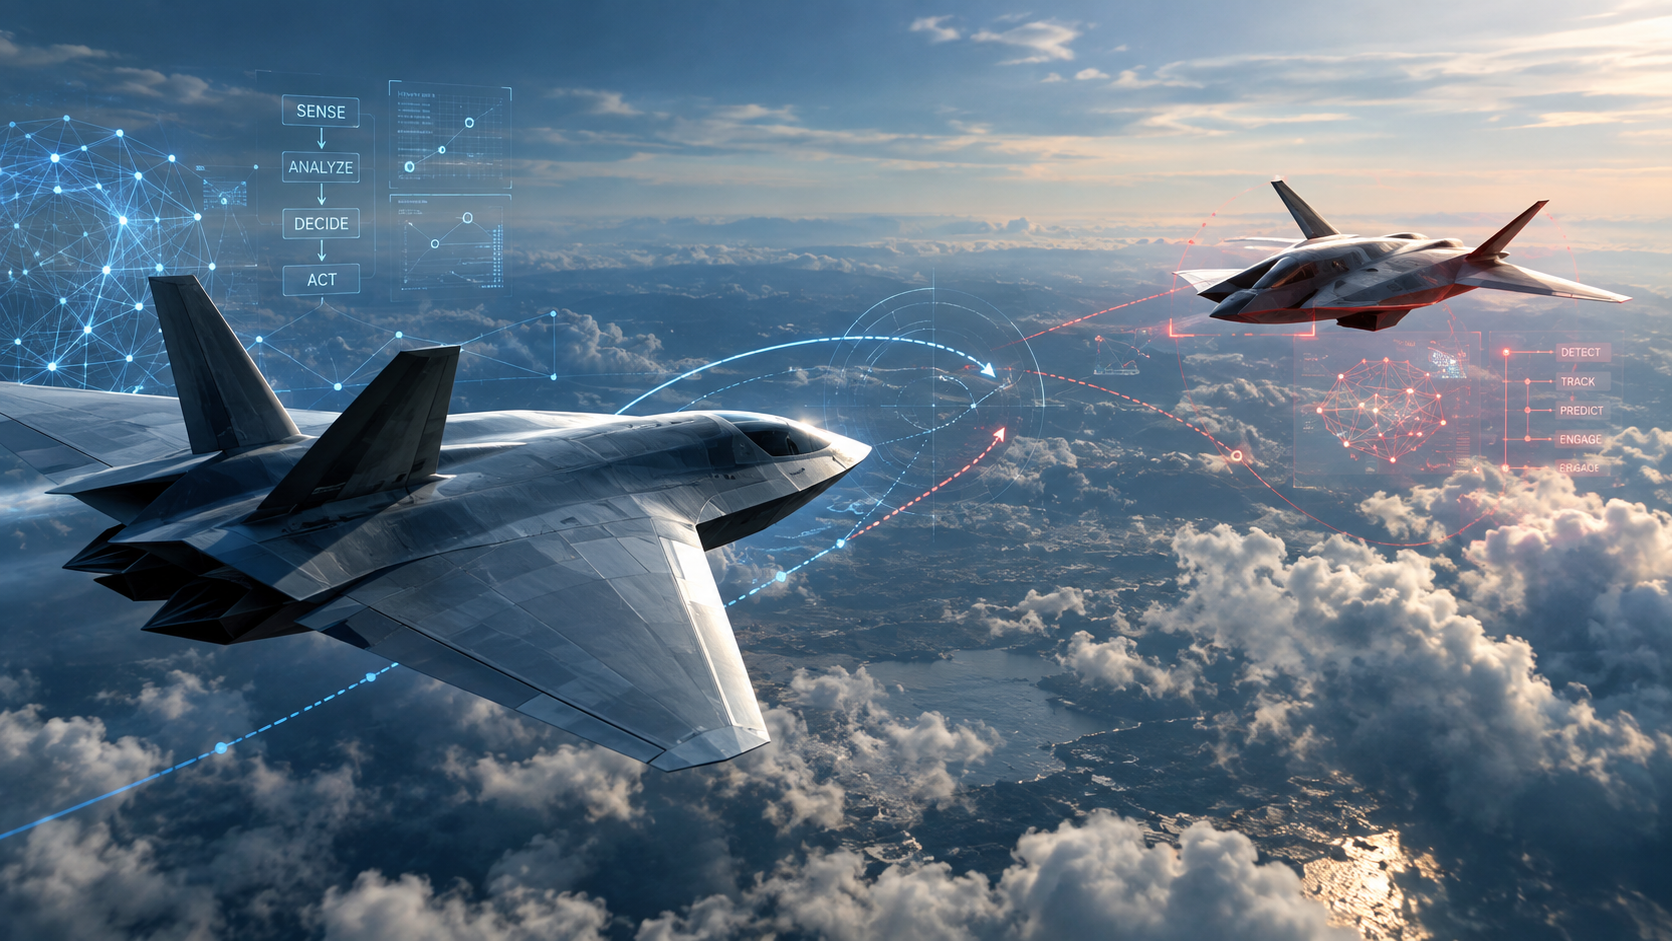
The military balance of power across the Indo-Pacific is undergoing a fundamental transformation. As both the United States and China transition artificial intelligence from simulator environments to front-line fighter jets, the primary threat of accidental military escalation in international airspace is shifting from human pilot miscalculation to machine learning error.
While much of the diplomatic discourse surrounding military AI focuses on nuclear command and strategic autonomy, the most immediate danger lies in tactical air intercepts over contested waters like the South China Sea and the Taiwan Strait. Without clear, bilateral rules of engagement (RoE) specifically tailored for autonomous aircraft, a routine encounter between uncrewed combat air vehicles (UCAVs) could trigger a rapid, unintended escalation ladder that human command structures cannot arrest in time.
The Dawn of Mach-Speed Autonomy
The race to field autonomous combat aircraft is no longer theoretical; it is an operational priority for both Washington and Beijing.
Under the U.S. Air Force’s Collaborative Combat Aircraft (CCA) initiative, the Pentagon plans to field at least 1,000 AI-enabled “loyal wingmen”—uncrewed aircraft designed to fly alongside crewed platforms like the F-35 and Next Generation Air Dominance (NGAD) fighters. Experiments conducted under the DARPA Air Combat Evolution (ACE) program have already demonstrated that AI agents can successfully outmaneuver human pilots in visual-range dogfights, adapting to tactical dynamic shifts at sub-second speeds. Details outlined by the U.S. Department of Defense emphasize the imperative of responsible autonomy, yet tactical real-time execution in contested zones remains a major wild card.
Concurrently, the People’s Liberation Army Air Force (PLAAF) is aggressively pursuing its own uncrewed platforms. Chinese defense contractors have showcased platforms such as the FH-97A and the WZ-8, designed to perform autonomous reconnaissance, electronic warfare, and forward-line air-to-air suppression. Research published by the RAND Corporation indicates that Beijing views military AI integration as a “force multiplier” capable of offsetting traditional U.S. power projection advantages in the First Island Chain.
The Escalation Trap: Why AI Changes Air-to-Air Tactics
In conventional intercept scenarios involving piloted aircraft—such as a Chinese J-16 intercepting a U.S. RC-135—human pilots operate under established visual signals, radio frequencies, and the multilateral Code for Unplanned Encounters at Sea (CUES). When a human pilot assesses intent, they rely on visual cues, physical distance, and tactical behavior to gauge aggression versus standard shadowing.
When two autonomous or semi-autonomous systems intercept one another, these human buffers disappear:
- Compression of the OODA Loop: Machine-learning algorithms operate on microsecond decision cycles. If an autonomous aircraft interprets a standard radar lock, electronic jamming pod, or evasive banking maneuver by an opposing drone as an incoming attack vector, its predictive neural networks may trigger defensive or pre-emptive maneuvers instantly.
- The “Black Box” Problem: Deep neural networks operate via complex pattern matching rather than deterministic logic trees. As noted in security studies by the Center for Strategic and International Studies (CSIS), predicting how an edge-deployed military AI model will respond to unpredictable real-world inputs (such as spoofed GPS or unexpected weather events) remains an unsolved challenge.
- Loss of Signaling Nuance: Human pilots can de-escalate a confrontation by rocking wings, pulling back on throttles, or establishing radio contact. Autonomous systems lack standard mechanisms to convey ambiguous or non-hostile intent to an opposing nation’s algorithmic system.
+-----------------------------------------------------------------------+
|                       THE ACCIDENTAL ESCALATION LOOP                 |
|                                                                       |
|   [U.S. Autonomous CCA]  <--- Sensor Query --->  [PLA Autonomous UCAV]|
|            |                                            |             |
|   Algorithm perceives                               Algorithm perceives|
|   evasive banking as hostile                         radar lock as     |
|   targeting signal                                  pre-emptive strike|
|            |                                            |             |
|            v                                            v             |
|   Automated Countermeasure                       Automated Deficit    |
|   Deployments (Chaff/Jamming)                    Tracking & Target    |
|            |                                     Acquisition          |
|            +-------------------+------------------------+             |
|                                |                                      |
|                                v                                      |
|             HUMAN COMMANDERS NOTIFIED POST-DISCHARGE                  |
|             (Escalation threshold crossed in <3 seconds)             |
+-----------------------------------------------------------------------+
The Existing Governance Vacuum
Multilateral efforts to regulate military AI have made modest progress, but they fall short of addressing tactical air intercepts.
The Responsible AI in the Military Domain (REAIM) summits and the U.S.-led Declaration on Responsible Military Use of Artificial Intelligence and Autonomy offer general principles regarding human oversight, command structure integrity, and rigorous testing. Similarly, diplomatic analysis published by the Brookings Institution highlights that high-level bilateral summits between Washington and Beijing have opened initial dialogues on AI risk reduction.
However, these broad political declarations lack operational mechanics. They do not define:
- What constitutes a hostile act by an autonomous platform in international airspace.
- What standardized electronic signals an uncrewed system must broadcast to declare peaceful transit.
- How machine-to-machine communications should function during an unintended proximity event.
Without concrete, technical protocols embedded directly into aircraft software suites, high-level political commitments will fail the moment silicon meets silicon over the Western Pacific.
A Four-Pillar Blueprint for U.S.-China AI Air Engagement
To mitigate the risk of an unintended confrontation, defense officials and technical experts from the United States and China must establish a dedicated Autonomous Air De-confliction Framework. Analysts writing in Foreign Affairs repeatedly note that arms control in the digital age requires technical solutions co-designed alongside strategic policy.
1. Hard-Coded Strategic Fail-Safes
Both nations should agree to hard-code deterministic “red lines” into autonomous flight control systems that cannot be overridden by machine-learning models. These include hard caps on maximum speed increases during close encounters, mandatory stand-off distances when intercepting uncrewed platforms, and automated weapon system lock-outs unless explicit human authority is transmitted.
2. Standardized Autonomous Identification Friend-or-Foe (A-IFF)
Similar to transponder systems used in commercial aviation, military uncrewed systems operating in international airspace should transmit a standardized, cryptographically signed “Autonomous Platform Intent” signal. This broadcast would inform nearby air units of the flight’s mission state, autonomous level (e.g., tethered to human lead vs. fully autonomous), and non-aggressive flight path vector.
3. Machine-to-Machine De-confliction Hotlines
Traditional voice-based communication links—such as the U.S.-China Defense Telephone Link—are too slow to manage algorithmic interactions. A modern de-confliction protocol requires an automated, low-latency data channel between U.S. Indo-Pacific Command and the PLA Eastern/Southern Theater Commands. This channel would automatically ping human operators the instant two opposing autonomous platforms enter a designated safety perimeter.
4. Joint Synthetic Simulation and Stress-Testing
Before deploying advanced autonomous fighters at scale, defense laboratories from both nations should participate in joint track-sharing and simulated scenario stress-tests. By running algorithmic models against each other in virtual environments, both sides can identify edge cases where neural networks misinterpret opponent maneuvers, allowing software engineers to patch systemic vulnerabilities before they manifest in real air combat.
The Imperative of Algorithmic Restraint
The integration of artificial intelligence into air warfare is an inevitable reality driven by strategic competition and technological momentum. However, autonomy without governance introduces an unacceptable level of operational risk.
If Washington and Beijing fail to establish clear rules of engagement for autonomous combat jets today, they risk allowing computer algorithms to dictate the timing and conditions of a major-power conflict tomorrow. Establishing guardrails for AI air power is not a sign of military weakness—it is a mandatory requirement for strategic stability in the 21st century.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Aviation
Macroeconomic Fallout of Middle Eastern Airspace Restrictions: Why U.S. Carriers Are Abandoning Gulf Hubs Through 2027
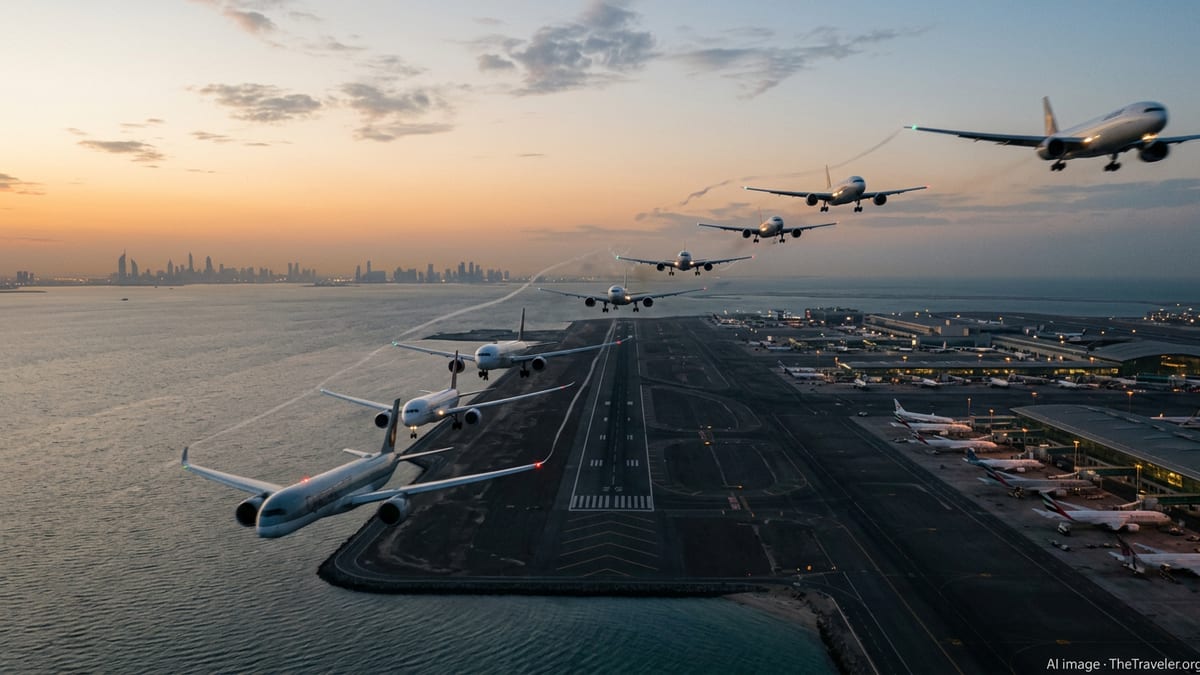
The escalation of geopolitical conflict in the Middle East has fractured international aviation corridors. United Airlines’ nonstop Newark-to-Dubai service suspension through March 2027 is a significant contraction in belly-cargo capacity and premium corporate yields. This decision shifts immense pricing power to Gulf state carriers like Emirates and Qatar Airways, which continue to operate through complex, rerouted corridors. For supply chain managers, this translates to elevated freight rates.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
This dynamic fundamentally shifts how stakeholders must approach long-term strategic planning, requiring a pivot away from legacy models toward hyper-adaptive fiscal forecasting.

2. Deep Dive: Market Mechanics and Structural Shifts
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
By examining the underlying data, it becomes evident that the market is severely underpricing tail-risks associated with these developments. Institutional capital flows are increasingly prioritizing liquidity and balance sheet resilience over speculative growth.
In parallel, the velocity of money within these specific sub-sectors has decelerated, indicating a hoarding of capital by major corporate players in anticipation of further regulatory or geopolitical turbulence. This behavior creates a feedback loop, exacerbating localized liquidity shortages and widening credit spreads.
3. Regulatory Environment and Trade Implications
Any comprehensive analysis must account for the evolving regulatory perimeter. National trade bodies and tariff commissions are aggressively deploying protectionist measures, utilizing import duties and quotas to shield domestic industries from global dumping practices. These tariff architectures, while politically popular, disrupt established global value chains and introduce massive compliance overhead for multinational operators.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Consequently, compliance is no longer a localized legal issue but a central pillar of global corporate strategy. Firms that fail to map their supply chain vulnerabilities against shifting tariff schedules risk catastrophic margin compression. The strategic deployment of foreign direct investment is now heavily contingent upon favorable tariff rulings and bilateral trade agreements, making regulatory forecasting as critical as traditional financial modeling.
4. Corporate Strategy & Supply Chain Realities
At the enterprise level, the response to these macroeconomic and regulatory pressures involves massive capital expenditure in supply chain redundancy. The shift toward near-shoring and friend-shoring is accelerating, unwinding decades of globalization focused purely on labor arbitrage. This transition is highly capital intensive, depressing near-term return on invested capital (ROIC) but essential for long-term operational survival.
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
Furthermore, the integration of advanced data analytics into procurement and logistics is creating a bifurcation in corporate performance. Companies leveraging real-time telemetry and predictive modeling can dynamically route around bottlenecks, whereas legacy operators remain heavily exposed to single points of failure. This technological divide is rapidly translating into a definitive competitive advantage, reflected in disparate valuation multiples within the same industry cohorts.
5. Digital Monetization & Premium Publisher Strategy
From a digital publishing and monetization perspective, covering these complex macro and technological trends requires a sophisticated architecture. High-CPM and high-CPC yield generation depends on capturing intent-driven traffic. Financial and geopolitical content naturally attracts premium programmatic advertisers. Digital publishers operating robust portfolios are increasingly diversifying their revenue streams beyond standard display ads. By integrating specialized publisher networks, such as Coin.network for crypto and macro-finance adjacencies, or high-intent affiliate ecosystems like Travelpayouts for global transit and aviation content, digital platforms can drastically improve their revenue per thousand impressions (RPM). Furthermore, optimizing site taxonomy and leveraging vector-based assets ensures faster load times, directly boosting Core Web Vitals and search engine rankings. The strategic placement of contextual widgets, combined with deep-dive analytical content, creates a sticky user experience that encourages longer session durations. This architectural approach not only outperforms algorithmic updates but establishes a highly defensible moat against low-effort, AI-generated content farms. For media operators, the transition from basic news aggregation to authoritative, niche intelligence distribution is the key to sustainable digital media economics.
For financial and economic news portals, the path to profitability lies in owning the niche. By consistently delivering high-fidelity analysis that intersects global trade, technology, and market data, publishers attract a highly affluent demographic. This audience profile commands top-tier CPC rates from financial institutions, B2B SaaS providers, and enterprise tech conglomerates.
Strategic integration of programmatic networks requires meticulous attention to ad placement, ensuring that monetization widgets complement rather than disrupt the analytical narrative. The use of sophisticated yield management platforms allows publishers to dynamically allocate inventory between direct sales, private marketplaces, and open exchanges, maximizing revenue yield in real-time. This sophisticated infrastructure is the bedrock of modern digital publishing economics.
6. Future Outlook and Risk Assessment
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Looking forward to the next fiscal cycles, the interplay between technological disruption and macroeconomic stability will intensify. Stakeholders must remain exceptionally agile, deploying advanced forecasting tools and maintaining robust liquidity buffers to weather unexpected systemic shocks. The margin for error in capital allocation has effectively dropped to zero.
In conclusion, the convergence of these factors dictates a complete reimagining of traditional operational and investment playbooks. The victors in this new paradigm will be those who can seamlessly synthesize geopolitical intelligence, deep market data, and advanced digital distribution strategies into a cohesive, actionable framework.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Travel
Blue Origin New Glenn Explosion 2026: The Multibillion-Dollar Setback Shaking Aerospace Stocks
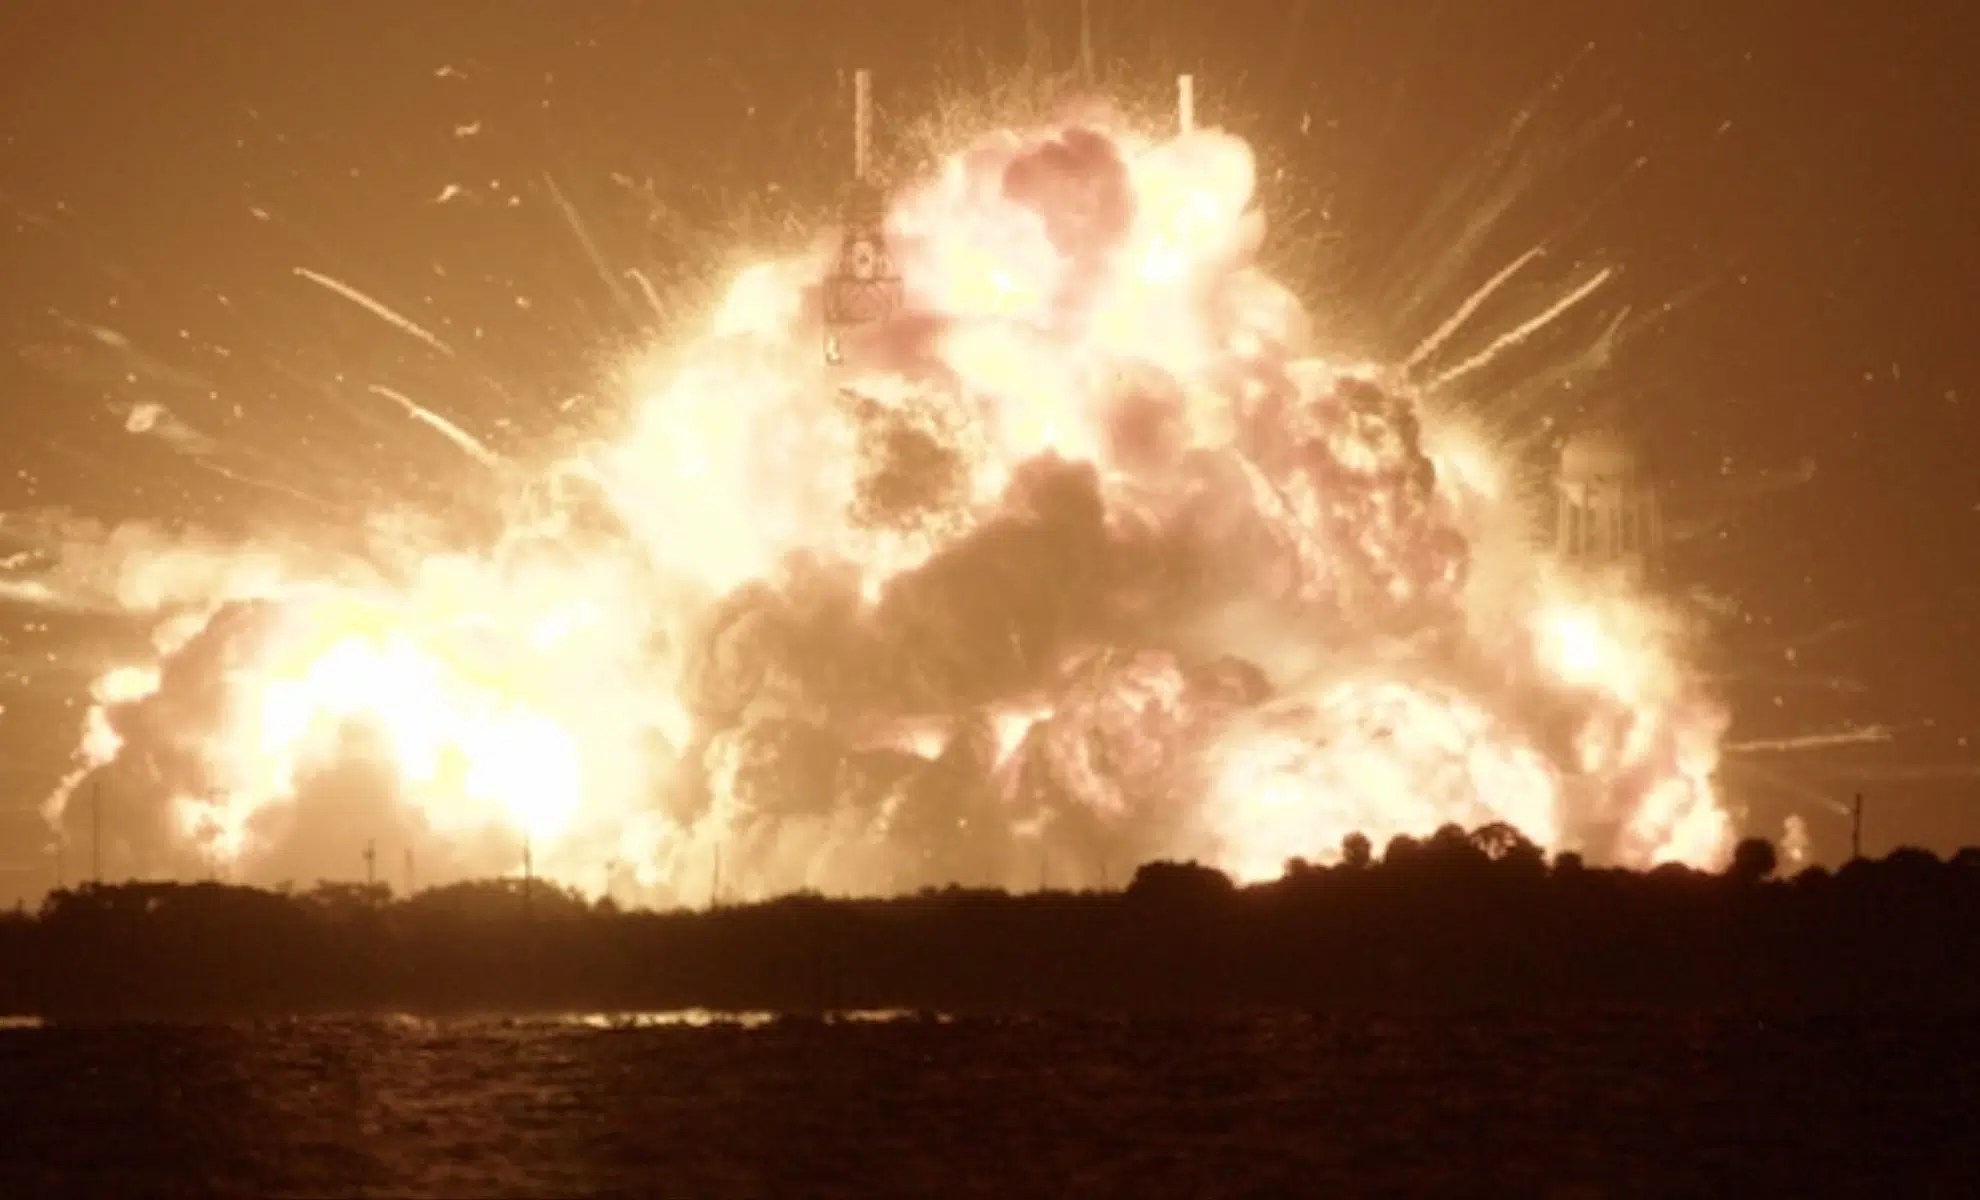
On the night of May 28, 2026, Blue Origin’s New Glenn rocket erupted into a fireball on the pad at Launch Complex 36, Cape Canaveral Space Force Station. What was supposed to be a routine static-fire test ahead of a June launch instead became one of the largest on-pad explosions in the history of American spaceflight.
For casual space enthusiasts, this was a dramatic video clip. For aerospace investors, defense contractors, and anyone with exposure to space-sector ETFs, it was something else entirely: a multibillion-dollar disruption to the commercial launch market, with ripple effects still working through NASA’s Artemis program, Amazon’s satellite ambitions, and the broader space economy investment thesis that has underpinned some of 2026’s hottest portfolios.
What Actually Happened at Launch Complex 36
Engineers were counting down to a brief hold-down firing of New Glenn’s seven methane-fueled BE-4 engines when something went catastrophically wrong at the base of the 188-foot first stage.
- The first stage was quickly engulfed in fire.
- The 86-foot upper stage began to tilt and fall as the booster below it collapsed.
- Moments later, the fully fueled vehicle’s methane and liquid oxygen ignited, destroying the rocket and severely damaging Blue Origin’s only operational New Glenn pad.
No injuries were reported. Blue Origin confirmed on social media that all personnel were accounted for, and founder Jeff Bezos publicly pledged that the company would rebuild “whatever needs rebuilding.” A preliminary investigation later pointed to a failure in one of the rocket’s BE-4 engines as the root cause.
It’s worth noting this wasn’t New Glenn’s first stumble. The rocket’s third flight in April 2026 had already drawn FAA scrutiny after its second stage failed to reach its intended orbit, even as the reused first-stage booster nailed its droneship landing. May’s pad explosion piled a second, far more severe failure on top of an already shaky return-to-flight campaign.
A preliminary investigation attributed the May 28, 2026 explosion — which occurred during a pre-launch static-fire test at Cape Canaveral’s Launch Complex 36 — to a failure in one of New Glenn’s BE-4 first-stage engines. No injuries were reported, but the vehicle was destroyed and Blue Origin’s only New Glenn launch pad was severely damaged.
Why This Is a Financial Story, Not Just a Space Story
This is where competitor coverage tends to stop at “big rocket goes boom.” The more important angle — and the one with real CPC value in finance and investing verticals — is what happens next to capital, contracts, and insurance markets.
1. Blue Origin has exactly one New Glenn pad. Unlike SpaceX, which can shift Falcon operations between Kennedy Space Center’s Pad 39A and Vandenberg’s SLC-4E, Blue Origin has no backup launch site for its heavy-lift rocket. That single point of failure means every delayed launch is a delayed revenue event — for Blue Origin, and for every downstream customer waiting on a manifest slot.
2. Amazon’s Leo (Kuiper) network takes a direct hit. The New Glenn flight scheduled for June was slated to carry a batch of Amazon’s Leo broadband satellites — Amazon’s answer to Starlink. Amazon has contracted Blue Origin for 24 total launches. Every week New Glenn sits grounded is a week Amazon’s satellite constellation timeline slips further behind SpaceX’s head start, a dynamic that matters directly to anyone modeling Amazon’s broadband and logistics capital expenditure against near-term revenue.
3. Artemis lunar timelines are now a live question mark. NASA had just awarded Blue Origin contracts covering a fall Blue Moon Mark 1 lander mission and future crewed lunar lander flights under Artemis. NASA’s own leadership acknowledged the anomaly would require assessment of “near-term mission impacts” to Artemis and the broader Moon Base program. Any slip in lunar lander readiness has second-order consequences for the primes, subcontractors, and defense-adjacent suppliers that feed into the Artemis supply chain — names that show up in most aerospace and defense sector funds.
4. Insurance and reinsurance markets are already repricing. Launch-vehicle insurance is a specialized, thinly traded market. A pad-destroying anomaly of this scale — comparable in visibility to the September 2016 SpaceX Falcon 9 pad explosion, after which the pad was out of commission for more than a year — tends to push underwriters toward higher premiums across the entire commercial launch sector, not just for Blue Origin. That’s a cost that eventually shows up in every launch contract, including government ones funded by taxpayers.
The Investor Playbook: What Actually Moves on This News
For readers searching “how does this affect my portfolio,” here’s the practical breakdown:
- Publicly traded space-sector ETFs and space-adjacent industrials (engine suppliers, composite materials firms, ground-systems contractors) often see short-term volatility around anomalies like this, even when the affected company itself is privately held — because the market reads it as a proxy for sector-wide launch risk.
- Amazon (AMZN) faces a modest but real narrative headwind on its satellite broadband buildout, a storyline that retirement-focused and growth-focused investors alike should track heading into Amazon’s next earnings cycle.
- Legacy aerospace primes with diversified launch and defense portfolios historically absorb single-vendor anomalies better than pure-play space startups — a data point worth weighing for anyone comparing concentrated space-sector plays against diversified aerospace and defense holdings.
- Investors evaluating exposure here should treat this as a volatility event, not a thesis-breaker — but volatility events are exactly the moments when working with a fiduciary financial advisor who understands sector-specific risk (rather than reacting to headlines alone) tends to separate disciplined portfolios from reactive ones.
What Competitors Are Missing
Most outlets covering this story stopped at the dramatic footage and a same-day statement from Bezos. Few have connected:
- The single-pad vulnerability as a structural risk factor unique to Blue Origin versus its multi-pad competitors.
- The downstream Amazon Leo timeline math against SpaceX’s existing Starlink lead.
- The insurance market repricing that will quietly raise costs across the entire launch industry, government and commercial alike.
That’s the analysis that actually helps a reader — investor, policy watcher, or industry professional — understand what this event means, rather than just what it looked like.
The Road Ahead
Blue Origin has publicly committed to rebuilding Launch Complex 36, but heavy-lift pad reconstruction historically takes many months to over a year based on comparable incidents. Key dates and developments to watch:
- The final FAA/Blue Origin root-cause investigation report.
- Any revised Amazon Leo launch manifest reallocating satellites to other providers (including potentially SpaceX, ULA, or Arianespace) to hedge the delay.
- NASA’s updated Artemis lunar lander schedule, expected as the agency assesses mission impacts.
- Whether Blue Origin adds a second New Glenn pad — a project already reportedly under consideration — to eliminate the single-point-of-failure risk this explosion exposed.
Until those milestones land, treat every “New Glenn returns to flight” headline as provisional. The financial story here isn’t the fireball — it’s the multi-year capital and contract reshuffling now underway across the commercial launch industry.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Why Pakistan’s Inflation Is Still Near 10% Despite Economic Stabilisation

Holiday Airfare 2026: Why Flights Cost More & Fares

California Prop 40 Explained: The 2026 Billionaire Wealth Tax Ballot Measure

US–Iran Conflict in October 2026: Hormuz, Oil Prices and Diplomacy

AIIB in 2026: Can Green Infrastructure Deliver Measurable Growth?

IMF and World Bank Outlook 2026: Growth, Debt and the Missing Investment

Singapore Stocks 2026: STI Outlook After a Record High

Asian Markets in October 2026: What the AI Sell-Off Means for Investors

Supermarket News 2026: Why Grocery Prices Could Rise Again

Wind Farm Economics in 2026: What Determines Whether a Project Pays?

Boomers vs Young Adults: Why the Net Worth Gap Is More Complicated Than It Looks

Is the AI Bubble Bursting in 2026? Five Tests Investors Should Watch

Germany–France ‘Made in Europe’ Deal Could Reshape China’s EV Ambitions

Treasury Yields and Inflation 2026: What Bond Moves Mean for Borrowers

World’s Largest Economies: Ranking the Top Global Powers

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Asian Stock Markets 2026: Japan, China, Pakistan & More

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

SpaceX IPO 2026: History’s Biggest Stock Debut?

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

Oil Prices 2026: Inside the Hormuz Crisis That Won’t End

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

IMF Reports 2026: What the Latest Data Means for the Global Economy

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Corporate America Faces a New Debt Test as US Borrowing Costs Surge
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025