
economic Zones
Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

The International Monetary Fund scheduled its full October 2026 World Economic Outlook for October 13 during annual meetings in Bangkok. As of October 12, a credible preview should not claim to know revisions in a report that has not yet been released. The main questions concern growth resilience, public debt, inflation pressure, trade fragmentation and geopolitical disruption. Sources: International Monetary Fund and World Trade Organization.
The important context competitors can overlook
These risks interact. Higher oil prices can squeeze household purchasing power; restrictive financing costs can slow business investment; trade barriers can reduce productive efficiency even when some protected producers benefit. Currency moves redistribute pressure between importers and exporters. A single worldwide growth figure therefore conceals important differences between economies. For primary-source checks and current reporting, see International Monetary Fund and Reuters bond market analysis. The key distinction is preview imf report rather than assert future numbers.
A practical way to use this information
Build coverage around three scenarios: baseline demand that remains resilient, a negative supply shock that lifts inflation while reducing growth, and a faster normalization of energy and trade conditions. After October 13, replace the preview with actual IMF forecasts, precise country tables and a transparent comparison with the previous edition. Link directly to the IMF report and explain which assumptions drive revisions.
Before the scheduled October 13 IMF release, updated figures remain unconfirmed. Evaluate growth forecasts as conditional estimates with explicit assumptions. Research cutoff: October 12, 2026; confirm developing facts before publication.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Has the full October 2026 WEO been released on October 12?
The IMF scheduled the full report for October 13, so do not use unsourced figures from it before release.
What risks matter most?
Energy, debt, trade barriers and inflation influence countries differently.
What a World Economic Outlook forecast actually measures
The International Monetary Fund’s World Economic Outlook is a set of estimates and projections covering economic growth, inflation and related macroeconomic developments across many countries. It brings a common framework to questions that individual national data releases cannot answer alone. Forecasts are conditional, not guaranteed outcomes. They reflect available data and analytical assumptions that may change as new information arrives. A report scheduled for a future release should not be quoted as if its updated tables have already been published.
Growth rates require careful interpretation. A country expanding rapidly from a small base may contribute less to global output than a large economy growing slowly. Purchasing-power-parity and market-exchange-rate measures can produce different rankings for economic size. Headline real GDP growth adjusts for changes in prices, while nominal growth does not. The right measure depends on the question: living standards, international market size, debt burden or trade exposure. An excellent outlook article defines its units before comparing countries.
Five channels that can shift global growth
Energy: higher oil or gas costs can reduce real household purchasing power and increase business expenses. Interest rates: higher borrowing costs may delay construction, investment and consumption. Trade: tariffs or export restrictions can redirect supply chains and influence prices. Technology: investment in artificial intelligence could improve productivity, but results may take time and differ by industry. Geopolitics: conflict and uncertainty can disrupt transport or deter long-term commitments. None of these forces acts independently; their interactions are a major source of forecasting uncertainty.
An energy price shock can simultaneously raise inflation and weaken growth in importing economies. Lower policy rates could support spending but may be constrained by price pressures or concerns about financial stability. Trade diversification might raise costs initially but reduce exposure to future interruptions. The usefulness of an IMF outlook lies in making these tradeoffs comparable, not in delivering a single number to settle every economic debate.
Why debt sustainability deserves separate attention
Government debt cannot be evaluated by size alone. The interest rate paid, maturity profile, currency of denomination, revenue base and pace of economic growth all influence fiscal risk. A country borrowing mostly in its own currency under long maturities may face different pressures from one heavily dependent on foreign-currency refinancing. Higher global bond yields can increase the cost of new government borrowing even before existing fixed-rate obligations mature. Fiscal analysis should avoid treating every large debt-to-GDP ratio as imminent default.
The private sector also matters. Households with variable-rate borrowing may see payments change faster than households with fixed-rate loans. Companies that must refinance bonds soon may be more exposed than firms with long-maturity debt and stable cash flow. A global report can identify common risks, but readers need country and balance-sheet details before applying its conclusions to specific decisions.
How to compare forecast revisions responsibly
Record the previous forecast, the newly published estimate, the country, forecast year and publication date. If growth for a particular economy moves from a hypothetical 2.0% to 1.7%, say it was revised down by 0.3 percentage points—not 0.3%. Differentiate real GDP from nominal GDP and annual averages from fourth-quarter-to-fourth-quarter changes. Note whether the IMF attributes revisions to new data, methodology or changed assumptions. Forecast revisions can be meaningful without proving that the earlier analysis was careless; forecasting is inherently conditional.
A balanced story also checks alternative institutional views, such as the World Bank or national central banks, while avoiding the assumption that one institution has a guaranteed superior forecast. Divergent views can reveal uncertainties worth explaining. Use direct tables where possible rather than relying exclusively on a news summary.
What households and businesses can take from the outlook
Consumers can use broad economic scenarios to revisit employment stability, borrowing obligations and emergency savings, but should not trade on an IMF headline alone. Businesses can assess demand sensitivity, energy costs, currency exposure and supplier concentration. Investors can compare reported corporate earnings with the macroeconomic assumptions implied by valuations. In each case, the value is in planning across multiple scenarios rather than following a universal recommendation.
When the October 2026 report becomes available, update the article with the confirmed numbers and precise table references. Label the old pre-release text as historical context. A credible living article is more valuable than a seemingly current story that quietly preserves obsolete projections.
What to ask when the new IMF figures arrive
Which countries were revised most significantly?
Compare like-for-like real-growth projections for the same calendar year against the earlier publication. A downward revision is not the same as an economic contraction: growth may still be positive. Check whether the country-level projection reflects a changed assumption about energy, trade, domestic demand or financial conditions.
Are the inflation forecasts headline or core measures?
Countries use different baskets and central-bank targets. The IMF’s data definitions should be checked before placing figures side by side. A global average should not be presented as the inflation rate every household experiences. Food, housing and energy exposure differ substantially across countries.
How should an investor interpret the report?
Use it to identify macroeconomic assumptions and risks, then compare those with a specific investment’s cash flows and valuation. The outlook does not recommend buying or selling a named stock, bond or currency. Strong global growth and a poor individual investment return can occur simultaneously.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Economic Costs of Wars
The Economics of Ceasefire Negotiations: Trade Routes, Commodity Stabilization

Ceasefire negotiations are heavily priced into Brent crude benchmarks and maritime insurance premiums. Successful mediation unfreezes shipping chokepoints, reducing ‘war risk’ premiums levied by insurers, lowering freight costs, and easing global consumer inflation, while post-conflict reconstruction offers massive capital expenditure booms.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality.
Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
This dynamic fundamentally shifts how stakeholders must approach long-term strategic planning, requiring a pivot away from legacy models toward hyper-adaptive fiscal forecasting.
2. Deep Dive: Market Mechanics and Structural Shifts
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
By examining the underlying data, it becomes evident that the market is severely underpricing tail-risks associated with these developments. Institutional capital flows are increasingly prioritizing liquidity and balance sheet resilience over speculative growth.
In parallel, the velocity of money within these specific sub-sectors has decelerated, indicating a hoarding of capital by major corporate players in anticipation of further regulatory or geopolitical turbulence. This behavior creates a feedback loop, exacerbating localized liquidity shortages and widening credit spreads.
3. Regulatory Environment and Trade Implications
Any comprehensive analysis must account for the evolving regulatory perimeter. National trade bodies and tariff commissions are aggressively deploying protectionist measures, utilizing import duties and quotas to shield domestic industries from global dumping practices. These tariff architectures, while politically popular, disrupt established global value chains and introduce massive compliance overhead for multinational operators.
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Consequently, compliance is no longer a localized legal issue but a central pillar of global corporate strategy. Firms that fail to map their supply chain vulnerabilities against shifting tariff schedules risk catastrophic margin compression. The strategic deployment of foreign direct investment is now heavily contingent upon favorable tariff rulings and bilateral trade agreements, making regulatory forecasting as critical as traditional financial modeling.
4. Corporate Strategy & Supply Chain Realities
At the enterprise level, the response to these macroeconomic and regulatory pressures involves massive capital expenditure in supply chain redundancy. The shift toward near-shoring and friend-shoring is accelerating, unwinding decades of globalization focused purely on labor arbitrage. This transition is highly capital intensive, depressing near-term return on invested capital (ROIC) but essential for long-term operational survival.
Delving deeper into the structural mechanics, we see a profound transformation in how institutional capital evaluates risk. Historically, geographic diversification offered a reliable hedge against localized downturns. Today, however, the rapid transmission of financial shocks across borders—facilitated by highly integrated banking networks and algorithmic trading—means that systemic risk is virtually ubiquitous. Asset managers are heavily scrutinizing cash flow durability, favoring sectors with inelastic demand characteristics. The regulatory environment is also tightening. Heightened scrutiny over data privacy, antitrust concerns in the technology sector, and rigorous ESG (Environmental, Social, and Governance) compliance mandates are forcing companies to overhaul their operational frameworks. These compliance costs are inevitably passed down to the consumer, fueling core inflationary pressures. Concurrently, the labor market is undergoing a structural shift. The automation of routine tasks, coupled with the rising premium on specialized technical and analytical skills, is widening the productivity gap between different segments of the workforce. For policymakers and corporate strategists alike, navigating this landscape requires a nuanced understanding of these intersecting vectors, moving beyond traditional econometric models to incorporate real-time, alternative data sources.
Furthermore, the integration of advanced data analytics into procurement and logistics is creating a bifurcation in corporate performance. Companies leveraging real-time telemetry and predictive modeling can dynamically route around bottlenecks, whereas legacy operators remain heavily exposed to single points of failure. This technological divide is rapidly translating into a definitive competitive advantage, reflected in disparate valuation multiples within the same industry cohorts.
5. Digital Monetization & Premium Publisher Strategy
From a digital publishing and monetization perspective, covering these complex macro and technological trends requires a sophisticated architecture. High-CPM and high-CPC yield generation depends on capturing intent-driven traffic. Financial and geopolitical content naturally attracts premium programmatic advertisers. Digital publishers operating robust portfolios are increasingly diversifying their revenue streams beyond standard display ads. By integrating specialized publisher networks, such as Coin.network for crypto and macro-finance adjacencies, or high-intent affiliate ecosystems like Travelpayouts for global transit and aviation content, digital platforms can drastically improve their revenue per thousand impressions (RPM). Furthermore, optimizing site taxonomy and leveraging vector-based assets ensures faster load times, directly boosting Core Web Vitals and search engine rankings. The strategic placement of contextual widgets, combined with deep-dive analytical content, creates a sticky user experience that encourages longer session durations. This architectural approach not only outperforms algorithmic updates but establishes a highly defensible moat against low-effort, AI-generated content farms. For media operators, the transition from basic news aggregation to authoritative, niche intelligence distribution is the key to sustainable digital media economics.
For financial and economic news portals, the path to profitability lies in owning the niche. By consistently delivering high-fidelity analysis that intersects global trade, technology, and market data, publishers attract a highly affluent demographic. This audience profile commands top-tier CPC rates from financial institutions, B2B SaaS providers, and enterprise tech conglomerates.
Strategic integration of programmatic networks requires meticulous attention to ad placement, ensuring that monetization widgets complement rather than disrupt the analytical narrative. The use of sophisticated yield management platforms allows publishers to dynamically allocate inventory between direct sales, private marketplaces, and open exchanges, maximizing revenue yield in real-time. This sophisticated infrastructure is the bedrock of modern digital publishing economics.
6. Future Outlook and Risk Assessment
The current macroeconomic environment is characterized by unprecedented volatility, driven by shifting monetary policies, supply chain recalibrations, and evolving trade barriers. As central banks navigate the delicate balance between curbing inflation and preventing deep recessions, emerging markets face asymmetric risks. Developing economies must rigorously manage their foreign exchange reserves while calibrating import duties and trade frameworks—often leveraging insights from national tariff commissions to protect domestic industries without stifling vital foreign direct investment. This delicate equilibrium directly impacts global liquidity, equity valuations, and sovereign debt yields. The restructuring of global supply chains, initially sparked by geopolitical friction, has now become a structural reality. Corporations are transitioning from ‘just-in-time’ manufacturing to ‘just-in-case’ inventory management, fundamentally altering capital expenditure cycles. Furthermore, the integration of advanced digital tracking and open-source intelligence is allowing multinational firms to better anticipate supply shocks, although the cost of implementing these technologies creates new barriers to entry for smaller enterprises. Ultimately, the intersection of foreign policy and economic strategy is tighter than ever, with trade tariffs and sanctions acting as primary instruments of geopolitical leverage.
Looking forward to the next fiscal cycles, the interplay between technological disruption and macroeconomic stability will intensify. Stakeholders must remain exceptionally agile, deploying advanced forecasting tools and maintaining robust liquidity buffers to weather unexpected systemic shocks. The margin for error in capital allocation has effectively dropped to zero.
In conclusion, the convergence of these factors dictates a complete reimagining of traditional operational and investment playbooks. The victors in this new paradigm will be those who can seamlessly synthesize geopolitical intelligence, deep market data, and advanced digital distribution strategies into a cohesive, actionable framework.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Economic Corridors
The Johor-Singapore Corridor: How Malaysia Became Southeast Asia’s AI Infrastructure Powerhouse
Introduction
While global attention has fixated on the Strait of Hormuz and Middle East energy risk, a quieter structural story has been reshaping Southeast Asia’s economic map: Malaysia’s transformation from a legacy chip-assembly hub into one of the region’s most important AI infrastructure and semiconductor innovation centers. Electrical and electronics exports rose 39.7% year-on-year in the first five months of 2026 alone, and the driving force behind that surge is a cross-border partnership most global business audiences have never heard of — the Johor-Singapore Special Economic Zone (VietnamPlus).
The Headline Numbers
Malaysia’s Economy Minister Akmal Nasrullah Mohd Nasir confirmed that E&E exports hit 382.9 billion ringgit (roughly $95.7 billion) in the January–May 2026 period, now representing 48.2% of the country’s total exports (VietnamPlus). That growth has fed directly into an upgraded national GDP forecast: HLIB Chief Economist Felicia Ling raised Malaysia’s 2026 growth projection to 4.7% from an earlier 4.5% estimate, citing the electrical and electronics sector’s stronger-than-expected performance alongside resilient domestic demand (BusinessToday Malaysia). That figure sits comfortably within Bank Negara Malaysia’s own official growth range of 4.0% to 5.0%, with inflation expected to average around 2.0% — well inside the central bank’s projected 1.5%–2.5% band (BusinessToday Malaysia).
The global backdrop is doing plenty of the heavy lifting: the worldwide semiconductor market is projected to expand by a remarkable 90% in 2026, driven overwhelmingly by AI infrastructure and high-performance computing demand — a tailwind HLIB expects Malaysia’s manufacturing base to keep capturing through its established position in the global semiconductor upcycle (BusinessToday Malaysia).
Why Johor, Specifically
Johor, the Malaysian state bordering Singapore, has emerged as the epicenter of this boom. In the first half of 2025 alone, Johor recorded RM56 billion (roughly $13.3 billion) in approved investments — the highest of any Malaysian state — with Singapore itself the single largest foreign investor at RM43.4 billion ($10.3 billion), a striking signal of cross-border confidence given the two economies’ historically distinct development paths (Malay Mail). The Johor-Singapore Special Economic Zone (JS-SEZ) is designed explicitly to combine Singapore’s upstream design and financial excellence with Malaysia’s outsourced semiconductor assembly and test (OSAT) strength, creating an integrated cross-border cluster rather than two competing national industries (Malay Mail).
The data center layer of this story is arguably even bigger. Johor is now described as a strategic extension of Singapore’s own digital infrastructure — absorbing the spillover of cloud, AI and hyperscale investment that land- and power-constrained Singapore cannot fully accommodate on its own soil (Bernama). AMRO’s research office notes that Malaysia is gaining data center capacity faster than any other state in the Asia-Pacific region, with proximity to Singapore cited as a decisive locational advantage alongside land and energy availability that more developed Asian markets increasingly lack (AMRO Asia).
The Economics Behind the Migration
Cost is a major part of the explanation. Average construction costs for a Malaysian data center run $8–10 million per megawatt as of 2025 — meaningfully cheaper than Singapore’s cost structure — though these costs are expected to climb 5–7% annually going forward due to inflation, rising interest rates and tightening regulation (ResearchAndMarkets/BusinessWire). Malaysia has also moved to manage the strain this investment wave places on its own grid: a new power tariff structure for data centers, finalized in mid-2025, is set to raise energy costs for operators by 10–14%, part of a broader Green Data Center Guidelines framework administered by the Malaysia Digital Economic Corporation to enforce energy-efficient, sustainable buildouts (ResearchAndMarkets/BusinessWire).
Penang’s Parallel Track: Moving Up the Value Chain
While Johor captures data centers and assembly investment, Penang — long dubbed Malaysia’s Silicon Valley — is pursuing a distinct strategy focused on higher-value semiconductor manufacturing and talent, continuing to attract chipmakers on the strength of its established supply chain and skilled workforce (Bernama). Malaysia’s government has been explicit that the ambition extends beyond hosting foreign assembly lines: officials point to the country’s strategic partnership with British chip design firm Arm as evidence of a deliberate push toward technology ownership and intellectual property, rather than remaining a pure-play assembly and test hub (VietnamPlus).
The Structural Caveat Analysts Are Flagging
Not every observer treats the data center boom as an unambiguous win. Asia Society’s Policy Institute cautions that most of Malaysia’s current data center commitments are geared toward inference and model deployment rather than the far more computationally intensive work of model training — meaning the buildout does not, on its own, move Malaysia into the small group of “compute-north” countries that shape how frontier AI models are actually built (Asia Society). Data centers also generate comparatively limited technological and labor spillover relative to semiconductor fabrication or advanced manufacturing — a distinction that matters for how much of this boom translates into durable, high-skill domestic employment versus real estate and power infrastructure investment (Asia Society).
Energy Security as a Quiet Advantage
Malaysia’s resilience narrative extends to energy as well. HLIB notes the country’s diversified crude oil import sources — spanning Saudi Arabia, Oman, Sudan, the UAE, Angola and the United States — provide meaningful insulation even in the event of shipping disruptions along routes such as the Strait of Hormuz, a risk that has weighed on other Asian import-dependent economies through 2026 (BusinessToday Malaysia).
Key Takeaways
- Malaysia’s E&E exports rose 39.7% year-on-year to $95.7 billion in the first five months of 2026, now 48.2% of total exports.
- The Johor-Singapore Special Economic Zone is the structural engine behind this growth, pairing Singapore’s capital and design strength with Malaysia’s assembly and land/power advantages.
- 2026 GDP growth has been upgraded to 4.7%, with Bank Negara Malaysia expected to hold its policy rate at 2.75% through the year.
- Data center construction costs remain cheaper than Singapore’s, though new power tariffs will raise operating costs 10–14%.
- Analysts caution the current boom is concentrated in inference-oriented, lower-spillover data centers rather than frontier model training capacity.
Sources: VietnamPlus, BusinessToday Malaysia, Malay Mail, Bernama, AMRO Asia, ResearchAndMarkets/BusinessWire, Asia Society Policy Institute
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
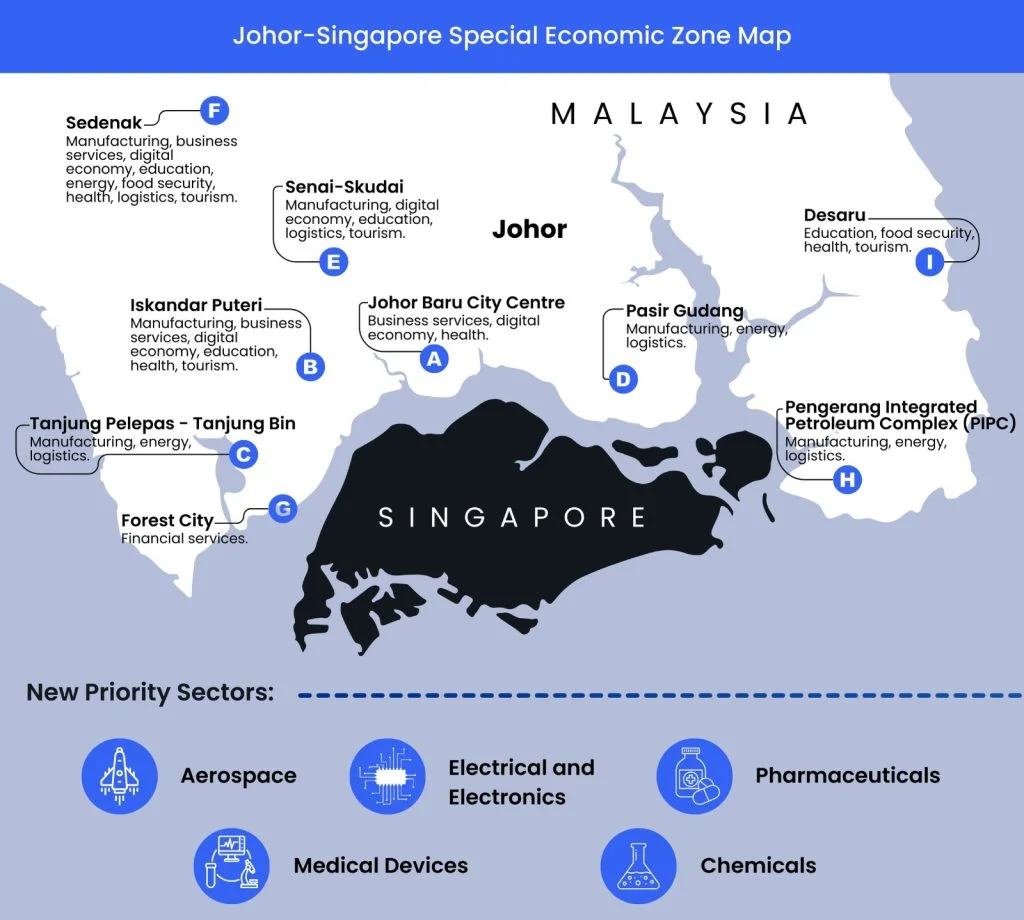
While much of global business coverage has focused on the Strait of Hormuz and Fed policy, one of Southeast Asia’s most significant economic developments has unfolded with comparatively little international attention: the Johor-Singapore Special Economic Zone has become a genuine cross-border investment magnet, even before its formal master plan has been unveiled.
The Scale of the Numbers
The JS-SEZ attracted 19 billion dollars in approved investments in 2025, with more than 57 percent of cumulative approved projects already at the implementation stage — a conversion rate that signals genuine capital deployment rather than speculative announcements. Malaysia’s Minister of Economy, Akmal Nasrullah, confirmed the momentum has continued into 2026, with a further $1.3 billion in newly approved investments recorded in the first quarter alone.
Investor interest continues to build at pace: the Invest Malaysia Facilitation Centre Johor processed 285 investment enquiries worth a combined $18.5 billion during just the first five months of 2026 — a pipeline roughly equivalent to the entire prior year’s approved investment total, suggesting the zone’s growth trajectory is accelerating rather than plateauing.
Why Investors Are Betting Ahead of the Master Plan
What makes the JS-SEZ notable is that this capital is arriving before Malaysia has formally unveiled the zone’s master plan — investors are pricing in the structural logic of the corridor itself rather than waiting for finalised regulatory detail. That logic rests on combining Singapore’s capital markets, legal infrastructure and connectivity with Johor’s land availability, labour costs and manufacturing base — a complementary pairing that Southeast Asia has lacked at this scale until now.
How much investment has the Johor-Singapore Special Economic Zone attracted?
The JS-SEZ attracted $19 billion in approved investments in 2025, with more than 57% of projects already in implementation, plus a further $1.3 billion approved in Q1 2026 — momentum that has continued even ahead of the zone’s formal master plan.
The zone’s momentum is reinforced by the broader institutional interest converging on the region. Maybank’s Invest ASEAN conference, held in Singapore in July 2026, drew roughly 200 institutional investors managing a combined $23 trillion in assets under management, with energy transition, supply chain reconfiguration and AI-led digital transformation identified as the dominant themes shaping capital allocation decisions across the region.
The Malaysia Growth Connection
The JS-SEZ is not an isolated success story — it’s a direct contributor to Malaysia’s broader macroeconomic outperformance in 2026. Maybank IBG’s decision to upgrade Malaysia’s 2026 GDP growth forecast to 4.9 percent cited sustained investment approval momentum in technology, renewable energy, industrial real estate and infrastructure — categories that map closely onto the sectors driving JS-SEZ deal flow.
Regional Comparison
Positioned against other Southeast Asian investment corridors, the JS-SEZ’s growth compares favourably even to Indonesia’s well-established Batam-Bintan-Karimun zone with Singapore, which drew $5.7 billion in investment in 2025 — roughly a third of the JS-SEZ’s total despite BBK’s longer operating history. The comparison underscores how quickly the Johor corridor has scaled since gaining formal momentum.
What to Watch Next
The formal unveiling of the JS-SEZ master plan remains the key near-term catalyst that could either validate or complicate current investment momentum, by clarifying tax incentives, land-use zoning, and cross-border labour mobility provisions. Until then, the zone’s implementation rate — already above 57 percent of approved projects — suggests investors are not waiting for regulatory certainty to deploy capital, a vote of confidence that is increasingly rare in a global environment defined by geopolitical and monetary policy uncertainty.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

Global Economy Outlook 2026–27: What to Watch Ahead of the IMF October Report

Strait of Hormuz in 2026: Why Shipping Risks Matter for Oil, Insurance and Food Prices

US–China Critical Minerals Competition in 2026: Who Controls the Supply Chain?

Oil and Diesel Prices in October 2026: How Supply Shocks Can Reach Inflation

AI Chip Demand in 2026: What TSMC, Nvidia and Data-Center Spending Reveal

Q3 2026 Earnings Season: The Bank, AI and Consumer Signals That Really Matter

Treasury Yields in 2026: Why Higher Bond Rates Matter for Stocks, Mortgages and Savings

KOSPI 2026: Why South Korean Stocks Turned Volatile and What AI Investors Should Watch

IREN Stock in 2026: AI Cloud Growth, Bitcoin Transition and the Risks Investors Miss

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Peso Mexicano vs Dólar Estadounidense: A Practical USD/MXN Guide for October 2026

Is the Stock Market Open on Columbus Day 2026? NYSE, Nasdaq and Bonds Explained

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

World’s Largest Economies: Ranking the Top Global Powers

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

The Future of Silicon: Supply Chain Vulnerabilities in the 2026 Tech Sector

Asian Stock Markets 2026: Japan, China, Pakistan & More

Stagflation vs. Soft Landing: How Central Bank Rates Are Reshaping European and Asian Economies
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025