
AI
AI Bubble Warning 2026: Why BIS, IMF and Bank of England Fear a Market Crash

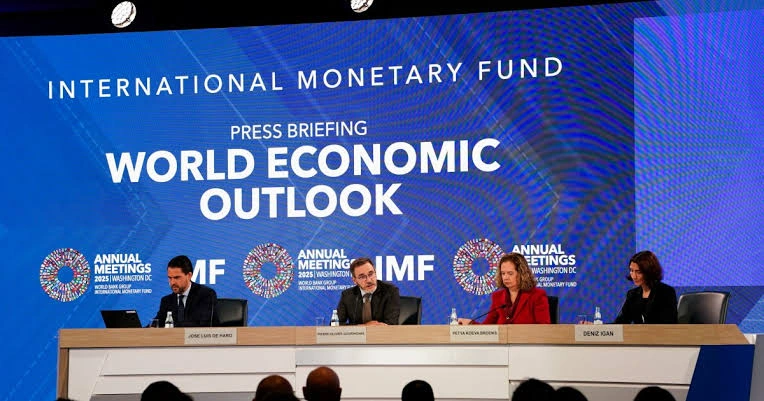
Global financial regulators have moved from quiet skepticism to open warning, marking one of the most significant shifts in central-bank rhetoric since the aftermath of the 2008 crisis. The Bank for International Settlements (BIS), the International Monetary Fund (IMF), and the Bank of England have each flagged the risk that a correction in artificial-intelligence valuations could cascade through the global financial system, according to the BIS Annual Economic Report 2026 and reporting compiled by Wikipedia’s tracking of the unfolding episode.
From Confidence to Contagion Fear
The warnings did not emerge in a vacuum. In late June 2026, South Korea’s KOSPI index was forced into a trading halt after Samsung and SK Hynix shares each lost roughly 12% in a single morning, a shock that rippled into the Nasdaq, which fell 2.2% the same day. By the following week, Oracle had recorded its worst trading week since the dot-com crash, sliding 19%, after Apple raised product prices in response to soaring chip costs. The sell-off, detailed in Wikipedia’s account of the June 2026 rout, spread across global chip manufacturers before the BIS issued its formal caution on June 29.
Pablo Hernández de Cos, general manager of the BIS, framed the moment as one of “progress” colliding with “peril,” pointing to inflationary pressure, elevated public debt, and what the institution calls AI exuberance as compounding financial vulnerabilities.
Why This Cycle Looks Different — and Why It Doesn’t
Comparisons to the 1999–2000 dot-com bubble are now routine among Wall Street strategists. Deutsche Bank’s global economics team has described 2026 as resembling “1999 meets 1990,” according to Fortune’s coverage of the growing exuberance debate. JPMorgan’s chief executive Jamie Dimon has repeatedly used the phrase “irrational exuberance,” borrowed from former Fed chair Alan Greenspan, to describe dealmaking activity that he says is running “gung-ho.”
Yet analysts at Fidelity note a structural difference from 2000: hyperscalers are largely funding AI capital expenditure from earnings rather than debt, keeping the capex-to-free-cash-flow ratio below 1, compared with nearly 4 at the dot-com peak, based on Fidelity’s bubble-indicator research. That distinction matters for systemic risk, since debt-fueled busts tend to transmit further into the banking system than equity-only corrections.
The Systemic Transmission Risk
Oliver Wyman’s analysis of a potential AI-led market collapse estimates that an equity crash on the scale of the early 2000s could erase approximately $33 trillion in value — more than annual US GDP — a scenario that would compound if financing tied to data-center and digital-infrastructure debt turns out to be more opaque than banks currently report, according to Oliver Wyman’s assessment of financial-sector exposure. US equity market capitalization currently sits at close to twice GDP, a higher multiple than at the dot-com peak.
Prediction markets have already begun pricing the risk. Polymarket data cited by Tekedia shows the probability traders assign to an AI investment-frenzy collapse by the end of 2026 climbing to 26%, up sharply in recent months as valuations in chip and hyperscaler stocks stretched further.
What Regulators Are Asking Institutions to Do
The BIS is not calling for a halt to AI development. Instead, it is urging financial institutions to build greater transparency into AI-related financing, particularly the private-credit channels that now fund a large share of data-center buildouts, and to stress-test balance sheets against valuation drops of 30%, 40%, or even 50% in AI-exposed equities. The Bank of England has separately warned that investors have not been adequately cautioned about downside scenarios tied to companies such as OpenAI, whose valuation more than tripled between October 2024 and the following year.
For markets in the UK, US, Singapore, and East Asia’s chip-manufacturing hubs, the message from regulators is consistent: the innovation is real, but the financing structure underneath it has not been fully stress-tested against a reversal in sentiment.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


China’s AI-powered microdrama boom is changing more than television. From military history and political storytelling to international streaming platforms, Beijing sees new opportunities to communicate with audiences at home and abroad. But whether viral entertainment produces lasting political influence remains uncertain.
A fictional character delivers a dramatic line. Music rises. The screen cuts to black just as the story reaches its most emotional moment. Seconds later, the next episode appears, drawing viewers further into a digital world where entertainment, cultural identity and political messaging can increasingly overlap.
This is the landscape of China’s booming AI microdrama industry—and it is becoming a significant arena in the country’s broader effort to build technological capabilities and communicate its stories internationally.
In October 2026, the People’s Liberation Army’s news media centre entered this increasingly competitive space with The Iron Remembers, an AI-produced historical microdrama highlighted in a South China Morning Post investigation.
The production illustrates an emerging approach to public communication: turning subjects traditionally associated with official speeches, commemorations and documentaries into accessible serialized entertainment.
Yet the larger story extends far beyond state-produced videos. Chinese businesses are developing AI-powered storytelling tools, exporting mobile drama platforms, experimenting with synthetic actors and attracting support from local governments determined to build globally competitive digital industries.
Together, these developments raise a consequential question: Could China transform its commercial success in short-form entertainment into a new kind of cultural and political influence?
The answer depends not just on the content of the stories, but on who produces them, how they reach audiences and whether viewers actually change their attitudes.
Key Takeaways
- China is increasingly using AI-assisted microdramas in cultural communication, public education and official messaging.
- China’s broadcasting regulator reported more than 800 million domestic microdrama viewers and a market exceeding 100 billion yuan in 2025.
- Reuters reported 221,900 AI shows launched on Douyin during the first half of 2026, demonstrating the scale—and saturation—of the emerging market.
- Chinese-linked short-drama platforms are expanding overseas, although commercial popularity does not automatically translate into political persuasion.
- China’s new regulations encourage industry development while strengthening content oversight, rights protection and AI disclosures.
- The biggest unanswered question is whether repeated exposure to digital entertainment will produce measurable, lasting changes in international opinion.
What Are AI Microdramas?
AI microdramas are short, serialized video stories created with varying levels of artificial intelligence assistance. They are commonly designed for smartphones, with fast-moving plots, emotionally engaging characters and episodes that often last only a few minutes.
Unlike conventional television dramas, these productions generally emphasize quick engagement, frequent plot twists and a strong reason to continue watching.
Some are predominantly live-action productions using AI for editing, visual effects or translation. Others rely heavily on synthetic imagery, computer-generated characters, artificial voices and AI-assisted animation.
That distinction matters. A drama incorporating an automated subtitle tool is not equivalent to a production featuring wholly synthetic actors and environments.
The business model also differs from conventional television. Many services combine free introductory episodes with advertising, subscriptions or payments that unlock subsequent installments.
Platforms such as ReelShort, DramaBox and ShortMax demonstrate how this Chinese-developed entertainment model has reached overseas markets.
Researchers Jiaxin Yang and Dechun Zhang, writing for the London School of Economics’ Media@LSE, argue that microdramas are changing the relationship between cultural products and the platforms used to discover them.
That transformation has implications far beyond the entertainment business.
Why Beijing Is Embracing AI-Powered Political Storytelling
For decades, Chinese official communication relied heavily on newspapers, broadcasters, documentaries and organized political education.
These formats remain influential within China’s media system. However, they now compete for attention with entertainment platforms that offer highly personalized content and constantly refreshed viewing experiences.
Official institutions increasingly recognize that messages delivered through familiar digital formats may be more engaging than formal presentations.
The October 2026 example of The Iron Remembers illustrates this change.
According to SCMP’s reporting, the PLA news media centre produced the AI microdrama as part of a wider emergence of officially supported productions exploring Chinese history, public policy and national achievements.
Rather than simply delivering information, this type of content presents a narrative in which audiences follow characters, encounter conflicts and experience emotional resolutions.
The difference is strategically important.
A documentary may explain an institution’s interpretation of an event. A dramatic narrative can encourage viewers to identify emotionally with characters experiencing that event.
This does not mean audiences necessarily accept the intended message. But storytelling offers officials an additional means of reaching people who might otherwise ignore explicitly political material.
The Associated Press reported in April 2026 that China’s state media had embraced AI animation, satire and social media storytelling to communicate its interpretation of major international developments.
One example involved an animated depiction of the Iran conflict using symbolic animal characters to represent geopolitical actors.
Such productions demonstrate a deliberate move toward digital formats that can circulate across borders.
The difference between official messaging and ordinary entertainment
Not every Chinese-produced microdrama is a government publicity campaign.
The distinction is essential:
| Type of content | Typical purpose | Potential influence |
|---|---|---|
| Commercial microdramas | Attract viewers and generate revenue | Spread entertainment formats and cultural familiarity |
| Cultural and educational dramas | Promote history, tourism or public knowledge | Increase awareness of selected cultural and social themes |
| Officially sponsored productions | Communicate institutional priorities and narratives | Reinforce or promote particular interpretations of events |
| State-produced geopolitical animations | Present national or foreign-policy viewpoints | Shape discussion around international issues |
These categories can overlap, particularly when public institutions collaborate with private producers.
But treating every Chinese-owned entertainment application as a coordinated propaganda operation would go beyond the available evidence.
China’s AI Microdrama Industry Is Expanding at Extraordinary Speed
The economic scale of the sector helps explain why Chinese authorities and businesses have become deeply interested in its development.
According to figures presented by China’s National Radio and Television Administration and reported by the State Council Information Office in September 2026, microdramas had attracted more than 800 million viewers domestically.
The regulator said the industry exceeded 100 billion yuan, or approximately $15 billion, in 2025.
It also reported approximately 430,000 microdramas released in the first eight months of 2026, with more than 90% produced using AI technologies.
These are official industry figures. The definition of an AI-assisted production is important when interpreting them: using AI somewhere in a production workflow does not necessarily mean the entire drama was generated synthetically.
Independent reporting also points to explosive growth.
A Reuters investigation published September 25, 2026 cited industry data showing that 221,900 new AI shows launched on Douyin during the first half of 2026.
Only 1,055 exceeded 100 million views, underlining a crucial commercial reality: rapid production is not the same as guaranteed audience success.
China’s microdrama industry: Key figures
| Indicator | Reported figure | Source and period |
|---|---|---|
| Domestic microdrama audience | More than 800 million | Chinese broadcasting regulator, September 2026 |
| Domestic market size | Over 100 billion yuan | Regulator’s 2025 estimate |
| Microdramas released | Approximately 430,000 | Official figures, first eight months of 2026 |
| AI shows launched on Douyin | 221,900 | DataEye figures reported by Reuters, first half of 2026 |
| Shows exceeding 100 million views | 1,055 | Same Reuters-reported dataset |
The figures describe different datasets and should not be added together or treated as directly comparable.
What they collectively illustrate is a rapidly industrializing form of entertainment.
For government institutions interested in producing large volumes of educational or political content, this new production capacity offers substantial opportunities.
How AI Is Changing the Economics of Storytelling
Traditional filmmaking requires actors, production crews, physical sets, location arrangements and extensive post-production.
Generative AI can replace or accelerate some of those activities, particularly in animation, fantasy sequences, synthetic environments, translation and visual effects.
In its September investigation, Reuters reported that producing AI short dramas had become substantially cheaper in China during the first half of 2026.
The report cited state broadcaster CCTV’s estimate that production costs had fallen from approximately 5,000 yuan per minute to a few hundred yuan.
The figures refer to reported production costs, not an industrywide audited average, and actual expenditure varies considerably with quality and production techniques.
AI makes it possible to produce a scene that once required elaborate costumes, locations and physical sets with a much smaller team.
For a commercial studio, this can improve production economics.
For a communications organization, it can allow a wider variety of themes to be tested and distributed.
But AI does not eliminate the need for human editorial judgment.
Successful productions still require coherent writing, compelling characters, effective direction and an understanding of audience expectations.
Excessive reliance on automated content generation can also produce repetitive narratives, unrealistic performances and visual inconsistencies.
Reuters documented concerns about oversupply, copyright disputes, employment disruption and the unauthorized use of performers’ likenesses.
Those weaknesses could ultimately determine whether the industry’s rapid expansion is sustainable.
China’s Overseas Microdramas and the Rise of Platform Soft Power
The international implications are especially important.
China’s traditional cultural exports—including films, television series and literature—often reach foreign audiences as explicitly Chinese products.
Microdramas operate differently.
A Chinese-linked platform can commission stories featuring American actors, English-language dialogue and locations designed to appeal to viewers in North America.
Other productions can be adapted for Southeast Asian, European, Latin American or Middle Eastern audiences.
As a result, overseas viewers may consume entertainment developed within China’s digital media industry without necessarily knowing where its production and distribution system originated.
This is part of what researchers describe as platform soft power.
In their August 2026 analysis for Media@LSE, Yang and Zhang explain that cultural influence increasingly depends on the digital systems connecting entertainment to audiences.
Those systems include recommendation engines, app interfaces, monetization methods and the data generated through continuous viewing.
The important shift is from exporting a single recognizable cultural product to expanding an entire entertainment ecosystem.
An overseas audience might not develop a stronger attachment to China after watching a romantic drama. Nevertheless, repeated engagement can make a Chinese-developed entertainment format familiar and commercially successful.
Whether that familiarity eventually affects national perceptions is an empirical question, not an established outcome.
Soft power is not the same as propaganda
Soft power generally describes the capacity to attract and influence others through appeal rather than coercion.
Propaganda involves communication designed to promote a particular viewpoint or political objective.
A private company’s romantic drama can contribute to the international visibility of its creative industry without communicating any government position.
A military-produced historical animation has a different institutional purpose.
The most useful analysis therefore distinguishes between commercial influence, cultural exposure and directed political messaging.
Conflating them obscures the very mechanisms researchers are trying to understand.
From National History to Foreign Policy: AI’s New Role in Digital Communication
China’s official adoption of short-form storytelling is not limited to portraying its own history.
The Associated Press documented how Chinese state media used AI-produced animations to comment on international conflicts and criticize American foreign policy.
One prominent example featured a symbolic white eagle portraying the United States in an animated interpretation of the Iran conflict.
The creative approach matters because it gives complicated political events recognizable characters and a simple visual storyline.
A viewer does not have to read a diplomatic statement or understand extensive historical background to grasp the production’s intended viewpoint.
However, simplification carries risks.
Geopolitical conflicts rarely fit neatly into stories featuring heroes, villains and single causes.
When political communication adopts the techniques of popular entertainment, the distinction between explanation, persuasion and selective framing can become less obvious.
This challenge is not unique to China.
Governments, political movements and organizations around the world use emotional storytelling, social media influencers and short-form video to communicate with audiences.
AI increases the potential scale, speed and visual sophistication of these methods.
The core issue is whether audiences can identify the origin, purpose and evidentiary basis of the content they encounter.
Can AI Microdramas Actually Change Public Opinion?
This is the central question—and the available research calls for caution.
High view counts may demonstrate effective distribution or entertainment appeal. They do not, by themselves, prove that audiences have changed political beliefs.
In a 2026 study published in Comparative Political Studies, researchers Siyu Liang and Lachlan McNamee examined the persuasive effects of favorable messaging about China.
Their study used two survey experiments involving 4,800 respondents in China and the United States.
The researchers found that American respondents evaluated favorable messages about China more positively when they were delivered by an American rather than a Chinese influencer. The comparable approach did not persuade Chinese respondents in the same way.
This research examined influencer-based propaganda, not AI microdramas specifically. It therefore provides relevant evidence about audience identity and persuasion, but it cannot establish the effectiveness of synthetic storytelling.
Still, the finding suggests an important limitation for international messaging campaigns: credibility, audience identification and the messenger’s perceived authenticity can influence how information is received.
Meanwhile, wider international attitudes toward China remain mixed.
A Pew Research Center survey published in July 2025 found that a median of 36% of adults across 25 surveyed countries viewed China favorably, compared with 54% who held unfavorable views.
That survey predates the latest phase of the microdrama boom and does not measure exposure to these productions.
It provides context rather than evidence for or against their success.
To establish whether microdramas genuinely change opinions, researchers would need studies tracking exposure, political attitudes and lasting behavioral changes across different audiences.
Until such evidence exists, claims that AI-produced dramas are decisively reshaping international public opinion should be treated carefully.
China’s Government Is Supporting the Industry—and Tightening Its Rules
The microdrama boom is not developing without official oversight.
China’s National Radio and Television Administration has supported industry expansion while introducing measures governing production, distribution and content.
Its 2025 Micro Drama Plus initiative sought to integrate short dramas with tourism, legal education, science communication, traditional culture and other economic and social activities.
The program, outlined in a government announcement, illustrates how authorities regard microdramas as more than entertainment.
Such productions can also become tools for promoting regional destinations, industries and selected public-policy objectives.
A further regulatory milestone arrived in 2026.
China’s Microdrama Development Management Measures, published by its broadcasting regulator, took effect on September 1, 2026.
The rules define microdramas as serialized productions with individual episodes shorter than 20 minutes and establish a tiered oversight system.
They distinguish ordinary productions from those involving sensitive subjects such as politics, military affairs, diplomacy and national security.
The measures also support overseas production and international cultural exchanges.
This creates an important dual dynamic.
China wants its microdrama industry to innovate, expand internationally and generate economic value. At the same time, domestic regulators retain significant authority over which subjects and narratives may circulate.
The resulting balance between creative experimentation and regulatory control could shape the industry’s global competitiveness.
AI Disclosure, Copyright and the Risk of Synthetic Manipulation
The growing realism of AI-generated video introduces additional questions.
How can viewers determine whether a character is real?
Who owns the voice or appearance of a synthetic performer?
What happens when a politically sensitive animation is shared without its original source or context?
And should viewers receive clearer disclosures when they encounter state-produced or artificially generated material?
China introduced requirements for labeling AI-generated content effective September 2025, according to Reuters’ reporting on the regulations.
In September 2026, Chinese broadcasting officials also said AI-produced microdramas must carry appropriate labels and that platforms should verify permissions for the use of people’s voices and likenesses.
These developments reflect broader concerns about synthetic media.
The United Nations Educational, Scientific and Cultural Organization (UNESCO) has warned that realistic AI-produced material challenges people’s ability to distinguish authentic information from fabrication.
The risk is not simply that false images might be created.
It is also that genuine-looking content can circulate outside its original context, without information about who produced it, why it was created or whether it depicts actual events.
Those concerns are especially significant for historical reenactments and geopolitical storytelling, where audiences may interpret realistic images as documentary evidence.
For media organizations and digital platforms, clear disclosures and responsible attribution are becoming central questions of credibility.
Why China’s AI Microdrama Strategy Matters to the United States and the World
Chinese microdramas are part of a wider transformation in global media.
Three overlapping changes are occurring.
First, entertainment production is becoming more accessible. Small studios can use AI tools to produce material that previously required significantly larger budgets.
Second, distribution is increasingly platform-centered. Audiences discover stories through recommendations, social media advertising and mobile applications rather than traditional broadcast schedules.
Third, competition for attention has become international. A Chinese-developed storytelling model can compete directly for American, European or Southeast Asian viewing time.
These trends create commercial opportunities for businesses across multiple countries, including advertisers, creative professionals, app developers and digital distributors.
But they also raise questions about transparency, cultural representation, labor protections, intellectual property and the influence of platform recommendation systems.
For governments, understanding foreign digital-media ecosystems matters because entertainment, commercial technology and public communication can intersect.
For audiences, the challenge is distinguishing ordinary fiction from intentionally persuasive material without assuming that all foreign entertainment is politically directed.
For independent publishers, researchers and journalists, the responsibility is to examine production ownership, financial incentives, institutional sponsorship and evidence of actual audience effects.
That is more informative than judging influence solely by the nationality of an app developer or the number of times a video has been viewed.
The Next Phase of China’s AI Microdrama Expansion
Several trends are likely to shape the industry’s development after 2026.
The first is greater production efficiency. As AI video tools improve, studios may be able to create and localize dramas with smaller teams and shorter production cycles.
The second is quality-driven competition. When audiences have access to vast numbers of synthetic productions, compelling storytelling may become more important than the novelty of AI-generated visuals.
The third is international localization. Platforms seeking to succeed overseas will need to understand local languages, performers, cultural preferences and consumer protection requirements.
The fourth is closer regulatory scrutiny. Copyright disputes, synthetic likenesses, political messaging and platform transparency could become increasingly important policy issues.
Finally, measurement of influence will matter more.
The industry’s political significance should ultimately be judged not by the volume of material produced, but by the extent to which exposure affects attitudes, familiarity and behavior.
Those outcomes require evidence that remains limited today.
Frequently Asked Questions
What are Chinese AI microdramas?
Chinese AI microdramas are short, serialized digital videos produced with varying levels of artificial intelligence assistance. They commonly feature mobile-first storytelling, rapid plot developments and episodes lasting only a few minutes.
Why is China using AI microdramas for public communication?
AI microdramas allow official organizations to present history, culture and public-policy themes in familiar entertainment formats. They can also reduce some production costs and help organizations reach audiences who might not engage with traditional institutional messaging.
Are all Chinese microdramas political propaganda?
No. Many are commercial entertainment productions created primarily to generate revenue. Some are cultural or educational programs, while others are produced or commissioned by official institutions to communicate particular messages.
How big is China’s microdrama industry?
China’s broadcasting regulator reported more than 800 million domestic viewers and a market exceeding 100 billion yuan in 2025. The figures describe the broader microdrama sector, not exclusively AI-generated productions.
Are Chinese microdramas popular outside China?
Chinese-developed or China-linked platforms have attracted international audiences, with services operating across North America, Southeast Asia, Latin America and other markets. Their overseas popularity varies by platform, market and individual production.
Can AI microdramas influence political opinions?
They may contribute to awareness, familiarity and emotional engagement, but reliable evidence that AI microdramas themselves produce lasting political attitude changes remains limited. Popularity and persuasion should not be treated as the same outcome.
Does China regulate AI-generated microdramas?
Yes. China has introduced labeling requirements for AI-generated content and has established a regulatory framework for microdrama production and distribution, including additional scrutiny of certain sensitive subjects.
Final Analysis: The Battle for Attention Is Bigger Than Propaganda
China’s AI microdrama expansion is not simply a story about official messaging becoming more entertaining.
It is also about an emerging production industry, new international distribution systems, evolving cultural exports and increasingly sophisticated synthetic media.
Beijing’s interest is understandable: storytelling can reach audiences that conventional institutional communication often struggles to engage.
Private companies, meanwhile, see opportunities to build profitable global entertainment businesses around inexpensive production and mobile-first distribution.
These ambitions sometimes reinforce one another, but they should not be treated as identical.
A successful commercial application does not necessarily create political loyalty. Nor does a widely shared government-produced animation prove that its intended message persuaded viewers.
The deeper shift is that artificial intelligence has made sophisticated audiovisual storytelling easier to produce, adapt and distribute at scale.
The strategic question is no longer whether China can produce enormous quantities of digital content. It is whether that content can earn trust, sustain attention and generate meaningful cultural influence beyond the screen.
That is the test that will determine whether China’s AI microdrama boom becomes a lasting force in global media—or simply another wave of rapidly produced online entertainment.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The artificial-intelligence investment boom has become a story about the wider economy. Powerful chips require land, buildings, power, networking equipment, finance and a workforce able to assemble and operate complex sites. Corporate spending on these inputs can contribute to construction activity and supplier revenue well before the software applications built on top generate sustainable profits. That timing difference explains both the enthusiasm and the anxiety surrounding AI infrastructure in 2026.
Major technology firms are still scaling facilities, yet investors are increasingly examining the cost of capital, financing obligations and free cash flow. Reuters reported that expected AI-related expenditure from Microsoft, Alphabet, Amazon, Meta and Oracle was putting their future free cash flow under pressure. The analysis raised a basic problem: even if AI adoption rises, those developing the infrastructure may not all enjoy attractive returns simultaneously. Reuters cash-flow analysis.
What “capex” means in an AI context
Capital expenditure is money used to acquire or improve assets that provide value over multiple accounting periods. For an AI operator, it may include specialized chips, servers, network hardware, buildings, backup power, cooling and some internal infrastructure. Not every payment labeled “AI spending” is capex: cloud usage, electricity bills, software subscriptions and wages may be operating expenses depending on the arrangement and accounting rules.
This distinction matters because capex affects cash outlays at the time money is spent, while depreciation may spread the accounting cost of an asset across future years. A company can present strong operating earnings while experiencing weak free cash flow if investment is rising faster than cash from business activities. Conversely, a new infrastructure facility may depress cash flow now yet support profitable services in later years.
Follow the dollar through the AI supply chain
One dollar committed to a new data center does not flow entirely to a chipmaker. A share reaches semiconductors and networking equipment; another pays developers, construction contractors and utilities; still more goes to real estate, cooling and electrical equipment. Suppliers may benefit from the capital build-out even if the eventual model operator struggles to generate returns. This is why “AI winner” should not be used as a universal label for all companies tied to a project.
There are also lag effects. Chips can be ordered before a building is powered. A utility may build capacity over years. A software company may book subscription revenue only after the deployment is productive. Different stock sectors therefore respond on different timelines to the same underlying investment wave. For investors and policymakers alike, tracing cash flow across layers is more illuminating than repeating a single headline spending estimate.
Power has moved from a background cost to a constraint
Data centers require dependable electricity and increasingly sophisticated cooling. High-density clusters can demand large additions to local generation and network infrastructure, while grid connections may be slow. In October, Reuters reported that Black Hills planned $1.8 billion of investment between 2027 and 2029 to help power a proposed Google data center in Wyoming. That announcement is a real-world example of AI demand prompting multiyear energy investment, not evidence that every planned facility will open on schedule. Reuters utility-investment report.
Grid capacity also changes the competitive landscape. A company with access to power at an acceptable price may deploy assets faster than one waiting for an interconnection. Nearby households and businesses can face questions about cost-sharing, water use, land development and reliability. Responsible reporting should examine local approval documents and tariff structures rather than assume that large corporate investment automatically benefits or harms surrounding communities.
How capital spending affects headline economic growth
Business fixed investment is part of measured economic output, and construction or equipment purchases can stimulate activity. But spending itself should not be confused with productivity. A data center can contribute to investment today and still deliver a disappointing economic return if utilization is low or the services it supports cannot be sold profitably. Conversely, a project may have productivity benefits that show up only after companies redesign operations around the technology.
The broader economic test is whether AI helps firms deliver more output with the same resources, lower error rates, expand useful services or develop entirely new offerings. Business announcements often emphasize potential time savings. Readers deserve evidence from measured processes, audited costs and customer outcomes—not a promise that a single technological breakthrough will transform every workplace at the same speed.
Free cash flow may matter more than impressive spending plans
Free cash flow is often approximated as cash from operations minus capital expenditure, though companies may present adjusted versions with exclusions. As an analytical measure, it helps investors estimate how much cash remains for debt reduction, dividends, buybacks, acquisitions or additional investment. A business that repeatedly spends more than it generates must eventually manage the financing difference.
The Reuters analysis of hyperscaler spending highlighted expectations that incremental investment might absorb a large share of incremental operating cash generation. Some technology groups may comfortably fund the program; others may rely on borrowing, delayed distributions to shareholders or changes to project pace. Reuters.
A strong balance sheet provides flexibility, not immunity. Investors should assess debt maturities, interest costs, equipment useful lives and the contractual terms of customers who rent computing capacity. If equipment needs replacement quickly, the depreciation and reinvestment cycle can limit returns even when sales are growing.
The missing denominator: revenue per unit of compute
A useful return-on-investment framework divides durable economic benefit by the complete cost of producing it. For an AI data center, analysts might track revenue per available accelerator, revenue per megawatt, workload utilization, service margin, cost per output and customer renewal. Each measure can be distorted by product mix and contract duration; none should be used in isolation.
This is particularly relevant because lower inference costs can have opposite financial effects. They may reduce revenue per task but encourage far greater usage. Whether that improves profits depends on demand elasticity, competition and customer willingness to pay. The market is still discovering which AI services have the clearest repeatable business models and which are demonstrations searching for customers.
The financing environment makes the test tougher
The Federal Reserve increased its policy target in September to 3.75%–4.00%, and the 10-year Treasury yield remained above 5% in early October reporting. Federal Reserve; H.15 official yields. A higher discount rate can reduce the present value of profits expected years from now. It also affects the cost of borrowing for power facilities, real estate and AI operators.
That helps explain why investors can applaud near-term earnings from AI suppliers while questioning the financing models of downstream infrastructure projects. The system’s collective investment bill must ultimately be supported by profitable use or some participants will reprice their plans. Higher rates do not invalidate AI; they demand greater attention to when its financial benefits arrive.
Five signals that the boom is maturing
First, cloud providers disclose clearer AI-specific demand and customer retention rather than only capex totals. Second, power projects move from announcements to completed connections and reliable service. Third, customer adoption produces repeated operating results, not just pilots. Fourth, hardware utilization and useful life become easier to measure. Fifth, financing arrangements become less dependent on rising asset valuations or ever-larger capital raises.
There are also warning signals: canceled facilities, delays tied to electricity access, weaker supplier order growth, falling utilization, customer concentration or a widening gap between published accounting profit and cash flow. A weaker indicator in one quarter is not proof the overall AI market has peaked, but a combination of deteriorating measures warrants scrutiny.
The most balanced conclusion for 2026
The data-center build-out is real, but its profitability will not be distributed evenly. Equipment makers, utilities, contractors, cloud platforms and AI application developers occupy different points on the risk curve. One company may collect revenue upfront while another waits years to recover its costs. Economic growth from investment is only one side of the equation; the return on deployed capital is the other.
A durable editorial approach follows capacity, financing and customer benefits together. The next question is not whether the world will spend heavily on AI—that is visible in announced projects and corporate disclosures—but whether incremental spending continues to earn returns after the easy early adopters have been served.
Frequently asked questions
Capital spending by large cloud and technology operators on long-lived assets such as servers, buildings and infrastructure.
Does more data-center construction guarantee faster productivity growth?
No. Productivity depends on whether the resulting compute is used to produce economically valuable outputs.
Who benefits from AI electricity demand?
Potentially utilities, grid-equipment suppliers and constructors, subject to contracts, regulation, capital costs and project completion.
What is the main risk to the AI capex thesis?
Spending may rise faster than monetization, leaving high depreciation, financing commitments or underutilized facilities.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Palantir’s appeal in 2026 is not simply that it uses artificial intelligence. Many companies do. The market debate is whether the business can convert enterprise interest in AI into deployed systems that influence real operations, generate recurring customer spending and expand margins. Its latest published results show considerable momentum, while also raising the difficult question of how much growth investors should reasonably expect to continue.
The company’s software spans data integration, analytical workflows and AI-assisted operational decision-making. Buyers do not necessarily want another stand-alone chatbot. They want systems that connect permissions, proprietary information, business processes and people. That is the economic opportunity behind Palantir’s Artificial Intelligence Platform, or AIP. The term “AI sovereignty” appears prominently in company messaging, but buyers’ need to control where data goes and who can use it is a concrete business concern.
The fact check starts with reported figures
Palantir’s August 3 earnings release reported $1.935 billion in revenue for the quarter ended June 30, 2026, up 93% year over year. U.S. commercial revenue was $764 million, up 149%; U.S. government revenue was $809 million, up 90%. The company also reported $912 million in GAAP operating income and $1.194 billion in adjusted operating income. The GAAP and adjusted values use different definitions and must not be presented interchangeably.
These rates help explain the high visibility of PLTR among traders. But a growth rate describes the past period, while a share price discounts an uncertain sequence of future periods. A company can exceed every operational target and still disappoint an investor who assumed even more aggressive future progress. Readers should therefore assess the revenue base, customer retention, contract terms and operating cash flows alongside headline percentages.
What AIP customers may actually be buying
Business AI is often less about a model’s ability to produce fluent text than about whether it can operate within a secure workflow. An organization needs access controls, audit trails, approved data sources, validation of outputs and integration with existing software. These tasks are unglamorous, but they can determine whether a pilot becomes a permanent budget item.
Palantir argues that its platforms help customers move from prototypes into operational use. That is a company position, which can be evaluated with disclosed customer wins, recurring revenue and contract expansion. The more valuable deployment is one tied to a recurring process that management continues funding because it saves time, increases throughput or reduces losses. Projects based on temporary excitement without measurable benefits face greater renewal risk.
Why U.S. commercial growth deserves a separate lens
The company’s U.S. commercial growth has outpaced its global total, suggesting enterprise adoption is a leading driver. Yet percentage growth can eventually normalize as a revenue base becomes larger. Investors need both year-on-year and sequential comparisons, plus details about new-customer acquisition versus expansion of existing accounts. The latter can signal that a product grows more deeply embedded in customer operations.
Palantir disclosed $3.373 billion of total contract value signed in the quarter, with $2.132 billion attributed to U.S. commercial deals. The company explains that TCV can include options and is not equivalent to immediately recognizable or guaranteed revenue. Palantir SEC release and contract definitions. Responsible reporting should never sum contract announcements as if they were all cash collected in the current quarter.
The difference between a sales pipeline and a moat
A large potential contract can create investor enthusiasm but does not automatically mean a customer cannot replace the software. The durability of a platform business may depend on integration complexity, data quality, employee training, switching costs, procurement rules and the economic savings customers experience. Some contracts may be terminated or re-competed; others may expand for years.
A stronger moat test asks whether an enterprise would still renew when rival vendors offer cheaper models or broadly available AI tools. If Palantir controls crucial orchestration and monitoring layers, generic improvements in AI models could increase its value. If customers can reproduce the functionality through internal platforms, competitive pressure could rise. Both outcomes are plausible and should be monitored through retention and deal economics rather than assumed.
Government business brings scale—and scrutiny
Public-sector deals are an important component of Palantir’s business. They can support long deployments and mission-critical functionality, but they also invite debate about procurement transparency, privacy, national security and public dependence on particular vendors. The company faces scrutiny over some government use cases and contracts abroad; these debates are relevant to revenue risk even when the stock-market narrative focuses on AI adoption.
In October, the Financial Times reported on the cost and extension of Palantir’s work connected with the U.K.’s Homes for Ukraine program, a story that highlighted concerns around technology dependence and procurement choices. The report is relevant context, not evidence that every Palantir government contract is improper.
Companies working with public institutions must navigate political transitions, budget decisions and procurement requirements. An investor should ask how much revenue is exposed to a handful of large buyers and how the company manages security, compliance and public trust. Customer concentration can improve initial growth but also increase vulnerability to policy changes.
Cash flow is central to the valuation argument
Palantir’s reported $1.216 billion cash from operations and $1.220 billion adjusted free cash flow in Q2 provide evidence that its rapid growth was not solely a headline about future demand. These are company-reported measures, and adjusted free cash flow should be read alongside its reconciliation and exclusions.
Margins may reflect favorable software economics, but sustaining them while expanding staff, infrastructure and international reach is an open question. Investors should examine stock-based compensation, cash conversion, deferred revenue, capital requirements and recurring contract mix. A business with exceptional margins today may face new spending needs as deployment demands evolve or competition intensifies.
What would justify investor confidence?
Evidence would include repeated quarterly performance, durable commercial renewals, increasing value from existing customers, lower customer acquisition friction, limited dependence on any one buyer and transparent profitability measures. Palantir forecast third-quarter 2026 revenue of roughly $2.160 billion to $2.164 billion in its August release; this is management guidance, not a reported October result.
A skeptical reader may ask whether valuation already presumes these favorable developments. That is a reasonable question even when operational performance is exceptional. Conversely, strong growth can sometimes justify a high multiple if durability and market opportunity are underestimated. The key is to specify the evidence necessary for either interpretation.
The FinTwit signal, with context
Palantir appeared fourth by composite buzz score in an October 10 snapshot of one finance-specific X tracker. Such rankings reveal subject interest within a methodology, not a directional price forecast. Adanos. Social excitement can increase short-run share volatility, while enterprise contracts are usually negotiated over much longer periods. This mismatch between the market’s daily clock and business development’s quarterly or yearly clock explains why a fast-growing company can remain a battleground stock.
A useful weekly editorial dashboard would update company disclosures, major contract wins, analyst estimate changes and notable regulatory developments separately. That structure prevents repeated opinion pieces from drifting into unsourced hype.
Frequently asked questions
What did Palantir report for Q2 2026 revenue?
$1.935 billion, up 93% year over year, according to its August 3 SEC-hosted results.
Is AIP the same as a consumer chatbot?
No. Palantir positions its AI platform around enterprise data integration and operational workflows rather than a consumer-facing assistant alone.
Does total contract value equal booked revenue?
No. Contract values may include options or future periods and must be separated from recognized revenue and collected cash.
Why does government procurement matter to PLTR?
Government buyers can be major customers, but political, compliance, privacy and procurement decisions may affect contracts and future growth.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

Q3 2026 Earnings Preview: Can Record Profit Expectations Keep Wall Street’s Rally Alive?

Russia Diesel Deal 2026: Oil Prices and Inflation Risks

Fed Rates 2026: Treasury Yields, Bonds and SGOV Explained

S&P 500 Market Breadth 2026: Weak Rally or Rotation?

The AI Capex Boom: Data Centers Reshaping Growth

Palantir Stock in 2026: Extraordinary AI Growth

Tesla Physical AI 2026: Robotaxis, Optimus and TSLA Risks

NVIDIA’s AI Grip in 2026: Record Revenue Is Only Half the Investment Story

Hormuz Diesel Shortage: Why Crude Oil Recovery Isn’t Enough

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

Jeff Bezos Three-Day Workweek View: What He Really Said

Celeste Frozen Pizza Discontinued: What Conagra Confirmed

Oil Prices Break $100 in 2026: Middle East Conflict & Energy Markets

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

World’s Largest Economies: Ranking the Top Global Powers

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025