
Analysis
Ackman’s €55bn Gambit: Wall Street Reaches for the Soul of Music

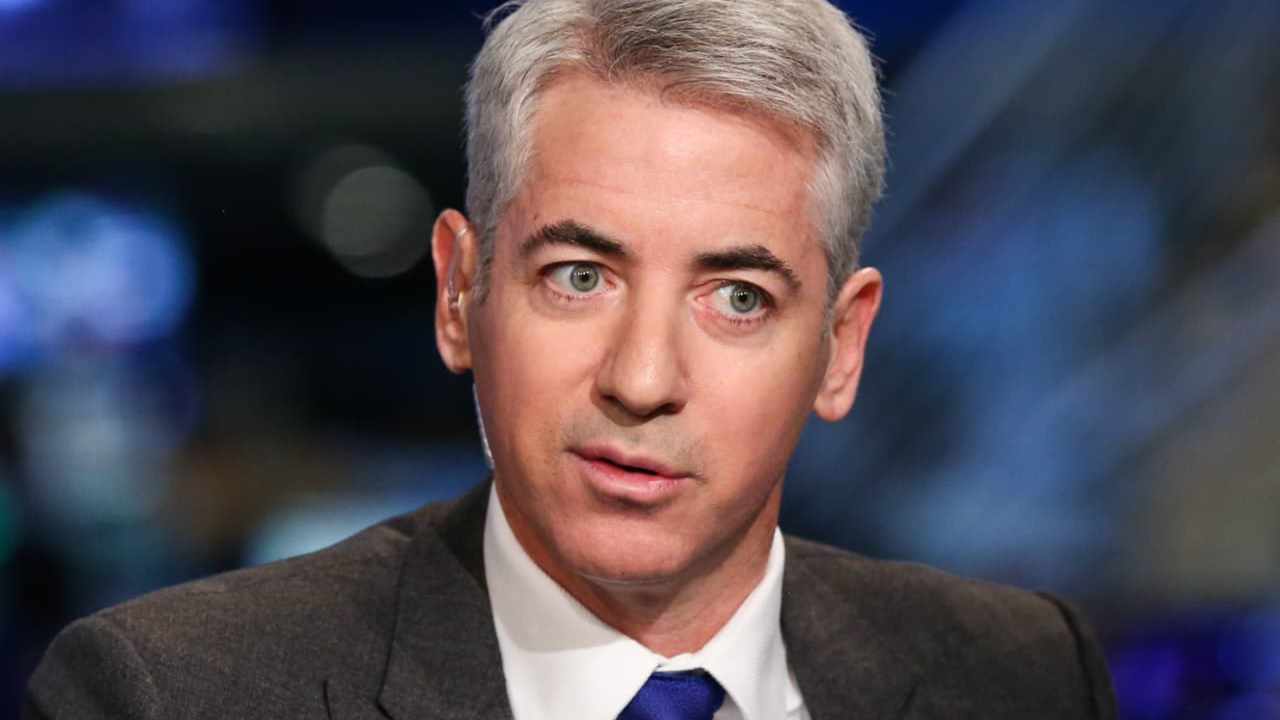
Bill Ackman’s Pershing Square bids €55.75bn for Universal Music Group — a bold SPARC merger, NYSE relisting play, and activist masterstroke that could reshape global entertainment finance.
There is a particular kind of audacity that separates the truly great dealmakers from the merely wealthy ones. It is the ability to look at a €31 billion company, one that controls the recordings of Taylor Swift, Drake, Lady Gaga, and The Beatles’ entire back catalogue — and declare, publicly, with the full force of a non-binding term sheet, that the world has been catastrophically wrong about its value. Bill Ackman did exactly that on Tuesday morning, submitting a €55.75 billion proposal to the board of Universal Music Group that is simultaneously a takeover bid, a structural intervention, a corporate governance manifesto, and perhaps the most consequential single act in the history of music-industry finance.
The numbers alone are theatrical. Pershing Square’s cash-and-stock deal, worth approximately €55.8 billion ($64.4 billion), would see UMG shareholders receive a total of €9.4 billion in cash and 0.77 shares of new stock for each share currently held. That equates to roughly €30.40 per share — a 78% premium to last week’s closing price of €17.10. In a market still nursing tariff-induced vertigo, it reads less like a merger proposal and more like a declaration of war against misvaluation itself.
The Deal, Deconstructed: What Ackman Is Actually Proposing
Strip away the financial engineering and what emerges is a thesis of elegant simplicity: Universal Music Group is one of the finest businesses on the planet, systematically mispriced by structural noise. Pershing Square cited six specific factors it believes have depressed UMG’s stock: uncertainty over the Bolloré Group’s 18% stake; the postponement of a US listing; balance sheet underutilisation; the absence of a disclosed capital allocation plan; a failure of investors to credit UMG’s €2.7 billion Spotify stake in its valuation; and what Ackman termed “suboptimal” shareholder communications.
Each point is surgical. Each is addressable. Together they constitute not a diagnosis of a failing business — Ackman himself praised CEO Sir Lucian Grainge effusively — but a bill of indictment against the governance architecture surrounding an excellent one. “Since UMG’s listing, Sir Lucian Grainge and the company’s management have done an excellent job nurturing and continuing to build a world-class artist roster and generating strong business performance,” Ackman said, before pivoting: “UMG’s stock price has languished due to a combination of issues that are unrelated to the performance of its music business.”
Under the proposed structure, Pershing’s SPARC Holdings would merge with UMG, and the combined entity — incorporated as a Nevada Corporation — would be listed on the New York Stock Exchange. The cash component, funded through SPARC’s rights holders, committed debt financing, and proceeds from Pershing’s Spotify stake, is carefully calibrated. It is designed primarily to offer the Bolloré Group — holder of an 18.5% stake that has hung over UMG like a Gallic storm cloud since its 2021 Euronext Amsterdam listing — a clean exit.
Pershing Square said all equity financing would be backstopped by itself and its affiliates, with debt financing committed at signing, and expects the deal to close by end of 2026.
The proposed deal mechanics, summarised:
| Element | Detail |
|---|---|
| Total deal value | ~€55.75bn ($64.4bn) |
| Price per share | €30.40 (78% premium to last close) |
| Cash component | €9.4bn (€5.05/share) |
| Stock component | 0.77 shares of New UMG per UMG share |
| Vehicle | Pershing Square SPARC Holdings (SEC-registered SPARAC) |
| New listing | New York Stock Exchange |
| Target close | End of 2026 |
| Board refresh | Michael Ovitz proposed as chair; 2 Pershing Square directors |
Why Ackman Wants the World’s Biggest Music Machine
The superficial answer is that Ackman saw a bargain. UMG has lost 26% of its market value in the past 12 months and was valued at just €31.4 billion before Tuesday’s announcement — a staggering discount for a company that generates consistent double-digit earnings growth and sits at the absolute commanding heights of intellectual property capitalism.
But the deeper answer is structural. Ackman purchased 10% of UMG in 2021 through a deal with Vivendi at approximately €18.27 per share, making him an early believer in its potential. Since then, he has watched the share price grind lower despite the business performing admirably — revenues and earnings growing at 11% and 13% per year respectively, while the Amsterdam listing provided insufficient liquidity and suppressed institutional access for US investors unable to purchase non-US-listed securities.
This is, at its core, a thesis about listing arbitrage — the premium that New York capital markets attach to great businesses versus their European equivalents. The S&P 500 trades at roughly 20x forward earnings. Amsterdam’s AEX sits closer to 13x. For a business of UMG’s quality and growth trajectory, that gap represents tens of billions in unrealised value. Ackman intends to unlock it via relisting.
There is also the artist economy argument, which deserves more attention than it has received. The music industry’s economics have been fundamentally restructured by streaming. Spotify, Apple Music, and their successors have converted what was once a lumpy, piracy-damaged revenue model into something approaching a recurring subscription business. UMG, home to global artists including Taylor Swift, Drake, and Lady Gaga, was spun out of Vivendi and listed on Euronext Amsterdam in 2021 with an initial valuation of €46 billion — and the business case for premium valuations has only strengthened since as streaming penetration has deepened globally. The irony is that UMG has executed precisely the transformation it promised, and the market has responded with indifference.
The Blank-Cheque Masterstroke: SPARC, Not SPAC
Much will be written conflating this deal with the SPAC boom of 2020-21 — that frothy, ultimately discrediting period of blank-cheque company proliferation that ended in regulatory scrutiny and spectacular write-downs. The conflation is understandable but wrong.
Pershing Square SPARC Holdings is technically a SPARAC — a Special Purpose Acquisition Rights Company — a vehicle Ackman designed precisely to avoid the structural defects of its SPAC predecessor. Where traditional SPACs forced investors to commit capital before a deal was identified, SPARAC rights holders only invest once a specific target is announced and they have full information to evaluate it. There is no dilutive warrant structure. There is no forced redemption dynamic. The optionality resides entirely with the investor, not the promoter.
It is, in essence, a rights-based acquisition vehicle that aligns incentives in ways the original SPAC format catastrophically failed to do. The SEC registered SPARC Holdings four years ago, and Ackman has been patient — waiting, as great investors do, for a target worthy of the vehicle’s ambition. Universal Music Group, one suspects, was always the destination.
Pershing’s move comes after UMG last month delayed a plan for a US listing, walking back on an agreement with Pershing, which had exercised its right to request a US offering and had argued a New York listing would boost UMG’s share price and liquidity. That reversal appears to have been the proximate trigger. When the elegant solution — a consensual secondary listing — was blocked, Ackman reached for the bolder instrument: full acquisition.
Strategic and Cultural Implications for the Music Industry
The implications extend far beyond the balance sheet. Universal Music Group is not merely a large corporation; it is, in important respects, the custodian of recorded culture. It controls the catalogues of artists spanning a century of popular music — from The Beatles to Bad Bunny — and its decisions about licensing, royalties, artificial intelligence, and streaming economics ripple through the entire creative ecosystem.
Ackman’s proposed governance changes are, on balance, more activist than revolutionary. He wants Michael Ovitz, the former CAA co-founder and Walt Disney president, to chair the board, alongside two Pershing Square representatives as directors. Ovitz’s reputation in talent representation and entertainment strategy is formidable; his appointment would signal a reorientation toward artist relationships and content strategy, not merely financial engineering.
The AI dimension cannot be overstated. Music labels are currently engaged in a defining legal and commercial battle over the use of their catalogues to train AI systems. UMG has been among the most aggressive in asserting rights — suing AI audio companies and demanding licensing frameworks. A NYSE-listed UMG, with a US activist shareholder structure and American governance norms, will likely pursue this battle with greater institutional firepower and investor support. American capital markets tend to reward IP maximalism. The implications for artists, AI companies, and streaming platforms are profound.
Key stakeholders and their likely positions:
| Stakeholder | Position | Strategic Implication |
|---|---|---|
| Bolloré Group (18.5%) | Seeking exit; cash component designed for them | Deal cannot proceed without their support |
| Vivendi (~10%) | Complex position as ex-parent | Likely supportive if premium maintained |
| Sir Lucian Grainge (UMG CEO) | Praised by Ackman; contract renegotiation proposed | Retention critical; may seek enhanced terms |
| UMG Artists | No direct vote; indirect interest in stability | NYSE listing may attract greater US investor coverage |
| Spotify | UMG holds €2.7bn stake | Complex licensing interdependence; deal may reassess |
Financial Engineering and Market Reaction
The market’s immediate verdict was unambiguous. UMG shares jumped as much as 28% in early Amsterdam trading following the announcement, before paring gains to trade approximately 15% higher. The stock had been down roughly 11% year-to-date entering Tuesday. Shares of Vivendi and the Bolloré Group were both higher — Vivendi up 11% and Bolloré up 6.3% — a clear signal that the broader conglomerate structure around UMG views this as a liquidity event long overdue.
The valuation case is compelling when stress-tested. UMG generates approximately €10 billion in annual revenues with EBITDA margins expanding toward the mid-twenties as streaming cost structures mature. Apply the multiple of peers — compare it to, say, Live Nation’s trading multiples or the private market transaction comps for music IP — and €30.40 per share begins to look not generous but fair. The 78% premium to a depressed share price does not, in this analysis, represent aggressive overpayment. It represents correction of a persistent anomaly.
The Spotify stake alone — valued at approximately €2.7 billion — represents nearly 9% of UMG’s current market capitalisation and has never been adequately reflected in analyst valuations. In the transaction structure, its monetisation becomes explicit rather than embedded and ignored.
One structural observation deserves attention: 17% of UMG shares will be bought back and cancelled as part of the transaction, concentrating ownership in the new entity while reducing dilution for remaining shareholders. This is the quiet architecture of a deal designed to maximise value in the hands of long-term holders rather than short-term arb traders.
Risks, Regulatory Roadblocks, and Counter-Moves
This is where intellectual honesty demands a departure from the deal’s considerable charms.
The Bolloré problem is real, and it is large. Nicolas Marmurek, an analyst at M&A specialists Square Global, noted bluntly: “Unless Bolloré supports the move, the proposal looks very much dead from the start. We doubt Bolloré will accept such terms.” The Bolloré Group is not a passive portfolio investor; it is a French conglomerate with its own regulatory entanglements, a controlling patriarch in Vincent Bolloré, and a history of strategic opacity. The cash component — €9.4 billion — is designed to offer them an exit. Whether they want an exit, on these terms, at this moment, is the $64 billion question. Literally.
Regulatory complexity compounds this. A transaction of this scale, involving a Dutch-listed company with French shareholders, a US acquisition vehicle, and a proposed NYSE relisting, traverses at least three major jurisdictions and regulatory regimes. EU merger control, Dutch financial market authority oversight, SEC registration requirements, and French market regulator AMF scrutiny of the Bolloré/Vivendi stake all represent genuine friction — not necessarily fatal, but time-consuming and expensive. Ackman’s year-end target may prove optimistic.
There is also the question of what this deal does to competitive dynamics. A US-listed, Pershing Square-controlled UMG would face heightened scrutiny in its licensing and AI negotiations — both from counterparties emboldened by antitrust concern and from legislators increasingly attentive to Big Culture’s market power. Warner Music Group and Sony Music, UMG’s two major competitors, will not be passive observers. Both have the scale and relationships to complicate regulatory approval processes.
Finally — and this is rarely discussed — there is the artist dimension. Major recording artists command extraordinary negotiating leverage in 2026. The consolidation of ownership around activist shareholder structures has historically produced cost discipline that artists and their managers experience as pressure on royalty terms and advance commitments. Any perception that a Pershing Square-controlled UMG would prioritise financial returns over artist relationships could accelerate the movement toward independent labels, direct licensing, and artist-owned catalogues that has already begun reshaping the industry’s edges.
My Expert Opinion: The Bigger Picture for Global Entertainment and Capital Markets
Let me be direct: this is one of the most interesting large transactions attempted in global capital markets in years, and it is more likely to succeed than the sceptics assume — but for reasons that extend beyond the deal’s immediate mechanics.
Bill Ackman is not primarily a music industry investor. He is a capital allocation activist who identified, five years ago, that the world’s most valuable IP business was being systematically underpriced by European listing constraints and governance ambiguity. The SPARC vehicle, the Lucian Grainge relationship, the Bolloré exit structure — none of this is improvised. This is the end of a long-form strategic play, executed with the patience and deliberateness that distinguishes Ackman’s best campaigns from his more turbulent episodes.
The broader thesis — that great businesses listed in small-liquidity markets are systematically undervalued relative to NYSE-listed equivalents — is not just true; it is increasingly obvious to sophisticated allocators globally. Arm Holdings’ relocation to Nasdaq, the parade of European companies exploring dual listings, the premium that US institutional capital demands for domestically-listed assets — all of these are manifestations of the same phenomenon Ackman is now monetising at scale.
For the music industry specifically, a successful UMG-Pershing transaction would have generational consequences. It would cement music IP as a mainstream institutional asset class, driving capital allocation toward royalty funds, catalogue acquisitions, and artist-equity structures at a scale that would transform the economics of every recording artist signed to a major label. The money that follows a NYSE-listed, S&P-eligible Universal Music Group into the sector would dwarf the private equity inflows of the past decade.
And on AI: a better-capitalised, US-governance-aligned UMG will be a more formidable adversary for technology companies seeking to licence or circumvent music rights. That is good for artists, good for label economics, and potentially very good for the broader case that creative IP deserves robust legal protection in the generative AI age.
Forward-Looking Outlook: Three Scenarios
Scenario A — The Deal Closes (Probability: ~45%): Bolloré agrees to the cash exit terms; UMG’s board, satisfied with the governance concessions and premium, recommends acceptance; regulatory approvals are secured by Q3. New UMG lists on NYSE in December 2026, immediately entering institutional indices, attracting US-oriented fund flows, and trading at a multiple that vindicates Ackman’s thesis. The 0.77-share component ultimately prices above the implied €30.40 equivalent. Ackman books one of the great activist trade completions.
Scenario B — Partial Success (Probability: ~35%): Bolloré refuses the exit terms; Ackman’s public pressure, however, forces UMG’s board to commit to a US listing without the full merger. A secondary NYSE listing proceeds in 2027, share price recovers meaningfully, and Pershing’s existing stake is vindicated without the complexity of full acquisition. Messier, but profitable.
Scenario C — Collapse (Probability: ~20%): Bolloré, exercising shareholder veto power, rejects the terms. Regulatory pushback in France and the Netherlands proves intractable. Ackman withdraws; UMG shares give back their premium; the saga continues. Even in this scenario, the public articulation of UMG’s undervaluation likely places a floor under the stock that did not exist before Tuesday morning.
In all three scenarios, one thing is clear: the world’s most valuable music business will never be invisible again.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.



Key Takeaways
- Rolex’s secondary market rose approximately 7.9% year-over-year as of 2026 (per WatchCharts data) — trailing Patek Philippe (+16.2%) and Tudor (+11.4%) but still outperforming Audemars Piguet (+3.4%).
- Rolex raised U.S. retail prices 4–9% in January 2026 (steel models ~5.6%, gold models ~8.7%), narrowing the historical gap between retail and pre-owned pricing.
- Not every model appreciates: steel sports references (Submariner, GMT-Master II, Daytona) have held value far better than two-tone or widely available dress references like the standard Datejust.
- The Lady-Datejust posted the sharpest 2026 gain among tracked collections — up 22.73%, from roughly $9,269 to $11,376 — driven by demand for smaller, “everyday luxury” watches.
- Gold’s rise past $2,400/oz has directly lifted the investment case for Rolex’s precious-metal references (Day-Date, Sky-Dweller, Yacht-Master).
The Model-by-Model Picture
| Category | 2026 Trend |
|---|---|
| Lady-Datejust | +22.73% (strongest performer among tracked collections) |
| Steel sports models (Submariner, GMT-Master II) | Held value well; corrected from 2022 peak but stabilized above retail |
| Daytona | Corrected from highs above $50,000 to the mid-$30,000s; still among the most sought-after references |
| Two-tone/widely available Datejust | Flat to negative — “holds value” is an overstatement for this category |
| Gold references (Day-Date, Sky-Dweller) | Lifted by gold’s rise above $2,400/oz |
Why the “Rolex Always Appreciates” Myth Is Fading
The pandemic-era boom pushed some references — the Daytona above all — to speculative highs disconnected from historical norms. Since the March 2022 peak, steel sports models have compressed meaningfully, and dealers who bought inventory near the top have in some cases faced 20–40% markdowns on liquidation. The lesson for 2026 buyers: Rolex as a category is not a monolith. Value retention depends heavily on specific reference, condition, and whether the piece comes with box and papers (“full set”).
What’s Actually Driving 2026 Strength
- Retail price increases raise the floor. When a new Submariner retails at $10,050 (up from $9,500), a pre-owned example at $11,000–$12,000 suddenly represents a smaller premium — narrowing the gap without secondary prices actually moving.
- Supply discipline remains Rolex’s core lever. The brand has never confirmed production numbers, and secondary-market premiums remain entirely a function of Rolex’s own manufacturing decisions — a risk factor as much as a support.
- Certified Pre-Owned rollout. Rolex’s now fully rolled-out CPO program has changed how buyers transact in the used market, adding a layer of brand-verified legitimacy that supports pricing.
The Case for Rolex as a Portfolio Diversifier
Financial advisors increasingly frame luxury watches not as a replacement for equities or bonds, but as a tangible, historically low-correlation diversifier — one that carries its own risks (illiquidity, condition-dependent pricing, no yield) but has demonstrated multi-decade resilience for specific references.
Is Rolex a good investment in 2026?
It depends heavily on the specific reference. Steel sports models like the Submariner and Daytona have held or grown in value; two-tone and widely available dress models generally have not. Overall, Rolex’s secondary market rose about 7.9% year-over-year in 2026, trailing Patek Philippe but ahead of Audemars Piguet.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Navigating Mortgage and Loan Refinancing in a High-Yield Environment
Global public debt crossing critical thresholds has kept central bank policies volatile, resulting in fluctuating US Treasury yields throughout 2026. For homeowners and commercial property holders burdened by previous high-interest borrowing cycles, finding optimal refinance windows has become a high-stakes financial puzzle. Stalled disinflation and stubborn employment numbers mean rate cuts are incremental, requiring borrowers to act with precision.
Timing your mortgage or commercial loan refinance in this environment requires a deep understanding of yield curve movements and lender risk appetites.
Decoding 2026 Refinance Dynamics
The 10-Year Treasury Yield Benchmark
Mortgage rates continue to track closely with the 10-year US Treasury yield. When macroeconomic anxiety spikes debt issuance, yields rise, tightening consumer borrowing capacity. Savvy borrowers monitor weekly Treasury auctions to lock in rates during brief dip windows.
Hybrid ARMs and Alternative Structures
With fixed rates remaining elevated, 7/1 and 10/1 adjustable-rate mortgages (ARMs) have surged in popularity. These products offer lower initial monthly payments, giving borrowers breathing room until central bank easing cycles fully materialize.
| Loan Product | Current Rate Range | Best For | Key Risk Factor |
| 30-Year Fixed Mortgage | 6.2% – 6.8% | Long-term predictability | Higher initial monthly outlay |
| 7/1 Hybrid ARM | 5.5% – 5.9% | Short-term ownership / flipping | Rate reset risk after year 7 |
| Commercial Refinance | 7.0% – 8.2% | Corporate asset restructuring | Strict DSCR lender covenants |
Actionable Steps for Successful Refinancing
To maximize your chances of securing favorable refinance terms in a volatile market, follow a disciplined preparation strategy.
Boost Your Credit Score Immediately: Lenders in 2026 are applying stringent credit tiering; a 20-point increase can drop your APR by a crucial quarter-point.
Shop Regional Credit Unions: Smaller financial institutions often offer portfolio loans with more flexible underwriting than major national banks.
Calculate the Break-Even Point: Ensure your total closing costs are recouped through monthly savings within 24 months of closing.
“Market Strategist View: Refinancing in 2026 is an exercise in opportunistic timing. Borrowers must maintain immaculate financial profiles ready to strike the moment Treasury yields dip.”
Mastering the complexities of today’s debt environment ensures you can successfully lower your debt service costs and protect your long-term financial stability.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

The days of pulling generic auto insurance quotes based purely on your zip code and age are officially over. In 2026, insurance comparison engines are powered entirely by generative AI and real-time telematics. These platforms digest thousands of live data points—ranging from your driving smoothness via connected vehicle sensors to real-time traffic congestion patterns—to generate hyper-personalized premiums instantly.
For consumers, this evolution represents both a massive opportunity for savings and a hidden trap for penalty pricing. Understanding how AI algorithms evaluate risk is essential for anyone looking to lower their monthly auto insurance premiums.
How AI Comparison Engines Evaluate Your Risk Profile
Behavioral Telematics and Connected Cars
Modern cars stream performance data directly to insurance aggregators. Generative AI models analyze braking sharpness, acceleration curves, cornering G-forces, and phone distraction metrics. Drivers who maintain smooth, defensive habits are rewarded with dynamic rate cuts of up to 40% compared to traditional rating tiers.
Predictive Traffic and Weather Modeling
AI tools now cross-reference your daily commute route with predictive weather and accident probability models. If your standard parking location or driving corridor has a statistically higher incidence of uninsured motorist claims, your quotes will reflect that hyper-local risk assessment.
| Comparison Factor | Traditional Rating Model | 2026 Generative AI Model | Impact on Premium |
| Mileage & Usage | Annual estimated odometer reading | GPS tracking & live trip duration | High (up to 35% savings) |
| Driving Behavior | MVR driving record & accidents | Real-time braking, speed, & G-force | Critical (determines tier) |
| Vehicle Tech | Make, model, and safety rating | ADAS calibration & repair cost data | Moderate |
Strategies to Lower Your AI-Driven Insurance Quote
To outsmart the algorithm and secure the lowest possible premium in 2026, drivers must proactively manage their digital footprint on insurance platforms.
Opt-In for Telematics Trial Periods: Many insurers offer immediate 15% discounts just for installing their driving app; let it track safe habits for 30 days to lock in permanent savings.
Scrub Unverified Public Records: Ensure your motor vehicle report is free of clerical errors that AI risk models misinterpret as reckless behavior.
Compare AI Aggregators: Use platforms that integrate multi-carrier API feeds rather than single-brand comparison sites to find the best risk-adjusted rate.
“Industry Note: AI-driven pricing rewards transparency and precision. Drivers who actively manage their telematics data consistently out-save those relying on legacy quote calculators.”
Embracing AI comparison tools allows savvy policyholders to customize coverage limits precisely to their driving habits, eliminating wasted premium spend while ensuring robust protection.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Social Security 2027 COLA Announcement: Date, Formula and What Retirees Should Check

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

Q3 2026 Earnings Preview: Can Record Profit Expectations Keep Wall Street’s Rally Alive?

Russia Diesel Deal 2026: Oil Prices and Inflation Risks

Fed Rates 2026: Treasury Yields, Bonds and SGOV Explained

S&P 500 Market Breadth 2026: Weak Rally or Rotation?

The AI Capex Boom: Data Centers Reshaping Growth

Palantir Stock in 2026: Extraordinary AI Growth

Tesla Physical AI 2026: Robotaxis, Optimus and TSLA Risks

NVIDIA’s AI Grip in 2026: Record Revenue Is Only Half the Investment Story

Hormuz Diesel Shortage: Why Crude Oil Recovery Isn’t Enough

Social Security Extra $90 Deposit: Who Qualifies for the October 2026 Medicare Rebate?

Anthropic Bans Sustained Abuse of Claude AI Under New Usage Policy Effective November 12, 2026

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

World’s Largest Economies: Ranking the Top Global Powers

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025