
Treasury
Treasury Yields and Inflation 2026: What Bond Moves Mean for Borrowers

Long-term Treasury yields connect bond markets to household borrowing and asset values. Higher yields can benefit new savers while hurting some borrowers and existing bondholders. Original research October 12; updated October 15, 2026. Verify newer developments before publication.
Unexpected inflation can raise the expected interest-rate path and alter equity valuations and borrowing costs. Yield changes and bond-price changes move in opposite directions for an otherwise similar fixed-rate bond. Source. Historical material further below is contextual and must not be mistaken for a live quotation or price.
What changed since the original research cutoff
Unexpected inflation can raise the expected interest-rate path and alter equity valuations and borrowing costs. Yield changes and bond-price changes move in opposite directions for an otherwise similar fixed-rate bond. The publication date and observation time are crucial: market prices, competition results and government announcements cannot be extrapolated from an earlier snapshot. A more useful reader question is what remains current today and what requires verification at the moment of a financial or travel decision. The new development should be checked against the primary or contemporary reference rather than assumed from an older headline.
What is happening and why readers are searching
Long-term Treasury yields are the price signal linking government borrowing, mortgages, growth-stock valuations and the return available on safer assets. Reuters has highlighted an unusual 2026 divergence: shares near highs while longer-term bond yields have climbed. A bond yield is not the same as the Federal Reserve policy rate, and a large move in either can affect people differently depending on whether they borrow, save or invest. Sources: Reuters bond market analysis and Reuters market breadth.
The important context competitors can overlook
Bond prices generally fall when market yields rise. That inverse relationship explains why holders of long-duration bond funds can suffer losses even as the yields offered to new buyers become more attractive. Mortgage rates also reflect lending spreads, credit risk and other factors, so a single Treasury number cannot predict a specific home-loan offer. Companies with distant expected cash flows may be particularly sensitive to higher discount rates. For primary-source checks and current reporting, see Reuters bond market analysis and Investor.gov. The key distinction is translate bond math into household decisions.
A practical way to use this information
Compare yields at consistent maturities rather than mixing two-year and ten-year readings. A homebuyer should assess monthly payment affordability at an actual lender quote. A saver choosing between a short-term bill and a long-term fund should consider liquidity needs and interest-rate risk. For an investor, the useful question is what rate assumptions are embedded in a company valuation, not whether “6%” makes a dramatic headline.
A simple rate-shock example
Imagine an existing long-duration bond fund whose duration is eight years. A simplified duration approximation suggests a one-percentage-point increase in yield could mean about an 8% price decline, before convexity, income and other effects. This is illustrative, not a forecast for a named fund. A short-term Treasury instrument with far lower duration usually reacts less to the same yield shock.
That distinction makes a practical difference for readers considering an emergency fund versus retirement money they can invest for a decade. The current market narrative described by Reuters should prompt a discussion of time horizon, not a blanket instruction to abandon bonds.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Are higher Treasury yields always bad? No. New fixed-income savers may earn more, while existing long-duration bond prices can decline.
Does the Fed set the ten-year Treasury yield? No. It influences conditions, but market expectations and term premiums also matter.
Why the ten-year yield influences everyday borrowing
The 10-year U.S. Treasury yield is an important benchmark for longer-term financing because it reflects the return investors require to hold government debt with that maturity. Mortgage rates do not equal the 10-year yield, but lenders consider Treasury markets, mortgage-backed securities, credit risk, servicing costs and competition when setting offers. If investors demand a higher return across long-term bonds, mortgage borrowing can become more expensive even without an immediate increase in the Federal Reserve’s short-term policy rate.
Suppose a buyer finances $300,000 over 30 years with a fixed-rate mortgage. At an illustrative 6% annual interest rate, principal and interest are roughly $1,799 per month; at 7%, they are roughly $1,996. The difference of about $197 per month excludes taxes, insurance, fees and other ownership costs. It demonstrates why a change in borrowing conditions can outweigh a modest change in a home’s asking price. Real quotes depend on the borrower’s circumstances and market conditions, not merely the Treasury yield reported in a news article.
Why bond prices and bond yields move in opposite directions
A conventional fixed-coupon bond promises specified payments. When newly issued securities offer higher yields, an existing bond with a lower coupon generally must trade at a lower price to attract buyers. The opposite happens when market yields fall. Duration measures a bond’s sensitivity to interest-rate changes. As an approximate illustration, a portfolio with an effective duration of seven years could lose about 7% in price if relevant yields rise by one percentage point, before other effects. The relationship is approximate and can vary with convexity, changing spreads and portfolio holdings.
For savers, a higher yield can be welcome if they are buying newly issued securities and can hold them under suitable circumstances. For owners of existing long-duration bonds, the same move can produce mark-to-market losses. Investors seeking near-term stability should understand the distinction between a bond’s redemption terms and the market price they might receive if they must sell before maturity. Credit risk also differs between Treasury securities and corporate or municipal bonds.
The yield curve tells a story, but not one prediction
The yield curve plots interest rates across maturities. Its shape can reflect expectations for growth, inflation, monetary policy and compensation for holding longer bonds. An inverted curve has often been studied as a recession signal, yet neither inversion nor steepening guarantees a specific economic outcome. A steepening curve may arise because investors expect stronger future activity, higher inflation or greater long-term borrowing supply. The underlying cause matters more than the shape alone.
Distinguish nominal yields from real yields after expected inflation. If a nominal Treasury yield rises because inflation expectations rise, the investor’s purchasing-power return may not improve nearly as much as the headline suggests. Treasury Inflation-Protected Securities provide another reference point, though their market prices and practical suitability also require care. Useful analysis compares inflation expectations, real yields and nominal yields rather than describing all higher rates as a sign of healthy growth.
A decision framework for households
Borrowers should compare multiple complete loan offers, including interest rate, annual percentage rate, closing costs and applicable points. A lower headline rate with very large upfront fees may not be cheaper for someone planning to move or refinance. Depositors should distinguish variable savings-account APYs from yields locked by certain fixed-term products. Bond-fund investors should review duration, credit quality, expenses and possible withdrawals. Stock investors should consider how higher discount rates affect the value assigned to future profits, particularly where profits are expected many years ahead.
No single financial product becomes universally best because yields reach a round number. A retiree seeking predictable cash flow, a first-time homebuyer and a technology-company investor face different tradeoffs. Their financial decisions are better guided by time horizon, liquidity and risk tolerance than by a prediction of where the yield will be next week.
The key variables to monitor
For a coherent market story, compare the 2-year and 10-year Treasury yields, current Fed communications, the latest inflation data and changes in bond-market liquidity. Track the time at which each observation was made. Also distinguish a policy announcement from a market-implied forecast; futures pricing can change significantly with new information. Where a report cites a historic high, specify the exact maturity and comparison period. Generalized phrases such as “rates hit their highest level” can conceal important differences.
Relevant data and explanations are available from the U.S. Treasury and Federal Reserve. Those are appropriate baselines for an article readers may use to understand mortgages, bonds and savings decisions.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Long-term Treasury yields are the price signal linking government borrowing, mortgages, growth-stock valuations and the return available on safer assets. Reuters has highlighted an unusual 2026 divergence: shares near highs while longer-term bond yields have climbed. A bond yield is not the same as the Federal Reserve policy rate, and a large move in either can affect people differently depending on whether they borrow, save or invest. Sources: Reuters bond market analysis and Reuters market breadth.
The important context competitors can overlook
Bond prices generally fall when market yields rise. That inverse relationship explains why holders of long-duration bond funds can suffer losses even as the yields offered to new buyers become more attractive. Mortgage rates also reflect lending spreads, credit risk and other factors, so a single Treasury number cannot predict a specific home-loan offer. Companies with distant expected cash flows may be particularly sensitive to higher discount rates. For primary-source checks and current reporting, see Reuters bond market analysis and Investor.gov. The key distinction is translate bond math into household decisions.
Long-term Treasury yields connect bond markets to household borrowing and asset values. Higher yields can benefit new savers while hurting some borrowers and existing bondholders. Research cutoff: October 12, 2026; confirm developing facts before publication.
A practical way to use this information
Compare yields at consistent maturities rather than mixing two-year and ten-year readings. A homebuyer should assess monthly payment affordability at an actual lender quote. A saver choosing between a short-term bill and a long-term fund should consider liquidity needs and interest-rate risk. For an investor, the useful question is what rate assumptions are embedded in a company valuation, not whether “6%” makes a dramatic headline.
A simple rate-shock example
Imagine an existing long-duration bond fund whose duration is eight years. A simplified duration approximation suggests a one-percentage-point increase in yield could mean about an 8% price decline, before convexity, income and other effects. This is illustrative, not a forecast for a named fund. A short-term Treasury instrument with far lower duration usually reacts less to the same yield shock.
That distinction makes a practical difference for readers considering an emergency fund versus retirement money they can invest for a decade. The current market narrative described by Reuters should prompt a discussion of time horizon, not a blanket instruction to abandon bonds.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Are higher Treasury yields always bad?
No. New fixed-income savers may earn more, while existing long-duration bond prices can decline.
Does the Fed set the ten-year Treasury yield?
No. It influences conditions, but market expectations and term premiums also matter.
Why the ten-year yield influences everyday borrowing
The 10-year U.S. Treasury yield is an important benchmark for longer-term financing because it reflects the return investors require to hold government debt with that maturity. Mortgage rates do not equal the 10-year yield, but lenders consider Treasury markets, mortgage-backed securities, credit risk, servicing costs and competition when setting offers. If investors demand a higher return across long-term bonds, mortgage borrowing can become more expensive even without an immediate increase in the Federal Reserve’s short-term policy rate.
Suppose a buyer finances $300,000 over 30 years with a fixed-rate mortgage. At an illustrative 6% annual interest rate, principal and interest are roughly $1,799 per month; at 7%, they are roughly $1,996. The difference of about $197 per month excludes taxes, insurance, fees and other ownership costs. It demonstrates why a change in borrowing conditions can outweigh a modest change in a home’s asking price. Real quotes depend on the borrower’s circumstances and market conditions, not merely the Treasury yield reported in a news article.
Why bond prices and bond yields move in opposite directions
A conventional fixed-coupon bond promises specified payments. When newly issued securities offer higher yields, an existing bond with a lower coupon generally must trade at a lower price to attract buyers. The opposite happens when market yields fall. Duration measures a bond’s sensitivity to interest-rate changes. As an approximate illustration, a portfolio with an effective duration of seven years could lose about 7% in price if relevant yields rise by one percentage point, before other effects. The relationship is approximate and can vary with convexity, changing spreads and portfolio holdings.
For savers, a higher yield can be welcome if they are buying newly issued securities and can hold them under suitable circumstances. For owners of existing long-duration bonds, the same move can produce mark-to-market losses. Investors seeking near-term stability should understand the distinction between a bond’s redemption terms and the market price they might receive if they must sell before maturity. Credit risk also differs between Treasury securities and corporate or municipal bonds.
The yield curve tells a story, but not one prediction
The yield curve plots interest rates across maturities. Its shape can reflect expectations for growth, inflation, monetary policy and compensation for holding longer bonds. An inverted curve has often been studied as a recession signal, yet neither inversion nor steepening guarantees a specific economic outcome. A steepening curve may arise because investors expect stronger future activity, higher inflation or greater long-term borrowing supply. The underlying cause matters more than the shape alone.
Distinguish nominal yields from real yields after expected inflation. If a nominal Treasury yield rises because inflation expectations rise, the investor’s purchasing-power return may not improve nearly as much as the headline suggests. Treasury Inflation-Protected Securities provide another reference point, though their market prices and practical suitability also require care. Useful analysis compares inflation expectations, real yields and nominal yields rather than describing all higher rates as a sign of healthy growth.
A decision framework for households
Borrowers should compare multiple complete loan offers, including interest rate, annual percentage rate, closing costs and applicable points. A lower headline rate with very large upfront fees may not be cheaper for someone planning to move or refinance. Depositors should distinguish variable savings-account APYs from yields locked by certain fixed-term products. Bond-fund investors should review duration, credit quality, expenses and possible withdrawals. Stock investors should consider how higher discount rates affect the value assigned to future profits, particularly where profits are expected many years ahead.
No single financial product becomes universally best because yields reach a round number. A retiree seeking predictable cash flow, a first-time homebuyer and a technology-company investor face different tradeoffs. Their financial decisions are better guided by time horizon, liquidity and risk tolerance than by a prediction of where the yield will be next week.
The key variables to monitor
For a coherent market story, compare the 2-year and 10-year Treasury yields, current Fed communications, the latest inflation data and changes in bond-market liquidity. Track the time at which each observation was made. Also distinguish a policy announcement from a market-implied forecast; futures pricing can change significantly with new information. Where a report cites a historic high, specify the exact maturity and comparison period. Generalized phrases such as “rates hit their highest level” can conceal important differences.
Relevant data and explanations are available from the U.S. Treasury and Federal Reserve. Those are appropriate baselines for an article readers may use to understand mortgages, bonds and savings decisions.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
It is tempting to talk about “interest rates” as though there is one number moving the entire U.S. economy. In reality, the short-term policy rate set by the Federal Reserve and the market yield on a 10-year Treasury note can tell different stories. The first is a direct monetary-policy instrument. The second embeds investor expectations for future short-term rates, inflation, bond supply, economic uncertainty and compensation for holding long-duration debt.
In September, the Fed raised its target for the federal funds rate by a quarter percentage point to 3.75%–4.00%. That is a significant factual anchor for the October debate: the central bank was not simply holding policy unchanged. The official statement described resilient domestic activity and inflation that remained elevated. Federal Reserve September 16 statement.
On October 9, reporting placed the 10-year Treasury yield near 5.24% after a volatile week. For readers, the gap between these rates is more informative than either number alone. Associated Press market close.
Why a 10-year yield can exceed the policy rate
A bond yield reflects the price investors demand for a stream of future cash flows. When the price of an existing bond falls, its yield generally rises. Long-term yields may remain high even if investors think the Fed could eventually reduce short-term rates, because long-term inflation uncertainty, federal debt supply or term premiums may still justify additional compensation.
The opposite also happens. A central bank can raise its short-term rate while long-dated yields decline if bond investors believe tighter policy will bring inflation under control or weaken future growth. Therefore “the Fed hiked so all Treasury yields must rise” is an inaccurate shortcut. Market analysts need a time series and an explanation of which component changed.
What the Fed’s official data can—and cannot—say
The Federal Reserve publishes daily selected interest-rate data through its H.15 release. During the October 8 session, the listed 10-year constant-maturity Treasury rate was 5.22%; the later Friday market closing figures cited in news coverage were slightly different, reflecting observation timing and methodology. Federal Reserve H.15.
These values should not be presented as interchangeable real-time quotes. A daily Treasury constant-maturity series, an intraday cash-bond trade and a news-service closing yield can differ. High-quality financial reporting labels the instrument, source and timestamp. A difference of a few basis points can be normal even when all figures are independently correct.
The Fed also publishes economic projections and participant expectations. The September summary included elevated inflation projections, but these are not commitments by the committee or a binding timetable. Federal Reserve September economic projections.
Where SGOV fits into the story
The iShares 0–3 Month Treasury Bond ETF (SGOV) holds a portfolio of very short-dated U.S. Treasury securities. It is often discussed as an alternative to leaving uninvested money in a brokerage account because it seeks to earn short-term Treasury income with limited interest-rate sensitivity. The fund does not behave like a long-duration Treasury ETF, whose price can swing substantially when longer yields move.
As of the October 5 information visible on the issuer’s product page, SGOV displayed a 3.71% 30-day SEC yield and 0.09% expense ratio. These are dated metrics, not a promise of the rate a future investor will receive. Its income distribution changes with short-term market conditions, and the ETF can trade at a small premium or discount to net asset value. iShares SGOV facts.
Low duration is not the same as zero risk
Short-dated Treasury securities generally expose investors to far less interest-rate sensitivity than 10- or 30-year bonds, but several risks remain. ETF shares change price, market spreads exist, distributions fluctuate and inflation can erode the purchasing power of returns. A fund also differs legally from a bank deposit. Investors should not describe an ETF as FDIC-insured cash or assume the absence of a meaningful mark-to-market loss under every conceivable market condition.
Currency matters for international readers as well. A Pakistan-based investor considering a U.S. dollar Treasury product faces exchange-rate movements in addition to the securities’ dollar returns. Taxes, account access, fund structure and local regulation can also alter the practical outcome. A quoted U.S. dollar yield is not equivalent to a guaranteed local-currency gain.
Why different Treasury ETFs can move in opposite directions
Compare short Treasury bills with bonds maturing in 10 or more years. When yields rise, the longer bond’s existing fixed payments become less attractive, and its market price generally declines more because its cash flows are further in the future. This sensitivity is measured by duration, a useful—but approximate—way to compare rate risk.
A fund holding nearly maturing bills repeatedly reinvests at new yields, so changes in short rates can affect future income relatively quickly. A long Treasury fund can experience substantial price moves before the income change becomes visible. This is why an investor discussing “bond yields” should specify maturity and exposure rather than treating all fixed-income products as interchangeable.
The 2026 inflation question behind higher yields
Inflation changes the value of fixed payments in the future. Investors demand compensation when they think price growth will remain elevated or volatile. Energy shocks can reinforce this concern because higher diesel, shipping and manufacturing costs may work through supply chains. Yet not every energy-price move becomes a lasting increase in core inflation; monetary policy depends on broader evidence and expectations.
A September Fed projection showed its participants anticipating inflation remaining above target in the near term. Federal Reserve projections. Readers should not interpret that as an assurance of more rate increases. The future policy path depends on economic developments and FOMC decisions. Market-implied odds, if used, require a verified source and a timestamp.
Why stock investors care about the yield curve
When safer government securities offer competitive yields, investors may require greater potential returns to justify risky assets. Higher discount rates also reduce the present value of distant projected corporate profits. Those effects can be especially relevant for high-growth businesses whose market valuations depend on results many years away. Companies that refinance debt frequently can also feel direct interest expense pressure.
The relationship is not perfectly mechanical. Stocks may rise alongside Treasury yields when both are reacting to stronger expected growth. A central bank may tighten because corporate activity is resilient rather than because the economy is on the verge of recession. To interpret the market, ask whether the yield move reflects optimism about growth, inflation anxiety, government borrowing or a genuine change in policy expectations.
What to monitor in the coming weeks
Watch the next inflation reports, FOMC communications, Treasury auctions, 2-year and 10-year yields, investment-grade credit spreads and market pricing of future policy moves. Pair those signals with earnings releases, business investment and labor-market data. One factor can offset another: stronger earnings may cushion stocks against higher yields, while slowing sales and rising borrowing costs together can create more serious stress.
Readers should also check short-term fund yields directly with issuers because SGOV’s distribution profile can change without the fund’s ticker changing. Avoid stale “best cash yield” headlines. A product’s risk, liquidity, expenses and tax characteristics matter as much as a single yield snapshot.
The central takeaway
The Fed’s September hike and the elevated 10-year yield show that the cost of money remains a defining market issue in October 2026. SGOV illustrates why short-term Treasury products attract attention when yields are meaningful, but the fund cannot reveal a guaranteed future Fed decision. The sound approach is to distinguish policy rates, market yields and investment-product mechanics—then update each using its own official data source.
Frequently asked questions
What is the Fed’s target range in October 2026?
Following the September 16 decision, the target range was 3.75%–4.00% as of this article’s reporting cutoff.
Is the 10-year Treasury yield the Fed rate?
No. The 10-year yield is determined in bond markets and reflects several expectations beyond current policy.
Does SGOV have a fixed guaranteed yield?
No. Its published 30-day SEC yield is a dated standardized measure, not a guarantee of future distributions.
Why do long-term Treasury bonds fall when yields rise?
Existing fixed coupons become less attractive relative to newer higher-yielding securities, so market prices typically decline.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
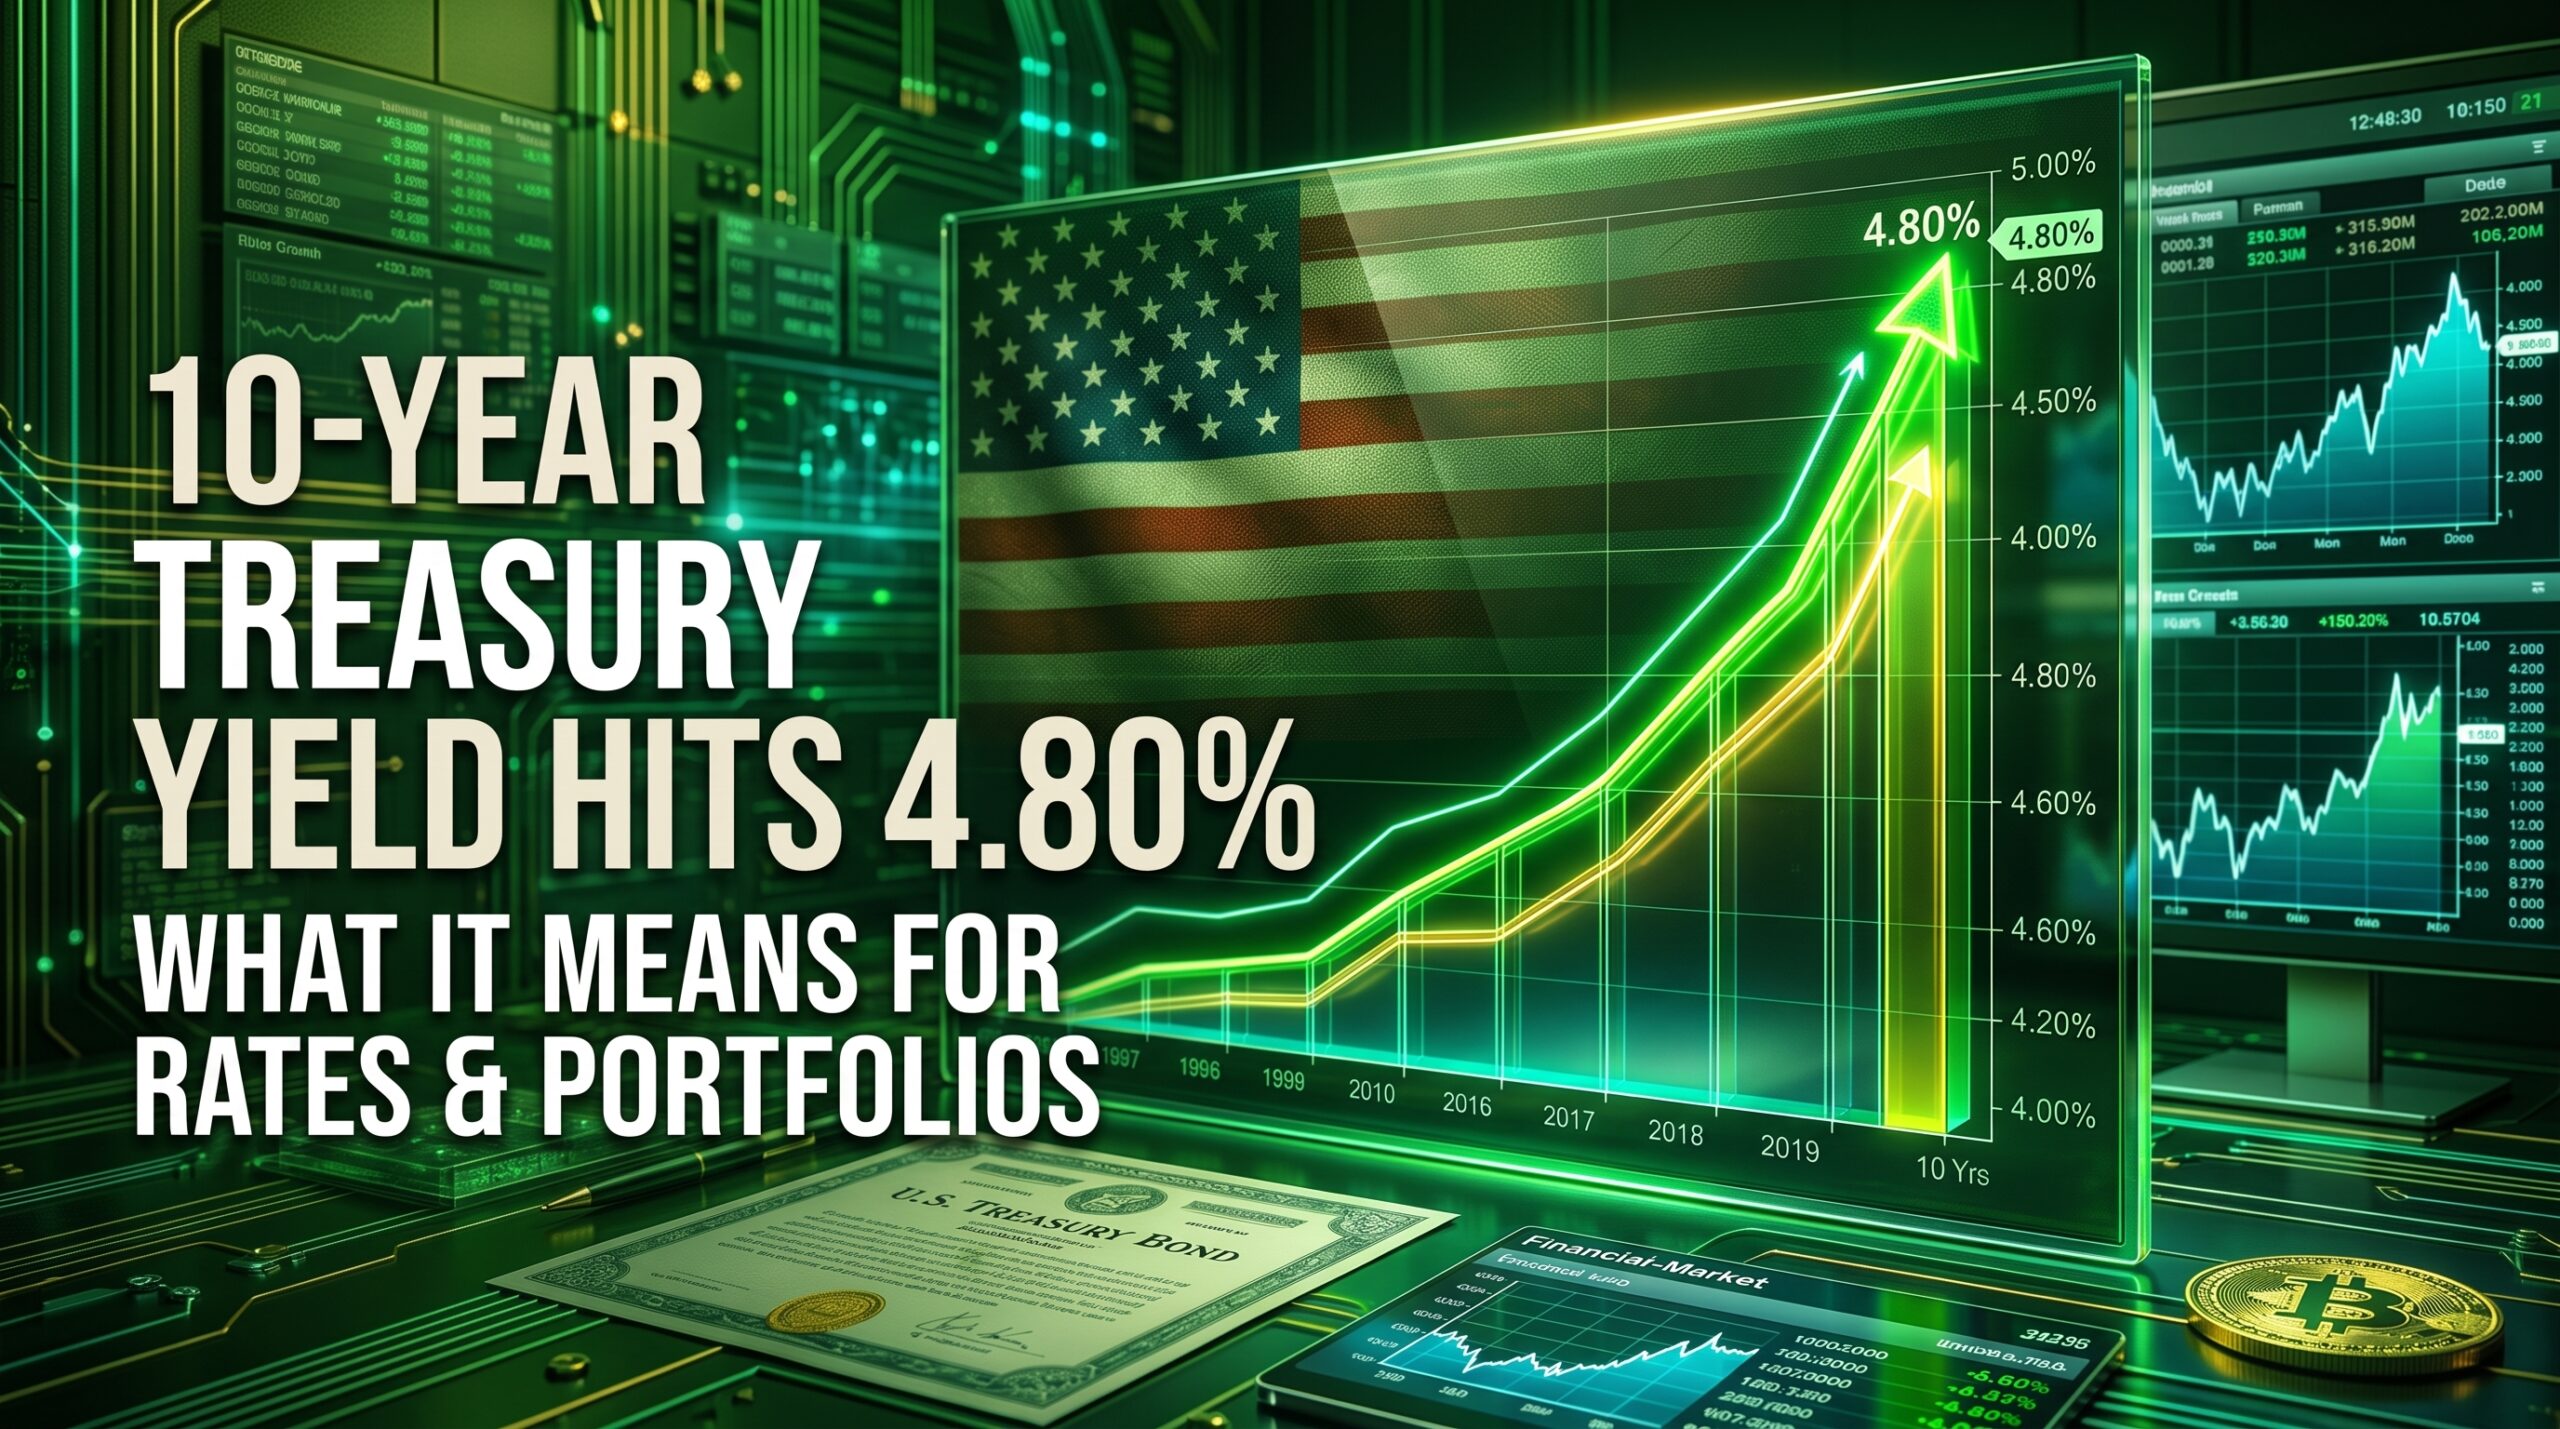
The 10-year U.S. Treasury yield climbed for a fifth consecutive session to 4.80% on September 1, 2026 — its highest level since January 2025 — as rising oil prices and hawkish Federal Reserve commentary pushed market-implied odds of a rate hike this month to roughly 68%, up sharply from around 40% a week earlier. The move has flattened parts of the yield curve and is already reshaping equity valuation math, mortgage rates, and fixed-income allocation decisions heading into the fall.
The Treasury Yield Curve: September 1, 2026 Snapshot
| Maturity | Yield (Sept 1, 2026) | 12-Month Average | Change vs. 12-Month Avg |
|---|---|---|---|
| 1-Year | 4.15% | — | — |
| 2-Year | 4.39% (day high 4.80% intraday on related note) | 3.77% | +62 bps |
| 3-Year | 4.40% | 3.80% | +60 bps |
| 5-Year | 4.49%–4.57% | 3.92% | +57–65 bps |
| 7-Year | 4.62% | 4.10% | +52 bps |
| 10-Year | 4.75%–4.80% | 4.30% | +45–50 bps |
| 30-Year | 5.28% | — | — |
| Related Metric | Value |
|---|---|
| Fed rate hike odds this month (market-implied) | ~68%, up from ~40% the prior week |
| 10-year yield 1-month change | +11 to +12 basis points |
| 10-year yield 12-month change | +52 to +53 basis points |
| Last time 10-year yield was this high | January 2025 |
| Key driver | Rising oil prices amid renewed geopolitical tensions; hawkish Fed commentary at Jackson Hole |
Sources: TradingEconomics, MacroMicro, StreetStats, and FRED (Federal Reserve Bank of St. Louis) Treasury yield data, September 1, 2026.
Deep Dive: What’s Actually Driving the Move, and Why It’s Different From Prior 2026 Yield Spikes
This Is an Inflation-Expectations Story, Not a Growth Story
It’s important to separate two very different reasons long-term yields can rise: strong growth expectations (generally a “good” reason, associated with rising real yields) versus rising inflation expectations (a more concerning reason, associated with rising breakeven inflation rates embedded in the yield). The current move fits the second category. Fed Chair Warsh’s Jackson Hole remarks reiterated a commitment to bringing inflation down, and Fed Governor Barr followed with commentary that the central bank should be prepared to raise rates if inflation fails to subside — language markets read as explicitly hawkish, not as confidence-inspired optimism about growth.
The proximate trigger has been the energy market. Renewed geopolitical tensions have pushed oil prices higher, and because energy costs feed directly and quickly into headline inflation readings, that pressure has meaningfully firmed up market expectations that the Fed’s next move is a hike rather than a hold or a cut — a reversal from where sentiment stood as recently as early August, when a weak July payrolls report had markets contemplating cuts.
The Curve Shape Tells Its Own Story
With the 2-year yield around 4.39%, the 10-year around 4.75–4.80%, and the 30-year at 5.28%, the curve remains upward-sloping (not inverted) across every point measured here — a configuration that historically has not signaled imminent recession risk in the way an inverted curve does. That said, the magnitude of the move across the curve in a compressed window (roughly 50+ basis points on the 10-year over the trailing year, with over 10 basis points in just the last month) is itself the signal worth tracking, independent of the curve’s shape.
Reading Through to Real-World Borrowing Costs
A 10-year Treasury yield near 4.80% has direct downstream effects that matter well beyond bond traders. Mortgage rates in the U.S. are priced primarily off the 10-year Treasury yield plus a spread, meaning a sustained move to this level typically translates into 30-year fixed mortgage rates that make refinancing activity and new home purchases meaningfully more expensive on a monthly-payment basis than they were when the 10-year sat closer to its 4.30% trailing 12-month average. Corporate borrowing costs — for both investment-grade and high-yield issuers, who price off Treasury benchmarks plus a credit spread — move in the same direction, raising the cost of capital for companies planning debt-financed expansion, buybacks, or refinancing of maturing debt.
The Manufacturing and Labor Backdrop Complicates the Picture
What makes this yield spike harder to dismiss as a temporary energy-driven blip is that it’s occurring against a backdrop of resilient — not weakening — underlying data on several fronts: job openings edged higher in July, layoffs fell, and manufacturing activity expanded for an eighth consecutive month through August. A central bank facing an inflation scare against a backdrop of a still-functioning labor market and expanding manufacturing sector has considerably more latitude to act hawkishly than one facing simultaneous inflation and growth concerns — which is precisely the combination that has pushed hike odds from 40% to 68% in a single week.
Historical Context: How Unusual Is 4.80%?
The 10-year yield’s climb to 4.80% marks its highest level since January 2025, meaning the current move represents a genuine multi-year high rather than a routine fluctuation within a familiar range. For perspective, the 10-year traded closer to 4.06–4.14% in September of the prior year (2025), meaning the current level represents an increase of roughly 65–75 basis points over that comparable period twelve months earlier — a meaningful repricing of the risk-free rate that underpins virtually every other asset valuation model in the market.
Actionable Takeaways for Fixed-Income and Portfolio Positioning
- Reassess duration exposure before assuming yields have peaked. Investors holding long-duration bond funds or individual long-maturity bonds should model further downside price risk if yields continue climbing toward or past 5.00%, rather than assuming the current level represents a ceiling.
- Consider laddering maturities rather than concentrating in a single tenor. A yield curve that remains upward-sloping but volatile rewards spreading fixed-income exposure across the 2-, 5-, and 10-year points to balance income against reinvestment and price risk.
- Watch oil prices and geopolitical headlines as the most immediate leading indicator. Given that energy-driven inflation expectations are the proximate driver of this move, a de-escalation in the geopolitical tensions currently pushing crude higher would likely be the fastest path to yields stabilizing or reversing.
- Revisit any rate-cut-dependent financial plans immediately. Anyone who delayed a mortgage refinance, a corporate debt refinancing, or a major purchase in anticipation of Fed cuts later in 2026 should reassess those plans against the new reality of meaningfully elevated hike odds.
- Track the FOMC meeting date directly. With market pricing near 68% odds of a hike, the meeting outcome itself — and, just as importantly, the Fed’s forward guidance and dot plot accompanying any decision — will be the next major catalyst for where yields head through the fourth quarter.
Frequently Asked Questions
Why is the 10-year Treasury yield rising in September 2026? The 10-year Treasury yield climbed to 4.80% — its highest since January 2025 — driven primarily by rising oil prices amid renewed geopolitical tensions, which have pushed up inflation expectations, combined with hawkish commentary from Federal Reserve officials at the Jackson Hole symposium suggesting rates may need to rise further.
Will the Federal Reserve raise interest rates in September 2026? Market-implied odds of a 25-basis-point rate hike at this month’s FOMC meeting stood at roughly 68% as of September 1, 2026, up sharply from around 40% the prior week, though this remains a probability derived from futures pricing rather than a confirmed outcome.
How does a rising 10-year Treasury yield affect mortgage rates? Mortgage rates are priced largely off the 10-year Treasury yield plus a lending spread, so a sustained climb to 4.80% typically pushes 30-year fixed mortgage rates higher in tandem, increasing monthly payment costs for new homebuyers and reducing the financial incentive to refinance existing loans.
What does an upward-sloping yield curve at these levels signal for the economy? With yields rising across the curve but remaining upward-sloping (2-year below 10-year below 30-year), the shape itself is not signaling the kind of recession risk historically associated with an inverted curve, though the pace and magnitude of the recent rise reflects a genuine inflation-expectations concern that bears separate monitoring from curve shape alone.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Treasury Yields and Inflation 2026: What Bond Moves Mean for Borrowers

Social Security COLA 2027 Is 3.6%: Payments, Examples and Dates

Ukraine’s Oil Strike Strategy: Can It Break Russia’s War Economy?

Power Grid Emergency Across 13 States? What the October 2026 PJM Order Actually Says

Oil Prices October 2026: Iran Conflict, Shipping and Inflation Risks

TSMC Stock in October 2026: AI Chip Demand, Earnings and Valuation Risks

Stock Market Crash 2026: What the Inflation and AI Selloff Means

Student Loans and the 2026 Midterms: SAVE Plan Deadlines and Borrower Choices

KOSPI Crash October 2026: What Korea’s Chip Selloff Reveals

CoreWeave Stock 2026: CRWV, AI Infrastructure Debt and the Selloff Explained

OP-ED:The AI Race Has No Single Winner — And Pakistan Must Choose Its Own Future

VA Disability Rates Increase 2027: The Confirmed 3.6% COLA Explained

US–China AI Export Controls in 2026: Chips, Testing Rules and Corporate Risk

World Trade in 2026: Tariffs, Supply Chains and the Cost of Fragmentation

World’s Largest Economies: Ranking the Top Global Powers

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Bitcoin Price Forecast 2026–2027: Will the 4-Year Cycle Hold?

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

Asian Stock Markets 2026: Japan, China, Pakistan & More

SpaceX IPO 2026: History’s Biggest Stock Debut?

SpaceX IPO: How Aerospace Is Reshaping Tech Startup News

Oil Prices 2026: Inside the Hormuz Crisis That Won’t End

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

IMF Reports 2026: What the Latest Data Means for the Global Economy

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Business Insurance: What Coverage You Actually Need and What It Costs in 2026
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025