
ASEAN
ASEAN+3 Enters 2026 From a Position of Strength — But Two Storms Are Building Offshore

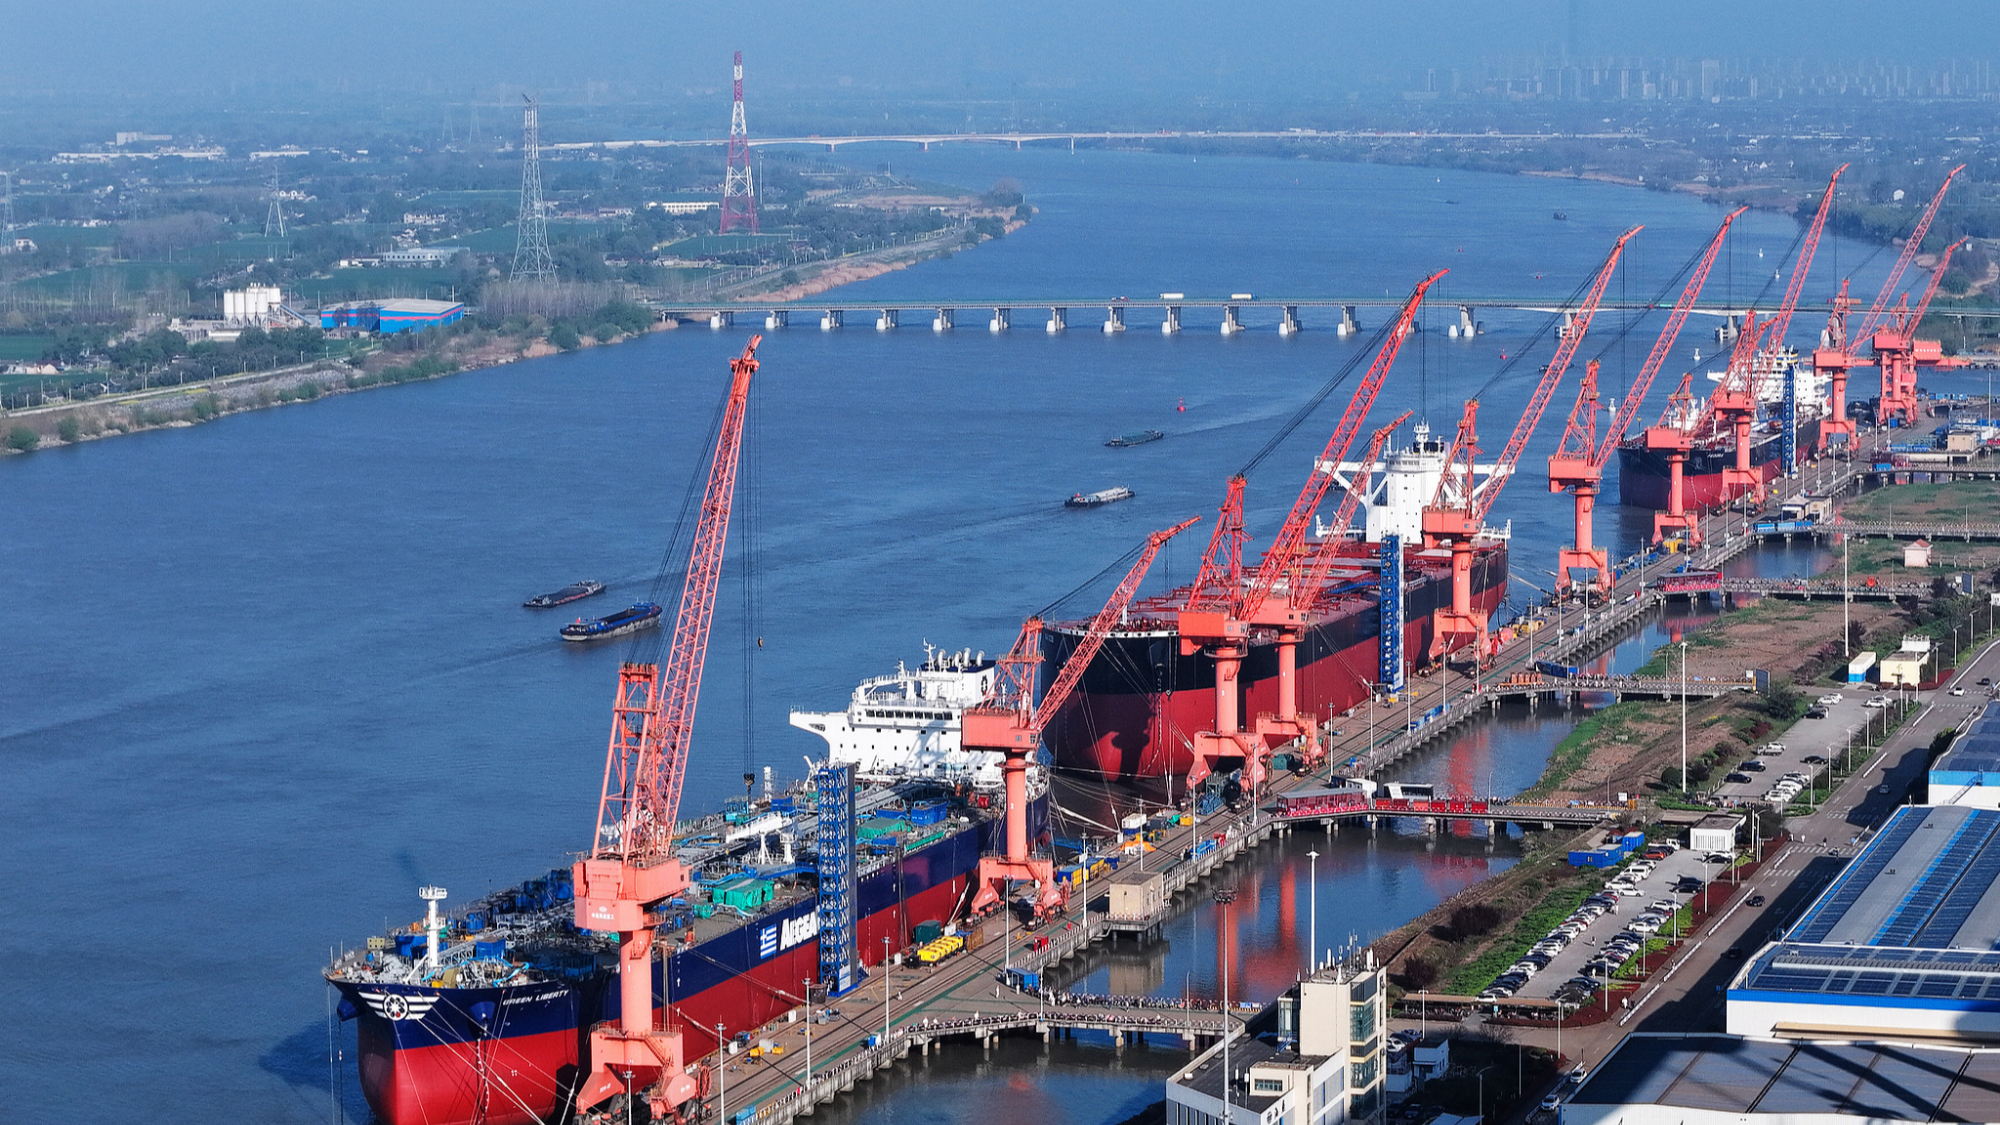
The ASEAN+3 region expanded 4.3% in 2025, outperforming expectations despite what regional economists describe as the most significant shift in global trade policy in decades, according to the AMRO ASEAN+3 Regional Economic Outlook 2026.
A Region Built on Firm Foundations
The ASEAN+3 Macroeconomic Research Office (AMRO) — whose membership spans the ten ASEAN states plus China, Hong Kong, Japan, and Korea — attributes the region’s resilience to firm domestic demand, robust export performance, sustained investment, and deepening intraregional trade linkages. The region enters 2026 with most economies retaining meaningful fiscal and monetary policy space, a buffer regional policymakers built deliberately following the shocks of the preceding decade.
Two Risks Now Dominate the Outlook
AMRO identifies the balance of risks as tilted firmly to the downside for the year ahead, driven by two distinct but interacting shocks. First, the Middle East conflict and the resulting disruption to energy supply through the Strait of Hormuz pose what AMRO calls a significant near-term threat to both regional growth and inflation. Second, shifting US trade policy continues to inject two-sided risk into technology demand and broader trade flows, with financial market volatility compounding the downside pressure from both channels simultaneously.
Semiconductors Anchor the Region’s Trade Position
Regional semiconductor exports remain a structural strength even amid the broader uncertainty. AMRO’s data tracks ASEAN-6 semiconductor exports — spanning Indonesia, Malaysia, the Philippines, Singapore, Thailand, and Vietnam — as a critical driver of regional trade resilience, reflecting the bloc’s entrenchment in global chip and electronics supply chains at a moment when demand for AI-related hardware remains exceptionally strong globally, per AMRO’s full 2026 report.
China’s Property Drag Still Ripples Outward
Even as China’s export engine benefits from AI-driven demand, AMRO notes that overall Chinese investment remained slightly softer in the period under review, with spending on clean energy and advanced manufacturing only partly offsetting a prolonged property-sector adjustment. Given the depth of intraregional trade linkages AMRO’s own research documents, continued softness in Chinese domestic investment carries spillover implications for supply chains and demand across the wider ASEAN+3 bloc, even as China’s headline export growth remains robust.
The Regional Growth Picture, Country by Country
Within the bloc, growth trajectories are diverging. Indonesia, Singapore, and Vietnam are leading regional growth momentum into 2026, while Malaysia and Thailand continue to expand at a steadier, more moderate pace, and the Philippines lags due to domestic structural challenges, according to McKinsey’s Southeast Asia quarterly economic review. The Asia House Annual Outlook separately forecasts overall Asian growth easing to 3.8% from 4.1% according to WTO estimates, reflecting softer global demand, a modest China slowdown, and the fading effect of earlier supply-chain frontloading, though the region is still expected to outperform the global growth average, per Asia House’s 2026 outlook.
Preserving Policy Flexibility Is the Central Challenge
AMRO frames the region’s central policy challenge for 2026 not as responding to any single shock, but as preserving the flexibility to respond to whichever shock materializes first — whether a further escalation in Middle East energy disruption, a sharper-than-expected US tariff or technology-policy shift, or a deeper Chinese property-sector adjustment than currently modeled. For businesses and investors across Singapore, Malaysia, Indonesia, and the wider bloc, that framing suggests 2026 will reward economies and companies that maintain optionality rather than committing early to any single scenario for how the region’s twin external shocks ultimately resolve.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Markets & Finance
Beyond Singapore’s Borders: How Squeezed SMEs Can Unlock High-Yield Growth Across ASEAN
Faced with escalating domestic overhead, acute labor bottlenecks, and an ultra-saturated local market, Singapore’s small and medium-sized enterprises (SMEs) are approaching an operational inflection point. While the city-state remains an unrivaled global financial hub, domestic cost structures are increasingly compressing profit margins for mid-market businesses. Expanding across Southeast Asia is no longer merely a growth option—it has become a necessity for enterprise resilience and long-term value creation.
The Singapore Pressure Cooker: Why Domestic Growth Has Hit a Ceiling
Singapore SMEs contend with a uniquely challenging operating environment. According to economic assessments from the Monetary Authority of Singapore, structural cost pressures—spanning commercial real estate rents, utility hikes, and rising labor expenses—continue to outpace revenue growth across several non-oil domestic sectors.
Key factors squeezing Singapore SMEs include:
- Manpower Bottlenecks: Tightening foreign worker quotas and elevated salary thresholds under the Strategic Skills Framework have made local talent recruitment highly competitive and expensive.
- Property and Rental Overhead: Commercial and industrial space costs in prime logistics and office hubs remain among the highest in Asia, squeezing operational margins for retail, manufacturing, and services alike.
- Market Saturation: With a population of roughly 6 million, the domestic addressable market limits scale, making revenue compounding difficult without international customer acquisition.
To achieve sustainable multi-year growth, forward-looking business leaders are restructuring their footprint—using Singapore as an intellectual property (IP), treasury, and management headquarters while scaling operations into neighbor economies.
The ASEAN Dividend: Demographics, Digitalization, and Supply Chain Realignment
Southeast Asia represents a vibrant economic bloc of over 680 million consumers, characterized by rapid urbanization, an expanding middle class, and high mobile technology penetration. Research published by the Asian Development Bank highlights that regional GDP growth across ASEAN continues to outpace global averages, fueled by strong domestic demand and cross-border trade integration.
                  +-------------------------------------------------------+
                  |            Singapore Corporate Head Office            |
                  |     (IP, Treasury, Governance, R&D, Tech Core)        |
                  +-------------------------------------------------------+
                                              |
      +-----------------------+---------------+---------------+-----------------------+
      |                       |                               |                       |
      v                       v                               v                       v
+-----------+           +-----------+                   +-----------+           +-----------+
|  Vietnam  |           | Indonesia |                   | Malaysia  |           | Thailand  |
| (Mfg/Tech)|           | (Consumer)|                   | (Logistics|           | (Industrial|
|           |           |           |                   | & Services|           | & Auto Ops|
+-----------+           +-----------+                   +-----------+           +-----------+
Three macro drivers make ASEAN the primary expansion target for Singaporean firms:
- Supply Chain Diversification (“China+1”): Global multinationals and regional enterprises are diversifying manufacturing hubs toward Southeast Asia to enhance supply chain resilience, boosting local business ecosystems.
- Accelerated Digital Transformation: Digital economy report insights from McKinsey & Company reveal that regional cross-border e-commerce, fintech adoption, and digital services are projected to triple in market value by 2030.
- Regional Trade Integration: Agreements such as the Regional Comprehensive Economic Partnership (RCEP) and ASEAN Free Trade Area (AFTA) reduce trade barriers, lower tariffs, and simplify cross-border logistics.
Comparative Expansion Matrix for Target ASEAN Markets
Selecting the right expansion destination depends on sector alignment, talent requirements, and cost structures. The following framework maps core opportunities for Singapore SMEs across major ASEAN growth markets:
| Expansion Market | Primary Growth Drivers | Strategic Cost Advantage | High-Potential Sectors | Market Entry Complexity |
| Vietnam | Rapid industrialization, tech talent pool, strong export orientation | Low manufacturing and engineering labor costs | Precision engineering, electronics, software development | Moderate (Requires navigating local regulatory channels) |
| Indonesia | Massive domestic market (275M+ population), rising consumer class | High consumer volume potential, lower operational costs | B2C e-commerce, consumer tech, logistics, agritech | Moderate to High (Complex licensing & local partner rules) |
| Malaysia | Proximity to Singapore, shared talent language, integrated supply chains | Lower land and talent costs with minimal cultural friction | Cross-border logistics, professional services, food manufacturing | Low (High synergy with SG business models) |
| Thailand | Strong industrial base, advanced infrastructure, EV ecosystem | Cost-effective industrial facilities and skilled labor | Advanced manufacturing, automotive supply, healthcare, tourism tech | Moderate (Language barriers require local executive talent) |
A 4-Step Actionable Roadmap for Overseas Regionalization
Expanding across borders requires structured execution to avoid capital misallocation. Enterprise leaders can adopt this four-phase framework to mitigate market entry risks:
- Leverage Institutional Support and Co-FundingBefore committing capital, utilize government-backed regionalization initiatives. Programs administered by Enterprise Singapore—such as the Market Readiness Assistance (MRA) grant and the Enterprise Development Grant (EDG)—provide co-funding for market studies, legal set-up, and overseas business matching.
- Adopt a “Hub-and-Spoke” Operational ModelMaintain high-value activities (financing, IP management, advanced R&D, regional leadership) in Singapore to preserve institutional trust and regulatory clarity. Establish operational “spokes” in target ASEAN countries to handle high-volume manufacturing, customer support, and local marketing.
- Form Local Joint Ventures and Strategic AlliancesDirect market entry can carry regulatory hurdles and cultural blind spots. Partnering with established in-market distributors or joint-venture partners accelerates distribution access and ensures regulatory compliance.
- Capitalize on Cross-Border Digital InteroperabilityWith initiatives backed by the ASEAN Secretariat to build unified cross-border payment rails (such as real-time QR payment linkages between Singapore, Malaysia, Thailand, and Indonesia), businesses can handle cross-border payments with reduced friction and lower FX transaction costs.
Mitigating Risk: Structural Protocols for Cross-Border Success
While the growth prospects are significant, cross-border expansion presents operational challenges. SME leadership must address key risk categories:
- Regulatory and Foreign Ownership Restrictions: Certain jurisdictions enforce foreign ownership caps in specific sectors. Engaging qualified legal counsel early ensures proper corporate structuring and compliance with local equity mandates.
- Foreign Exchange Exposure: Currency volatility across emerging ASEAN markets can erode operating profits. Implementing formal hedging policies through treasury banking partners mitigates FX exposure.
- Taxation Structuring: Companies must optimize transfer pricing and leverage bilateral Avoidance of Double Taxation Agreements (DTAs) signed between Singapore and ASEAN member states to avoid overlapping tax obligations.
SMEs that treat regional expansion as a strategic imperative rather than a reactive survival tactic can leverage Singapore’s regional anchor status to capture long-term market share across Southeast Asia.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
Singapore’s non-oil domestic exports rose 20.7% year-on-year in June 2026, driven by a 115.4% surge in integrated circuit shipments tied to AI demand, even as a separate and less-covered trade story unfolds next door: Malaysia-Indonesia bilateral trade is projected to grow 10% to US$29.3 billion in 2026, powered by expanding halal-sector cooperation.
The story most coverage is missing
Regional business press has extensively covered Singapore’s semiconductor export boom. What’s had far less coverage is the parallel, non-tech growth engine developing in the halal trade corridor between Malaysia and Indonesia — a structural, policy-driven trade relationship that is scaling steadily even as the AI trade headlines dominate attention.
Singapore: the AI supply chain’s export barometer
Singapore’s June non-oil domestic exports climbed 20.7% year-on-year, with integrated circuit exports jumping 115.4% and disk media products and personal computers rising 170.9% and 95.8% respectively — a direct read on how deeply the AI infrastructure buildout is flowing through the city-state’s electronics trade (VietnamPlus/VNA). Non-electronic exports told a different story, falling 2.9% in June after a 17.7% rise in May, mainly on weaker shipments of non-monetary gold, petrochemicals and food preparations — evidence the export strength is narrowly concentrated in the AI-linked segment rather than broad-based.
Singapore’s economic gravitational pull on its neighbours is intensifying too: a joint study by the Singapore Business Federation, Restaurant Association of Singapore and Singapore Retailers Association found Singaporean consumers are projected to spend an additional S$1.05 billion (roughly US$810 million) annually in Johor Bahru, just across the Malaysian border — a cross-border consumption pattern that is becoming a meaningful line item in regional retail planning (VietnamPlus/VNA).
The halal corridor: a steadier, policy-built growth story
While AI exports grab headlines, Malaysia’s bilateral trade with Indonesia is forecast to grow 10% to US$29.3 billion in 2026, according to Malaysia’s Chargé d’Affaires in Jakarta, Farzamie Sarkawi — up from US$26.61 billion in 2025, itself a 5.3% increase on the year before (BusinessToday Malaysia).
The driver is structural rather than cyclical: a halal Memorandum of Cooperation signed by the two countries in 2023 established mutual recognition of halal certification, easing product movement and market access across sectors. Sarkawi described the arrangement as delivering “positive progress” through knowledge exchange, training and improved market access for businesses in both countries (BusinessToday Malaysia). The ambition extends beyond the bilateral relationship: intra-D-8 trade — spanning the eight-nation Developing 8 bloc of Muslim-majority economies — currently runs between US$150 billion and US$160 billion annually, with a stated target of US$500 billion by 2030.
The macro backdrop: a region growing, unevenly
The Asian Development Bank’s July 2026 outlook shows Indonesia’s growth forecast holding steady at 5.2% for both 2026 and 2027, while Malaysia’s outlook is unchanged at 4.6% for 2026 and 4.5% for 2027 (ADB). Regional growth leadership, per McKinsey’s Q1 2026 review, sits with Indonesia, Singapore and Vietnam, while the Philippines lagged as domestic challenges weighed on activity (McKinsey).
Indonesia’s investment story has particular momentum: foreign direct investment grew for a second consecutive quarter, rising 8.1% to 249.9 trillion rupiah (roughly US$14.5 billion) in the first quarter of 2026, with Singapore remaining Indonesia’s largest single foreign investor at US$4.6 billion, ahead of China, Japan, Hong Kong and the United States (McKinsey). Realised investment for full-year 2025 reached a record Rp1,931.2 trillion (about US$120.7 billion), exceeding the government’s own target, driven by downstream industrial projects outside Java (BERNAMA).
Indonesia’s central bank has flagged currency management as an active watch item, signalling readiness to step up both onshore and offshore FX intervention to curb rupiah weakness and keep inflation within its 2026-2027 target band (McKinsey). Foreign investment in Indonesian government bonds has nonetheless rebounded, with net inflows of 17.7 trillion rupiah following outflows in the first quarter, alongside cumulative foreign holdings of 174 trillion rupiah in Bank Indonesia Rupiah Securities (BERNAMA).
Institutional context: Singapore’s coming ASEAN chairmanship
Adding a governance dimension to the economic picture, Singapore is set to take over the ASEAN chairmanship from the Philippines in 2027, with Prime Minister Lawrence Wong pledging a smooth transition — a leadership handover that will shape how the bloc coordinates trade and investment policy, including the halal-corridor and semiconductor-trade dynamics described above, through the second half of the decade (BERNAMA).
The bottom line
Southeast Asia’s 2026 growth story is not a single narrative but two distinct, converging tracks: a high-velocity, AI-linked export boom concentrated in Singapore’s electronics trade, and a steadier, policy-engineered halal-sector trade corridor between Malaysia and Indonesia that is quietly scaling toward a $500 billion bloc-wide target by 2030. Investors and policymakers tracking only the semiconductor headlines risk missing the second, structurally more durable growth engine sitting right alongside it.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
While global headlines chase the AI infrastructure story in the US and China, one of the most interesting AI capital-deployment stories on the planet is unfolding almost unnoticed across a 4-kilometre stretch of water between Singapore and Malaysia — and it’s worth understanding for anyone tracking where the next wave of Southeast Asian growth is actually landing.
What the JS-SEZ Actually Is
The Johor-Singapore Special Economic Zone, formally established on January 7, 2025, covers roughly 3,588 square kilometres across southern Johor state. It spans nine flagship areas and targets investment across eleven sectors, including manufacturing, logistics, financial services, the digital economy, tourism, education, healthcare, and the green economy (Forest City SFZ / Manila Times).
The core idea is simple, even if the execution is complex: Singapore contributes financial infrastructure, regulatory credibility, and capital markets access; Johor contributes roughly four times Singapore’s land area and a median monthly wage around one-seventh of Singapore’s, creating room for industrial-scale development that Singapore’s tiny footprint simply can’t accommodate (Trowers & Hamlins).
The Numbers That Show This Isn’t Just Another SEZ Announcement
Skeptics have plenty of reason to be cautious about grand cross-border economic zone announcements — Southeast Asia has seen plenty of ambitious blueprints fizzle. But the JS-SEZ’s investment figures suggest real capital is already moving, not just political goodwill.
The zone attracted $19 billion in approved investments in 2025, with more than 57% of cumulative approved projects already entering the implementation stage — not just paper commitments (VietnamPlus). That momentum continued into 2026, with $1.3 billion in new approved investments in the first quarter alone, and the Invest Malaysia Facilitation Centre Johor (IMFC-J) fielding 285 investment enquiries worth a combined $18.5 billion in just the first five months of the year.
Separately, Singapore’s Ministry of Trade and Industry confirmed Singapore-based companies have committed more than S$5.5 billion into Johor since the memorandum of understanding was signed (Forest City SFZ). On the Malaysian side, domestic and foreign investment into the region more than doubled from MYR 48.5 billion (roughly US$11.9 billion) in 2024 to MYR 110 billion (about US$27 billion) in 2025, with 70% of that total year’s investment specifically tied to JS-SEZ projects (Lundgreen’s Investor Insights).
The Real Story: Johor Is Becoming Singapore’s Data Centre Overflow Valve
Here’s the angle competitors are missing entirely: this isn’t primarily a manufacturing or logistics story. It’s a data centre story, and it’s happening precisely because Singapore has run out of room and water to support the AI infrastructure boom domestically.
Roughly 60% of Southeast Asia’s data centres are already concentrated in Johor (Lundgreen’s Investor Insights). That’s not a coincidence — Singapore enforces strict limits on new data centre expansion domestically, largely due to power and water constraints, pushing hyperscale demand across the border. Global players including Microsoft, ByteDance, and AirTrunk have already invested in Johor’s data centre buildout, and Johor also benefits from proximity to Singapore’s extensive submarine cable network — around 30 international cables carrying a combined 44.8 terabits per second of capacity (Trowers & Hamlins).
The economics are striking at a granular level: based on Johor State Data Centre Development planning guidelines, every MYR 1 billion (roughly US$250 million) invested in a data centre creates 400 to 600 jobs and adds MYR 500 million (about US$126 million) to Malaysia’s GDP (Lundgreen’s Investor Insights). With data centres, manufacturing, and energy topping the list of investor enquiries by sector, and China, Singapore, and South Korea ranking as the top three source countries for investment interest (Invest Johor), the zone is quietly positioning itself as a geopolitically neutral alternative for AI infrastructure at a moment when US-China tensions make data centre siting decisions increasingly political.
The Infrastructure Piece Everyone’s Watching: The RTS Link
The physical backbone tying this all together is the Johor Bahru-Singapore Rapid Transit System Link, a four-kilometre rail connection between Bukit Chagar and Woodlands North designed to carry up to 10,000 passengers per hour in each direction, cutting a commute that currently involves congested causeway traffic down to roughly five minutes (Forest City SFZ). It’s targeted to begin passenger service by the end of 2026 — a deadline that, if hit, would materially improve the shared-labour-market model underpinning the entire economic zone concept, where thousands of Malaysians already commute daily into Singapore.
What’s Genuinely Uncertain — and Why That Matters for Investors
This is where most boosterish coverage of the JS-SEZ falls short: it’s not risk-free, and the risks are structural rather than cosmetic.
No unified regulatory framework yet exists. The JS-SEZ falls under Malaysian jurisdiction, and substantive regimes — tax, labour law, compliance — remain entirely separate between the two countries. Current cross-border coordination focuses on facilitation rather than genuine legal integration, and the formal master plan and investment blueprint, originally targeted for the first quarter of 2026, has already been delayed (Trowers & Hamlins).
Implementation friction is real, not theoretical. Existing Singaporean businesses operating in Johor are reportedly receiving contrasting guidance from Malaysia’s federal and state governments on tax treatment — exactly the kind of bureaucratic inconsistency that can quietly erode investor confidence even as headline investment figures climb.
The minimum investment threshold favors large players over SMEs. Malaysia’s tax incentive package, administered through MIDA, requires a minimum capital investment of RM500 million (roughly US$126 million) to qualify — a bar high enough to exclude most small and mid-sized businesses from the zone’s most attractive incentives, concentrating benefits among multinationals and large regional players.
Water is the long-term constraint to watch. Data centres consume enormous volumes of water for cooling, and shifting that burden onto Johor — precisely because Singapore’s own water resources are limited — creates an environmental sustainability question that current green initiatives (stormwater reuse, greywater recycling, solar-powered facilities) are only beginning to address at scale.
What This Means for Businesses Weighing Entry
For companies evaluating the JS-SEZ as an expansion target, the practical playbook emerging from early movers suggests: treat Johor as a genuinely separate operating environment rather than “Singapore with cheaper rent,” budget for parallel legal review in both jurisdictions rather than assuming harmonized compliance, and prioritize sectors — data centres, advanced manufacturing, logistics — where the zone’s infrastructure investment is most mature, rather than betting on sectors still waiting on the delayed master plan for clarity.
The Bottom Line
The JS-SEZ has moved past the announcement-and-optimism phase that sinks most cross-border economic zones and into measurable capital deployment — $19 billion in approved 2025 investment with the majority already under implementation is a meaningful signal, not just a talking point. But the zone’s success now depends on execution details that don’t make for exciting headlines: harmonizing tax treatment, delivering the RTS Link on schedule, finalizing the long-delayed master plan, and managing the environmental trade-offs of becoming Southeast Asia’s default data centre overflow zone. Investors who track those unglamorous milestones will understand the JS-SEZ’s real trajectory long before the next round of splashy investment-forum press releases does.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

AI Investment Boom 2026–2027: Can Pakistan Capture the Upside?

Global Economy 2026–2027: What Slower Growth Means for Pakistan

Why Global Inflation Is Rising Again in 2026, and What It Means for Pakistan

Raast Pakistan 2026: Digital Payments, Fintech

Pakistan Real Estate Tax 2026: What Buyers, Sellers and Investors Must Check

SME Finance Pakistan 2026: Why Small Businesses Still Struggle for Credit

Pakistan IMF Programme 2026: Why Bailouts Keep Returning

Agri-Tech Pakistan 2026: Where Farming Innovation Could Actually Pay

Pakistan Tax Net: Why Agriculture, Retail and Property Are So Hard to Tax

KSE-100 Index 2026: Is Pakistan’s Stock-Market Recovery Sustainable?

Pakistan IT Exports 2026: What Would It Take to Reach $10 Billion?

Pakistan AI Policy 2025: Can It Raise Productivity and Create Jobs?

Pakistan Remittances 2026: How Overseas Workers Support the Economy

Can Pakistan Reach $34 Billion in Exports? The Real Barriers and Fastest Fixes

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

World’s Largest Economies: Ranking the Top Global Powers

Pakistan Economy 2026: Inside the SBP’s Balancing Act

Asian Stock Markets 2026: Japan, China, Pakistan & More

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally

SpaceX IPO 2026: History’s Biggest Stock Debut?

Oil Prices 2026: Inside the Hormuz Crisis That Won’t End

Algorithmic Dogfights: Why the U.S. and China Must Establish Rules of Engagement for Autonomous Air Power

Top US Convenience Store Chains: Store Counts, EV Charging, and Sales Trends

Who Is Shivon Zilis? The Neuralink Executive at the Center of the Musk–OpenAI Trial

Business Insurance: What Coverage You Actually Need and What It Costs in 2026

Global Economic Outlook 2026: 7 Forces Reshaping Markets, Trade and Business

Corporate America Faces a New Debt Test as US Borrowing Costs Surge

Is AI a Stock Bubble in 2026? What the Data Shows
-

 Markets & Finance10 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis9 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025