
Stocks
Q3 2026 Earnings Preview: Can Record Profit Expectations Keep Wall Street’s Rally Alive?

Stocks approached record territory as the third-quarter 2026 corporate earnings season gathered pace. Investors have substantial optimism about profits but also a complicated set of risks: borrowing costs, geopolitical energy shocks, narrow market leadership and doubts about whether AI spending will keep producing attractive returns. Earnings reports offer something social-media commentary cannot: company-specific numbers against which expectations can be tested.
The S&P 500 closed at 7,811.54 on Friday, October 9, according to the Associated Press, after gaining 0.6% for the session. A high stock index can be supported by improving fundamentals, improving valuations, or a combination. Earnings season helps reveal how much of the rally is backed by actual revenue, profits and revised guidance. AP market close.
FactSet’s key estimate: 29.6% expected growth
In research published October 9, FactSet said the S&P 500’s current third-quarter earnings growth rate was 29.6%. That is a blended or estimated earnings-season measure, not the final result for the entire index. FactSet further argued that normal patterns of companies beating estimates could push final reported growth above 35%. It is critical to attribute the higher figure as an analytical expectation, not a fact already achieved. FactSet, October 9.
The difference matters for both investors and editorial credibility. A reader seeing “S&P profits rose 35%” may assume results have been reported, while much of the quarter’s company-level information remains forthcoming. A good headline preserves tense: analysts expect, companies reported, or estimates imply. Numbers should be revised after additional disclosures, with the article’s update date changed accordingly.
Why AI is a major source of expected growth
Technology suppliers and businesses selling into AI infrastructure have seen demand for chips, networking and cloud capabilities. Large AI-oriented firms can deliver unusually fast earnings growth that influences aggregate S&P performance. A Financial Times analysis reported strong profit expectations driven in significant part by AI investment and cited Goldman Sachs forecasting a 27% year-on-year increase for the September quarter at the time of publication. Different forecasting organizations may report somewhat different estimates because of timing, methodologies and index coverage. Financial Times analysis.
AI’s influence cuts both ways. If capital spending accelerates, infrastructure providers may enjoy better near-term sales. But the companies purchasing equipment may experience pressure on future cash flows. A positive earnings result from an upstream chip supplier does not establish that a downstream AI application has produced attractive returns. For an earnings season described as “AI-led,” these layers must be kept distinct.
Banks are an early window into the rest of the economy
Major U.S. banks are among the firms expected to report prominently as the season develops. Their results can reveal changes in loan demand, deposits, interest margins, consumer credit and corporate investment appetite. A bank’s profits are influenced by trading activity as well as household borrowing, making financials a useful but imperfect proxy for overall economic strength.
Barron’s reported cautious investor sentiment ahead of results from institutions including JPMorgan and Bank of America, with questions around loan growth, trading, investment banking and funding costs. That coverage highlights an important distinction: strong analyst estimates can coexist with weak bank share prices when the market is concerned about sustainability. Barron’s banks preview.
For editors, bank earnings offer a chance to connect a headline number to the drivers underneath it. A trading-revenue surprise is not the same thing as a broad increase in customer lending. A favorable quarter from reserve releases is not the same as accelerating underlying demand.
Profit margins are the stress test
Corporate profit growth can result from faster sales, lower expenses, favorable mix or accounting effects. When revenue rises quickly but expenses rise more slowly, margins improve. Yet companies experiencing higher energy, borrowing or labor costs may face pressure even if total sales are still rising. Margin changes deserve as much scrutiny as earnings per share.
To compare businesses fairly, separate operating margins from net margins and GAAP results from management-adjusted metrics. Adjusted profitability measures can illuminate recurring performance but can also exclude substantial compensation or restructuring costs. Reconciliations in company filings matter. Commentary should not declare a new efficiency era solely because one adjusted metric rose.
Earnings beats are relative to expectations
A company can report growing profit and see its shares fall. Markets care about results relative to estimates and about forward guidance. If management announces a large revenue increase but expects slower future growth, the stock may decline because investors had anticipated an even stronger outlook. Conversely, a weak quarter can generate a share-price rise if the news is less bad than investors feared.
This is why a quality earnings article should answer at least four questions: What did the company report? What had analysts expected? What guidance changed? How did the share price move after the report, with a precise time reference? Avoid relying on a single social-media reaction or prematurely attributing every market move to one headline.
Does the rest of the market benefit from AI-driven profits?
A major issue is whether profit improvements are spreading beyond the highest-profile technology companies. Large index members have greater weight in the S&P 500, and strong results from a handful of leaders can dominate its earnings trajectory. The wider market may experience more uneven conditions, especially where debt costs, weak pricing power or shrinking demand weigh on smaller firms.
MarketWatch described an improvement in market breadth in the latest week, despite prior concentration in AI-linked shares. That provides a possible counterpoint to fears of permanently narrow leadership. MarketWatch breadth update. But a sustained broadening should be confirmed through both price data and profit revisions across sectors.
The strongest earnings season would be one in which more industries deliver genuine revenue gains, margins remain defensible and corporate guidance does not depend on endlessly rising financing commitments. The weaker version is one in which aggregate growth looks impressive but relies on relatively few extraordinary businesses.
Energy and rates could change management guidance
Energy prices influence transport, production and consumer spending. October’s Russian diesel arrangement temporarily reshaped fuel-market expectations, while conflict risks continued to cloud future supply. Those variables could affect management commentary even when reported September-quarter financial results predate the latest announcement. Reuters diesel reporting.
Interest rates are another powerful influence. In September, the Fed raised its policy target to 3.75%–4.00%, and the 10-year Treasury yield traded at elevated levels by October. Higher financing costs may constrain businesses with weak cash flows and significant borrowing requirements. However, stronger economic growth can also support profits despite those costs. An earnings season should test which companies actually have the pricing power and balance sheets to navigate this environment. Federal Reserve.
The earnings dashboard worth publishing each week
For each major reporting wave, show the percentage of S&P companies that have announced results, the blended earnings growth rate, revenue growth, the fraction beating estimates, and the direction of full-year guidance. Then include a sector table highlighting technology, financials, energy, industrials, health care and consumer-facing companies. A static earnings estimate from early October must not be presented as though it already incorporates late-October results.
Separate reported financials from projections. Update coverage at meaningful milestones and retain a revision history when numbers change materially. Cite primary investor-relations releases and SEC filings wherever possible, using analysts or data providers for consensus figures. This publication method is better for readers than repeating an aggressive headline each time a single company exceeds expectations.
Can profits keep the rally alive?
They could help, especially if earnings growth proves durable and broadens. But market outcomes will also depend on valuation, bond yields, policy uncertainty and what management teams say about future capital expenditure. The most productive question for investors is not whether Q3 growth looks large in isolation. It is whether the incremental profit justifies the market prices investors are already paying and whether cash flow supports further expansion.
For a finance news site, the editorial advantage is to follow those tests in real time. A disciplined tracker of estimates versus actual results can offer more repeat value than a one-off prediction about how high the S&P 500 will climb.
Frequently asked questions
What was FactSet’s Q3 2026 S&P 500 earnings-growth estimate on October 9?
The reported estimated growth rate was 29.6%.
Has S&P 500 Q3 earnings growth already exceeded 35%?
No final index-wide outcome was established by that analysis; FactSet said the rate might exceed 35% after companies report.
Why do banks matter early in earnings season?
Their reports can illuminate credit quality, deposit costs, corporate activity and risk appetite.
Does an earnings beat mean the stock will rise?
No. Market reaction depends on expectations, guidance, valuation and many other factors.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.


Markets & Finance
Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist
A stock market crash is a scenario to prepare for, not an event that can be declared merely because a few technology stocks fall. Reuters reported on October 12 that the S&P 500’s 2026 advance was relatively narrow, with more than four in ten constituents down for the year even as the benchmark had gained. That is a market-breadth warning worth analyzing, but it does not by itself prove that a crash is imminent. Sources: Reuters market breadth and Reuters bond market analysis.
The important context competitors can overlook
Watch the relationship among corporate earnings, long-term Treasury yields, credit conditions and the durability of AI spending. Higher yields can pressure expensive growth shares by raising discount rates, yet resilient earnings can offset part of that effect. It is important to distinguish a routine pullback, an index correction and a systemic crisis. None is the same as an unavoidable recession, and exact timing forecasts are notoriously unreliable. For primary-source checks and current reporting, see Reuters market breadth and Investor.gov. The key distinction is turn fear-driven headline into evidence-led risk analysis.
A correction, a bear market and a crash describe different price events. No single indicator can reliably predict a market collapse; portfolio resilience is more actionable. Research cutoff: October 12, 2026; confirm developing facts before publication.
A practical way to use this information
For a household, start with the financial plan: maintain cash needed soon, review whether holdings are excessively concentrated, check investment fees and avoid leveraged bets on a headline. A retiree drawing income has different exposure to early losses than a worker contributing for decades. Stress-test an illustrative decline, confirm how much would need to be sold, and document rebalancing rules before volatility arrives.
Crash risk or ordinary volatility? A four-part test
| Question | Evidence to gather | Why it matters |
|---|---|---|
| Is the weakness broad? | Number of stocks falling, sector breadth | A few giant companies can hide weaker participation |
| Is financing tightening? | Treasury yields and credit spreads | Borrowing stress can amplify selling |
| Are profits weakening? | Earnings revisions and guidance | Valuation may need to reset if cash flows disappoint |
| Is your plan fragile? | Near-term withdrawals and concentration | Personal exposure differs from market headlines |
The October 12 Reuters breadth report supports asking these questions, not publishing a certain crash date. Always specify what would falsify an alarming thesis.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Is there a confirmed market crash today?
The cited October 12 evidence describes market concentration and risk, not a confirmed broad-market crash.
Which signal should investors watch first?
No single metric works; consider breadth, earnings, funding conditions and your own time horizon together.
What would distinguish a correction from a crash?
Market vocabulary matters. A correction is commonly used to describe a broad decline of roughly 10% from a recent peak, while a bear market often refers to a fall of about 20%. “Crash” has no universally binding numerical definition; it often describes an unusually fast and disorderly fall. Those labels summarize price behavior but do not diagnose the economic cause. A 3% decline after a strong rally can feel alarming, especially in speculative stocks, yet it should not automatically be promoted as evidence that the entire market has entered crisis.
A more useful question is how many securities participate in a decline. Indexes weighted by company size can hide weakness beneath headline levels. When a handful of companies account for much of an index’s gains, weakness in smaller constituents may go unnoticed. Still, narrow breadth alone is not a reliable crash clock. It should be assessed together with earnings expectations, credit conditions, unemployment trends and funding-market stress. For real-time broad-market reporting, prefer clearly time-stamped sources such as Reuters.
Four risks investors can measure instead of guessing
Valuation risk: expensive shares can be vulnerable when projected growth disappoints or discount rates rise. Compare the valuation measure with realistic earnings scenarios rather than treating one ratio as a verdict. Concentration risk: calculate how much of a portfolio depends on a few stocks, industries or factors. Two funds can appear diversified while holding many of the same underlying companies. Liquidity risk: an investment may be difficult to sell near a quoted price during stress. Leverage risk: borrowed money and margin calls can turn an ordinary setback into a forced sale.
These risks interact. A portfolio concentrated in highly valued growth companies, financed partly with leverage, may be more fragile than a broadly diversified portfolio even if both posted similar returns last year. Conversely, a company with strong cash generation does not become risk-free merely because its balance sheet is healthy. Markets can reprice excellent businesses when required returns change. Good analysis distinguishes possible loss mechanisms from unsupported claims that a specific collapse is certain.
A stress test that does not require forecasting the market
Assume a household has $40,000 invested, needs $8,000 for tuition within nine months and can tolerate a temporary paper loss of $5,000. If a 20% market decline cut the account to $32,000, selling $8,000 for tuition would lock in a portion of the loss and leave less capital to recover. The important weakness is not the prediction of a 20% decline; it is using a volatile portfolio to fund a near-term unavoidable expense. A dedicated cash reserve can reduce that timing risk, though cash also has inflation and opportunity costs.
For longer-term savers, test the impact of several hypothetical market drops against current asset allocation and future contributions. Ask whether the household could maintain essential spending and avoid forced selling. This is more constructive than changing a retirement strategy in reaction to an intraday headline. It is also useful to review emergency liquidity, high-interest debt and insurance arrangements before increasing exposure to volatile investments.
Why an economic slowdown is not the same as a stock crash
GDP data, employment, consumer spending and corporate earnings influence markets, but share prices reflect expectations about the future. Stocks can fall ahead of a recession, rise while the economy is still weak or remain volatile without a recession occurring. Monetary policy can affect both discount rates and borrowing costs; its influence is important but not mechanically predictable. Financial news should not confuse a large move in Treasury yields with a confirmed default, or a disappointing earnings report with proof of an economy-wide breakdown.
Investors should separate observations from hypotheses: “credit spreads widened” is measurable; “credit spreads guarantee a crash next month” is speculative. Charts become more trustworthy when they show units, beginning and ending dates, and data sources. A scary percentage without a reference period may exaggerate or disguise risk.
Questions to ask before making portfolio changes
- What is the time horizon for this money and what spending does it need to cover?
- How concentrated is the portfolio in equities, technology or a single employer?
- Is there borrowing, margin exposure or a short-term cash obligation?
- Did the market move because of confirmed data, policy news or unverified speculation?
- Would a proposed trade still make sense if the market recovered tomorrow?
A clear checklist cannot eliminate losses. It can, however, keep a stressful search for “stock market crash” from turning into a decision based on a sensational headline alone.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
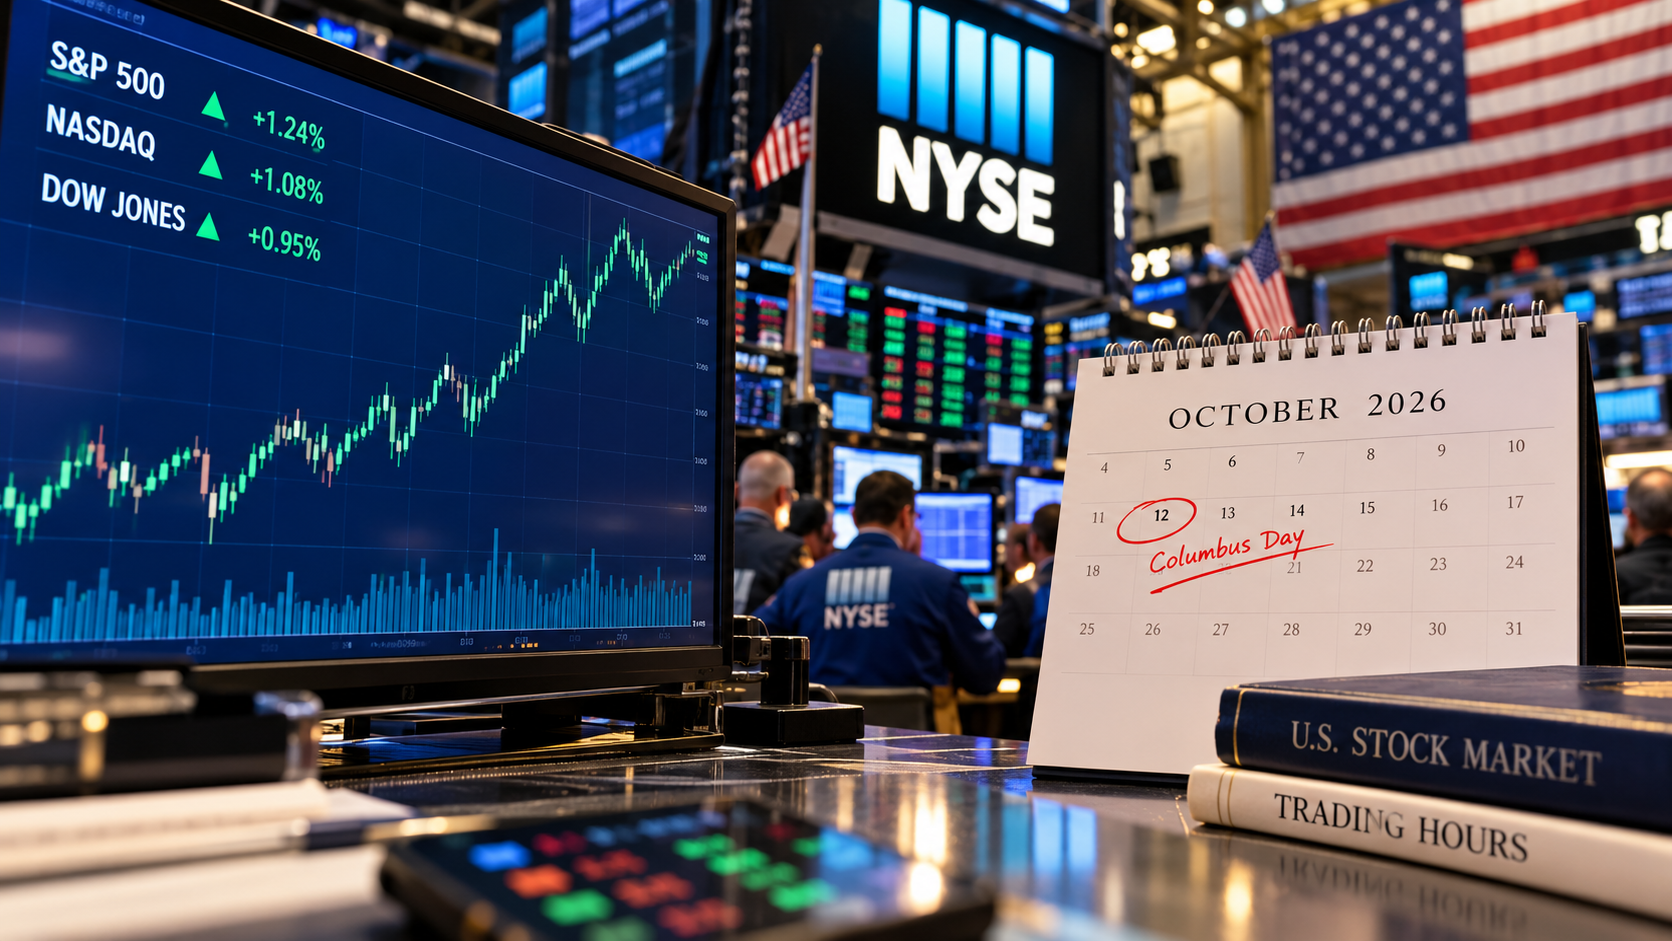
NYSE and Nasdaq are scheduled to trade their regular session on Monday, October 12, 2026, although the U.S. bond-market holiday schedule differs from that for stocks. Research cutoff: October 12, 2026; confirm developing facts before publication.
What is happening and why readers are searching
Yes. Monday, October 12, 2026 is Columbus Day, also observed by many as Indigenous Peoples’ Day, and the New York Stock Exchange and Nasdaq are scheduled to trade during their standard 9:30 a.m.–4 p.m. Eastern session. The bond market follows a different holiday schedule: SIFMA recommends a full closure in U.S. dollar fixed-income trading. Sources: NYSE and SIFMA holiday schedule.
The important context competitors can overlook
This distinction matters for more than trivia. A trader may see stocks move while some bond markets and banks are closed. Brokerage funding, transfer cutoffs and market data from less-liquid products can behave differently from a typical Monday. International exchanges observe their own holidays and may not follow the U.S. calendar. The federal holiday label alone does not tell a reader whether a particular financial instrument trades. For primary-source checks and current reporting, see NYSE and Kiplinger. The key distinction is separate equity, bond, bank and settlement schedules.
A practical way to use this information
Check your brokerage’s trading notice for options, mutual-fund cutoffs, fixed income and account funding. Avoid saying “the market is closed” without naming the asset class. Readers with urgent cash needs should confirm transfer and settlement arrangements directly with their institution. The next scheduled full U.S. stock-market holiday after October 12 is Thanksgiving Day, November 26, according to the exchange holiday calendars.
A holiday-hours comparison worth saving
| Market or service | October 12, 2026 | What to check |
|---|---|---|
| NYSE-listed shares | Regular session scheduled | Your broker and exchange notices |
| Nasdaq-listed shares | Regular session scheduled | Trading hours and order type |
| U.S. dollar bond market | SIFMA recommends closure | Fixed-income trading desk |
| Banks and transfers | Federal holiday may affect services | Your bank’s payment timetable |
NYSE exchange trading hours and the SIFMA holiday recommendation are different types of evidence. Neither establishes that every retail intermediary will offer normal transfer processing.
What to verify before making a decision
The right next step is to identify the source, timestamp and applicable market or jurisdiction. Check whether a number is a historical observation, official announcement, target, forecast or scenario. If you intend to act financially, legally or commercially, use the relevant provider’s current terms and obtain professional advice where appropriate. The sources cited here establish context; they are not a substitute for live prices, individual eligibility checks or binding agreements.
Reader questions
Can I buy U.S. stocks on Columbus Day?
Yes, the regular NYSE and Nasdaq session is scheduled.
Are Treasury bonds trading normally?
SIFMA recommends a U.S. bond-market holiday closure.
What “the market is open” actually means
The NYSE and Nasdaq trading session and the U.S. federal-holiday calendar are separate systems. On Monday, October 12, 2026, their standard core trading hours are scheduled to run from 9:30 a.m. to 4 p.m. Eastern Time. A share of a widely traded U.S. company can therefore change hands while many bank branches and government offices remain closed. But that statement does not tell you whether your brokerage’s customer-service desk is staffed normally, whether a fund values assets at its usual time, or whether a particular bond has a reliable two-sided quote. Those details depend on instrument, venue and broker.
For an investor outside the United States, convert Eastern Time carefully. Some countries move clocks on different dates, while others do not observe daylight saving time. A calendar showing “9:30” without a time zone is insufficient. Use the NYSE official market calendar as the first reference for exchange trading hours and your broker’s order preview for instrument-specific handling.
Stocks, Treasuries, funds and cryptocurrency are not interchangeable
A company’s listed common stock may trade normally even when the recommended U.S. bond-market session is closed. Treasury bonds, municipal bonds and corporate bonds do not operate in exactly the same way as exchange-listed shares. Fixed-income markets are fragmented, and a limited or irregular quoting environment can produce wider bid-ask spreads. Placing a market order in a thinly traded security can be more expensive than expected. Investors considering a bond trade should ask about dealer liquidity, execution timing and whether prices are executable rather than merely indicative.
Mutual funds, exchange-traded funds, stock-index futures and cryptocurrencies each have their own pricing mechanics. An ETF can trade on the stock exchange, but its underlying holdings could include instruments in markets observing a holiday. Mutual funds normally process orders according to their published prospectuses and cutoff policies. Futures venues publish product-specific schedules. Cryptocurrency markets trade around the clock, but uninterrupted availability does not guarantee tight spreads. Checking one “market open” headline is not enough to infer all these schedules.
Order types and settlement around a federal holiday
Imagine an investor who places an order for shares on Monday morning. The exchange may execute it during the ordinary equity session, but settlement and cash-transfer processing can be affected by banking holidays and applicable business-day conventions. A trade confirmation, settled-cash display and withdrawal availability are not the same event. The safest approach is to check the brokerage’s holiday operations notice rather than assuming that an executed trade instantly creates withdrawable cash. Different account types may impose additional restrictions.
For a volatile security, an investor can compare the displayed bid and ask before trading and consider a limit order rather than automatically accepting an uncertain market price. This does not guarantee execution. It does specify the least favorable purchase price or sale price the investor is willing to accept. Orders entered outside the core session may also have distinct participation, duration and execution rules, which a broker should disclose.
The practical Columbus Day checklist
A useful market-hours answer should cover more than the yes-or-no question. Check the exact date and year, the trading venue, the time zone, the security type, your brokerage’s processing calendar and any early-closing notice. For dollar-denominated fixed income, consult the SIFMA holiday schedule. For your specific bank, inspect its branch and electronic-transfer information. Do not assume a bank holiday means cards stop working or electronic trading becomes impossible; these are distinct operations.
Holiday headlines can also expire quickly. A search result from 2025 or 2027 might display the same Columbus Day keywords yet give the wrong weekday or market specifics. Editors should include “Monday, October 12, 2026” near the top and remove any blanket claim that all financial markets are open. If the story is reused next year, the date and all supporting calendars need new verification.
What to do if a trade or transfer is urgent
For an urgent payment, ask the receiving institution about cutoff times and whether it recognizes the holiday as a processing day. For an urgent investment order, verify the specific instrument’s status directly in the broker interface and review the quote rather than trusting a static article. Where timing is not essential, waiting for ordinary liquidity can be more sensible than accepting a large spread. These are general execution considerations, not recommendations to buy or sell any particular security.
The broader lesson is that exchange trading, dealer liquidity and banking settlement are three separate clocks. Columbus Day demonstrates why a short market-hours answer is useful as a starting point but inadequate for every investor’s operational decision.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.
The S&P 500 is an index of large American companies, but it is not a democratic vote in which every stock contributes equally. In the familiar market-capitalization-weighted version, the largest companies have a disproportionate influence on the headline index. When major technology and AI businesses rise substantially, they can lift the benchmark even while the typical constituent delivers a much less impressive return.
That is the main idea behind “market breadth.” Breadth asks how widely a rally is distributed rather than how far the index has risen. It is especially important in a market where investors discuss AI leadership, high interest rates and uneven sector performance at the same time. Weak participation can reflect vulnerable concentration, but it can also create the conditions for a healthy rotation if lagging groups begin to catch up.
The October 9 close and the deeper split
According to the Associated Press, the S&P 500 ended Friday, October 9, at 7,811.54, up 0.6% for the session after a strong week. That tells readers the headline direction of the benchmark, but not how many companies had participated over preceding months. The S&P 500’s performance is compatible with both a broadly rising market and a narrowly led market, depending on the period and indicator examined. AP market close.
A separate Barron’s report highlighted that only 46% of S&P 500 constituents stood above their 200-day moving averages when the index set a record earlier in the week. That is an indicator observed at a particular time with a particular definition. It should not be carelessly extended to every U.S. listed stock or to a later trading session. Barron’s breadth analysis.
Why the 200-day moving average gets attention
A 200-day moving average smooths roughly ten months of daily trading prices. Analysts often treat a share price above that moving average as evidence that its longer-term trend is positive, although this is an imperfect and backward-looking measure. If a large share of an index’s constituents trade below that line, it indicates many individual stocks are struggling to maintain their own long-term trend even if the benchmark is holding up.
There is no universal rule that a particular percentage automatically predicts a market crash. Broad rallies can weaken before falling, but narrow markets can remain narrow for extended periods. Moving averages can be distorted by sharp drops followed by recoveries, by industry cycles and by seasonal trading. A reader should see breadth as a risk gauge and diagnostic tool, not an infallible timing signal.
Cap-weighted versus equal-weighted performance
One practical way to assess concentration is to compare a capitalization-weighted S&P 500 fund with an equal-weight version of the same constituents. In an equal-weight approach, each stock starts with approximately the same weight at scheduled rebalances. If a few mega-cap companies dominate, the cap-weighted index often outperforms. If gains spread to smaller members, equal weight may improve relative to market-cap weighting.
This difference also changes sector exposure and rebalancing costs. Equal weighting is not an automatically better investment strategy. It generally increases exposure to smaller index constituents, adds periodic rebalancing and can behave differently when interest rates rise or liquidity deteriorates. The comparison is useful because it reveals a hidden property of the rally rather than because one benchmark should always be preferred.
Friday provided a counterargument to the “breadthless” label
The latest weekly picture was not uniformly negative. MarketWatch reported an improvement in breadth after nearly two months of narrow AI-led leadership, with the equal-weight S&P 500 outperforming the cap-weighted benchmark over the week. That move matters because a broadening market could support a rally without depending entirely on the largest technology companies. MarketWatch breadth recovery.
One stronger week is not enough to declare a durable rotation. A genuine improvement would likely appear across multiple indicators, including the number of stocks setting new highs, sector leadership, advancing versus declining issues and performance beyond mega-cap technology. Analysts should measure whether the improvement lasts through earnings reports and changing bond yields.
Concentration can coexist with excellent fundamentals
A narrow rally is not always speculative. The largest firms can have stronger cash generation, more diversified customers and exceptional earnings growth. Investors may reasonably prefer them during uncertain periods. The challenge arises if prices incorporate so much favorable news that even strong results cannot meet expectations, while other stocks remain weak because financing conditions and end demand are deteriorating.
The divergence also produces a measurement problem. A highly profitable company may be expensive relative to realistic future growth, while an inexpensive cyclical business may remain cheap because its market is weakening. Breadth alone cannot decide which. Balance sheets, earnings guidance, valuation and sector demand are necessary complements.
Interest rates explain part of the divide
The bond market adds context. Higher Treasury yields can pressure businesses with heavy refinancing needs, property exposure or long-duration anticipated profits. In September, the Fed raised its short-term policy target to 3.75%–4.00%, while the 10-year Treasury yield was above 5% around the October close. Federal Reserve policy statement; H.15 Treasury data.
Large cash-rich businesses may be better equipped to absorb financing costs than weaker borrowers. That difference can cause stock-performance concentration even without a collapse in overall economic activity. If bond yields stabilize, lagging sectors might recover. If credit conditions deteriorate, the headline index could eventually face pressure from weakening profits beyond the biggest winners.
What would make the narrowness dangerous?
Concentration becomes more concerning when the leading companies also lose momentum, estimates are revised downward, credit spreads widen and breadth remains weak. A divergence in which the index climbs while most components trend lower is a warning to examine market fragility. But its interpretation depends on the period and context.
Investopedia reported analysts highlighting the historic narrowness of recent leadership while also considering opportunities in underperforming sectors. That two-sided framing is useful: weakness creates risks for passive headline interpretation, but it can also create pockets of relative value for investors whose horizons and risk tolerance differ. Investopedia market-breadth analysis.
A simple breadth dashboard for news readers
A credible weekly update could include five indicators: percentage of index constituents above their 50-day and 200-day averages; equal-weight versus cap-weight return; new 52-week highs against lows; fraction of sectors gaining over the month; and percentage of earnings estimates revised upward. These measures capture trend, leadership and business performance from different angles.
Publish a date and universe beside every chart. “Forty percent of stocks” is meaningless without specifying S&P constituents, all U.S. listed common shares or an exchange-specific sample. Similarly, price breadth measured on Tuesday should not be attached to Friday’s benchmark close without labeling both dates. A transparent methodology earns more trust than a dramatic title alone.
The practical takeaway
The October stock rally has a hidden divide, but it is not a single-direction forecast. Strong benchmark results and weak individual participation can both be true. The improvement during the latest week is encouraging for broader participation, yet it requires confirmation. Rather than treating the S&P 500 as a complete portrait of corporate America, readers should follow who is actually rising, whether earnings growth is spreading and whether financial conditions permit a durable recovery in lagging groups.
Frequently asked questions
What is market breadth?
A set of measures showing how many stocks participate in a market advance or decline.
Does an all-time S&P 500 high mean most stocks are at highs?
No. Because of index weighting, a minority of large companies can disproportionately drive the benchmark.
Is weak breadth proof a crash is coming?
No. It highlights potential fragility but is not a reliable stand-alone market-timing rule.
Why does equal-weight performance matter?
It offers a second view of index participation and can show when smaller constituents are catching up with mega-cap leaders.
Discover more from The Economy
Subscribe to get the latest posts sent to your email.

Stock Market Crash in 2026? Warning Signs, Scenarios and a Calm Investor Checklist

Peso Mexicano vs Dólar Estadounidense: A Practical USD/MXN Guide for October 2026

Is the Stock Market Open on Columbus Day 2026? NYSE, Nasdaq and Bonds Explained

Concert Ticket Prices in 2026: Dynamic Pricing, Fees and How to Buy Safely

High-Yield Savings Accounts in 2026: How to Compare APY Without Chasing a Headline

EU-China Trade Deal 2026: How Beijing and Brussels Avoided a Trade War—and Who Wins

Social Security 2027 COLA Announcement: Date, Formula and What Retirees Should Check

China’s AI Microdrama Boom: How Beijing Is Reshaping Global Media

Q3 2026 Earnings Preview: Can Record Profit Expectations Keep Wall Street’s Rally Alive?

Russia Diesel Deal 2026: Oil Prices and Inflation Risks

Fed Rates 2026: Treasury Yields, Bonds and SGOV Explained

S&P 500 Market Breadth 2026: Weak Rally or Rotation?

The AI Capex Boom: Data Centers Reshaping Growth

Palantir Stock in 2026: Extraordinary AI Growth

PSX Forecast 2026: KSE-100, IMF Reviews & Geopolitics

Middle East War Economics 2026: Oil Prices & Energy Markets

China Stocks Today: Are Big Economies in Asia Nearing a Market Bottom?

Crypto Daily Outlook: Bitcoin, Altcoins, and the Future of Decentralized Finance

Global Pension Systems Ranked: The World’s Best and Worst Retirement Frameworks

World’s Largest Economies: Ranking the Top Global Powers

Elon Musk’s Next Moves: Disrupting the 2026 Global Economy

Pakistan Economy 2026: Inside the SBP’s Balancing Act

GasBuddy Market Insights: How Crude Price Shifts Impact Local Fuel Cost Averages

World Bank & IMF Reports 2026: Why the “3% Growth” Consensus Is Actually a Debate

Global Equity Market Divergence: US Tech vs. European Dividend Stocks vs. Asian Growth

Crude Oil & Petroleum Market Analysis: OPEC+ Decisions and Price Forecasts

IMF & World Bank Global Economic Outlook: Growth Forecasts Across Europe and Asia

Silver Price Today: Why the Xi-Trump AI Standoff Is Fueling a Safe-Haven Rally
-

 Markets & Finance9 months ago
Top 15 Stocks for Investment in 2026 in PSX: Your Complete Guide to Pakistan’s Best Investment Opportunities
-

 Analysis8 months ago
Johor’s Investment Boom: The Hidden Costs Behind Malaysia’s Most Ambitious Economic Surge
-

 Analysis8 months ago
Top 10 Stocks for Investment in PSX for Quick Returns in 2026
-

 Banks9 months ago
Best Investments in Pakistan 2026: Top 10 Low-Price Shares and Long-Term Picks for the PSX
-

 Analysis8 months ago
Brazil’s Rare Earth Race: US, EU, and China Compete for Critical Minerals as Tensions Rise
-

 Investment9 months ago
Top 10 Mutual Fund Managers in Pakistan for Investment in 2026: A Comprehensive Guide for Optimal Returns
-

 Global Economy10 months ago
15 Most Lucrative Sectors for Investment in Pakistan: A 2025 Data-Driven Analysis
-

 Global Economy10 months ago
Pakistan’s Export Goldmine: 10 Game-Changing Markets Where Pakistani Businesses Are Winning Big in 2025